

Liability
- Fitter struck by a swinging load
- Production line damaged while lifting in a machine
- Care, custody and control limit matched to your most expensive load
A self-employed Rigger slings loads worth more than his entire business; without cover for property in your care (opzicht) and a suitable sum insured, many sites will not even let you in.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Business quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen Insurance.
Additional questions follow per chosen Insurance.
Additional questions follow per chosen Insurance.
Additional questions follow per chosen Insurance.
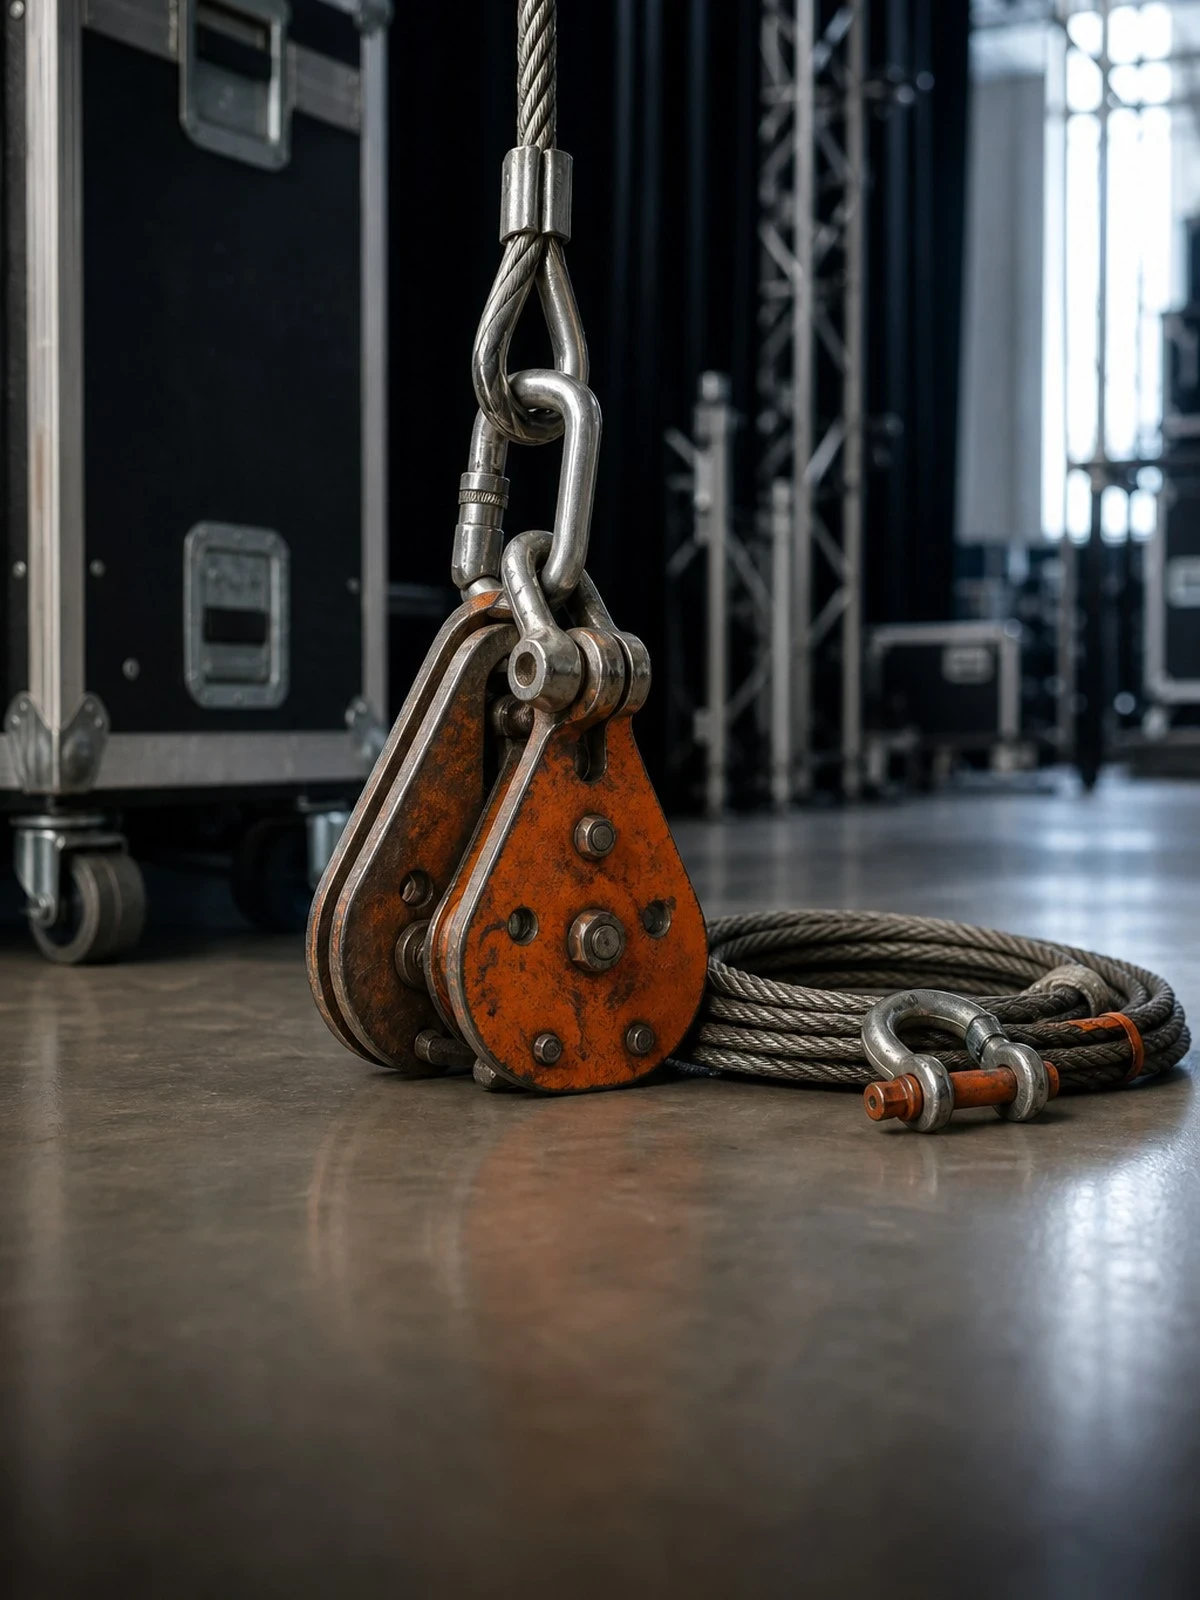
Self-employed riggers work in two worlds. In Industry and construction, they prepare lifts with mobile cranes: determining weight and centre of gravity, choosing slings, chains and spreader beams, and guiding the load until it is in place. In the events Industry, they hang trusses, lighting and sound from hoists above audiences and performers. Unlike our general page on riggers and lifting supervisors, this page is about the self-employed (zzp) rigger, who has no employer, is personally liable and in hire contracts often takes on more than the law requires.
The legal framework is set out in the Working Conditions Decree (Arbobesluit), in the section on Work equipment for lifting and hoisting: Article 7.18 for lifting and hoisting machinery and Article 7.20 for lifting accessories such as slings, chains and shackles, supplemented by the inspection requirement of Article 7.4a. In practice, this means demonstrable periodic inspection, at least once a year, and never exceeding the working load limit (WLL). A rigger who uses an uninspected sling or an incorrect slinging method will be at the centre of the investigation by the Netherlands Labour Authority (Arbeidsinspectie) and by the insurers of all parties involved if an accident occurs.
For the policy, this means three choices: a sum insured that meets the contract requirements, cover for property in your care (opzicht) for the load itself with a limit that suits your loads, and proper documentation of who is in charge of the lift. We review your hire contracts with you and tailor the policy to them.
We compare your personal liability Insurance (AVP) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Personal liability Insurance (AVP)
 Compare
 Get covered
The cover you need as a self-employed (zzp) Rigger depends on the value of the loads, your clients' requirements and how dependent you are on your own ability to work.
Injury and property damage to third parties caused by an error in the slinging method, plus cover for the load on the hook in your care.
Your own slings, chains, hoists and van are your working capital; being out of action through injury stops your income immediately.
If you hire a fellow self-employed rigger or bring a helper, employer's Liability arises under Article 7:658 of the Dutch Civil Code (BW).
What is covered
| Situation | AVB | BAV | Cyber |
|---|---|---|---|
| Injury to a visitor or customer | Yes | No | No |
| Damage to a client's property | Sometimes | No | No |
| Financial loss caused by an advisory or calculation error | No | Yes | No |
| Downtime after a ransomware attack | No | No | Yes |
| Data breach involving personal data | No | Sometimes | Yes |
| Damage to property in your care | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the Insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what Execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of Contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No Menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference in the policy for a self-employed Rigger.
As an employee, your employer is liable under Article 6:170 BW for mistakes you make at work; only in cases of intent or deliberate recklessness can the employer recover the costs from you. As a self-employed worker, that buffer disappears. If a wrongly chosen sling snaps and a fitter is injured, he or his employer's insurer can hold you personally liable. Personal injury claims involving permanent injury quickly run into several hundred thousand euros because of lost earning capacity. If you work as a sole trader (eenmanszaak), such a claim hits your private assets directly; a private limited company (bv) offers only limited protection, because the Rigger carrying out the work can also be held personally liable in tort.
Riggers regularly sling loads worth more than their business: a transformer, a chiller, a prefabricated staircase or a lighting bridge. Damage to property in your care, such as the load on the hook, falls under care, custody and control (opzicht) and is excluded on most business liability (AVB) policies or covered only up to a sub-limit. If you work with more expensive loads, ask for a higher limit for property in your care or agree in writing that the load is covered during the lift by the client's contractors' all risks (CAR) or transport Insurance, with a waiver of recourse against you. Put that agreement in the lifting plan or the order confirmation, not just in an email.
Crane companies, main contractors and event producers often have self-employed riggers sign an indemnity: you accept liability for all damage arising from your work, sometimes including damage caused by mistakes of others in the crew. A business liability policy (AVB) generally covers only the liability you would have under the law; anything extra you take on by contract remains uninsured. Contracts regularly require a sum insured of € 2.5 million or more and a certificate of Insurance in your name. Show us contracts before signing; a limited change to the clause is often enough.
If you use your own slings, chains and shackles, you must be able to prove the inspection of each item with a register and a legible WLL marking. If you use the client's equipment, check the inspection label and the condition of the equipment before every lift. After an accident, the Labour Authority and insurers look at who was in charge of the lift, who chose the slinging method and whether a load was suspended above people. A self-employed Rigger without a documented role in the lifting plan is often assigned a large share of the responsibility in that investigation. Have your task recorded in writing and keep the lifting plan with your project records.
Questions from self-employed riggers about their Insurance.
Not by law, but in practice it is. Crane hire companies, contractors, industrial clients and event producers ask for a certificate of Insurance with a minimum sum insured when hiring you, often € 2.5 million per claim and sometimes more in heavy industry or energy. Without that document, you will not get onto the site. The Insurance also protects your private assets against injury claims you could never bear alone.
The premium depends on turnover, sum insured, the limit for property in your care, sector and claims history. For a self-employed Rigger with a sum insured of € 2.5 million and limited cover for property in your care, the premium is, as an indication, between a few hundred and just over € 1,000 a year. Work in petrochemicals, offshore or above audiences at events, and a high limit for property in your care, increase the premium. We request quotes from several insurers that accept the profession.
Not on the business liability policy (AVB); that is your own equipment and requires tools or goods Insurance. Pay attention to the conditions for theft from a van: many insurers require signs of forced entry and restrict cover at night to a van in a locked building or on a locked site. Rejection after inspection, wear and tear and loss on a project are not covered; damage from a sudden accident sometimes is.
That depends on the type of contract. If you work as a self-employed person through an agency, you remain liable yourself and need your own business liability policy (AVB). If you are employed by a secondment company, liability runs through its policy and you are covered as an employee. If in doubt, ask for the secondment company's certificate of Insurance and check whether hired-in staff are named as insured persons. We compare it with your own policy.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass insures is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass insures (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.