

Liability
- Cable and pipe damage
- Adjacent buildings during demolition
- Injury to bystanders
A Kobelco crawler excavator of 14 to 50 tonnes works in demolition and earthmoving close to adjacent buildings, cables and contaminated soil; the policy must explicitly recognise that work.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
Kobelco builds hydraulic crawler excavators in the SK series, from the compact SK17 to the 50-tonne SK500, with the SK210 and SK260 as popular mid-range models in the Netherlands. The brand also supplies special long-boom demolition machines, such as the SK400 and SK550 demolition, and material handlers. As an indication, a new SK210 costs between € 180,000 and € 250,000, including quick coupler and buckets; a demolition version with a high-reach boom comes in well above € 500,000.
Plant and machinery insurance for a Kobelco has three components. Liability cover pays for damage you cause to others with the machine: a gas pipe that is struck, a damaged adjacent building during demolition, injury to a bystander. This cover is compulsory as soon as the machine goes on the public road and is practically indispensable for work on a construction site. Own-damage cover (casco) covers damage to and theft of the machine itself, including attachments such as a sorting grapple, breaker or concrete crusher if they have been declared. On top of that come downtime cover and transport between sites.
Because Kobelcos are often deployed on demolition, remediation and inner-city projects, insurers assess their use carefully. In the application we state the actual work, the attachments, deployment through subcontracting and the locations, and compare the conditions of several insurers on precisely those points.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
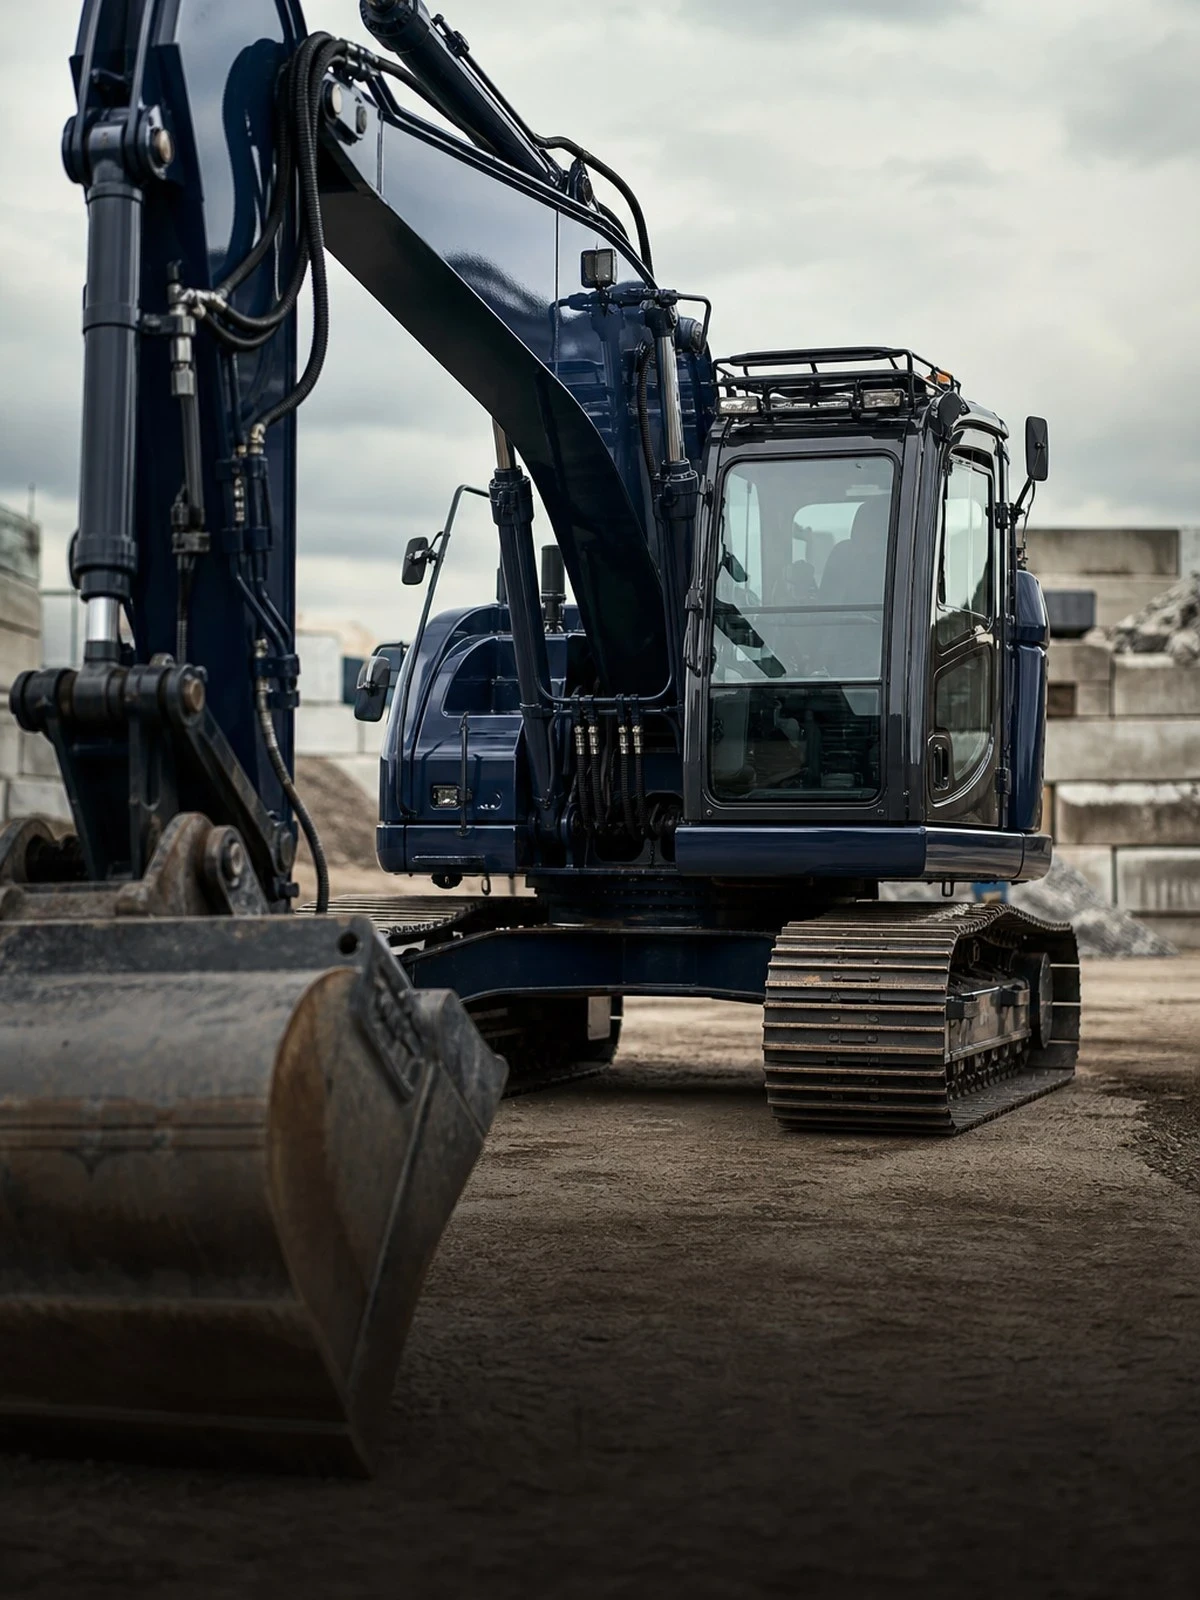 Plant and machinery insurance
 Compare
 Get covered
Cover for a Kobelco depends on the tonnage and value, the type of work, the attachments and whether the machine also goes on the road or in transport.
Damage to cables, pipes, adjacent buildings and people during demolition and excavation with the Kobelco; compulsory once the machine goes on the road.
Damage to and theft of the machine itself, including declared attachments such as a sorting grapple, breaker and concrete crusher.
Reimbursement of hire costs for replacement equipment during downtime after damage, and cover while the machine is transported on a low loader.
What is covered
| Situation | Covered |
|---|---|
| Theft from the building site | Sometimes |
| Fire and storm damage | Yes |
| Inherent defect in the hydraulics | Sometimes |
| Damage to cables and pipes | Sometimes |
| Normal wear and tracks | No |
| Damage due to deferred maintenance | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Six situations from deploying Kobelco equipment in which the policy makes the difference.
In inner-city demolition with an SK260 or a long-boom demolition version, the machine stands a few metres from the neighbouring building. Vibrations, a falling section of wall or a misjudged party wall cause cracks, subsidence or a collapsed extension. Insurers treat demolition as an increased risk: some policies exclude damage to adjacent buildings or limit it to a lower amount, others require a structural pre-condition survey of the surrounding buildings. Without that survey, the dispute about existing cracks is virtually unwinnable. We include demolition work explicitly in the application and look at which insurer covers it without restriction.
The most common liability claim with an excavator is a struck gas pipe, data cable or water main. A damaged fibre-optic cable can easily cost tens of thousands of euros once businesses suffer an outage; a gas pipe leads to evacuation and repairs by the network operator. The WIBON requires a KLIC notification before you dig and careful excavation in line with the CROW 500 guideline. Insurers generally cover cable damage but apply a higher excess and may restrict cover if there was no KLIC notification. Keep records of notifications and trial trenches per project; that is your evidence when you claim.
A Kobelco is rarely used with just a bucket. Sorting grapples, hydraulic breakers, concrete crushers and pulverisers cost € 20,000 to € 80,000 each and regularly move from one machine to another. Own-damage cover only applies to attachments listed on the policy with make, type and value. A breaker hired from a colleague falls under a separate clause for hired equipment. Theft of attachments left next to the machine overnight is a real risk and is often only covered if they are in a locked container or attached to the machine. We keep the list of attachments per machine up to date.
Kobelcos are widely used for soil remediation and on former industrial sites. Anyone who mixes contaminated soil with clean soil during excavation, or hits an oil drum still buried in the ground, causes environmental damage. The liability cover of a plant and machinery policy usually excludes environmental damage or limits it to sudden events with a low maximum. Contractors who regularly carry out remediation work need separate environmental damage insurance, aligned with the plant and machinery policy and the business liability policy (AVB). We make sure the three policies dovetail, so that a leaking hydraulic hose on a remediation site does not fall between two stools.
A crawler excavator does not simply disappear, but theft of complete machines on a low loader does happen, particularly from remote construction sites at the weekend. For machines above a certain value, insurers set requirements: an immobiliser or PIN code, a track-and-trace system with a recognised certificate, and storage on a locked site outside working hours. Kobelco supplies its own telematics system on newer models, but that does not always meet the insurer's security requirement. In the event of theft without the required security, the payout may be reduced. We check in advance which security class goes with the value of your machine.
Many Kobelco owners work as subcontractors or hire out the machine with an operator to a main contractor. The question then is whose policy pays in the event of damage. The project's construction all risks (CAR) insurance generally covers the works themselves, but not your machine and not always your liability. The main contractor may shift liability onto you in its terms and conditions. Hire without an operator is excluded by most plant and machinery policies unless it is included. We read the hire terms alongside you and record in the policy that deployment for third parties, with and without an operator, is covered.
Frequently asked questions about insuring a Kobelco.
As soon as the machine goes on the public road, even just to drive from the low loader to the construction site, the insurance obligation under the Motor Vehicle Liability Insurance Act (Wet aansprakelijkheidsverzekering motorrijtuigen) applies and third-party liability cover is compulsory. A crawler excavator that works exclusively on enclosed sites formally falls outside that obligation, but the liability risk on a construction site is so great that liability cover is indispensable in practice. Clients also almost always require proof of insurance.
For a new Kobelco, the purchase value is insured, including quick coupler and standard buckets; many insurers offer a new-for-old arrangement for the first two to three years. After that, the current value applies, which falls quickly for an excavator running 1,500 to 2,000 hours a year. Attachments are valued separately. Stating too low a value leads to underinsurance when you claim. We determine the value based on year of manufacture, operating hours and the current used-machine market, and adjust it every year.
Hire without an operator is excluded by most plant and machinery policies unless it is included, because the insurer then has no insight into who is operating the machine. Hire with your own operator is generally regarded as normal use. With hire without an operator, the hirer often has to take out cover themselves, or you take out a hire clause with a higher premium. Record in the hire agreement who pays in the event of damage and what the hirer's excess is.
An SK210 that spends three weeks at the dealer after overturning costs you the hire of a replacement machine of roughly € 1,500 to € 2,500 a week, plus a project that comes to a standstill. Downtime cover on the plant and machinery policy reimburses the hire costs of replacement equipment for an agreed period, often up to 30 or 60 days, with an excess of a few days. Loss of turnover itself is generally not covered. For a contractor with one machine, this extension is often worthwhile.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.