

Liability
- Cables and pipes
- Damage to buildings
- Injury to bystanders
Terex equipment lifts people and materials into the air, and at height the risk changes character: what goes wrong comes down, onto the façade you are working on or onto whatever is standing below.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Terex is active across a wide range, from dumpers to access platforms and cranes, but the part of the range that occupies insurers most is working at height. With equipment that raises a bucket or a basket, the emphasis lies not with the machine but with the zone beneath it. That is where cars are parked, where the public walks and where the building you are working on stands.
Falling objects are the most common cause of loss in this segment. A tool, a bolt or a panel of cladding does serious damage from ten metres up. That is damage to third-party property or personal injury and runs through your liability cover, not through the own-damage cover on the access platform.
The building you are working on is a category of its own. Many liability policies exclude damage to the work object: precisely that part of the building you are working on.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
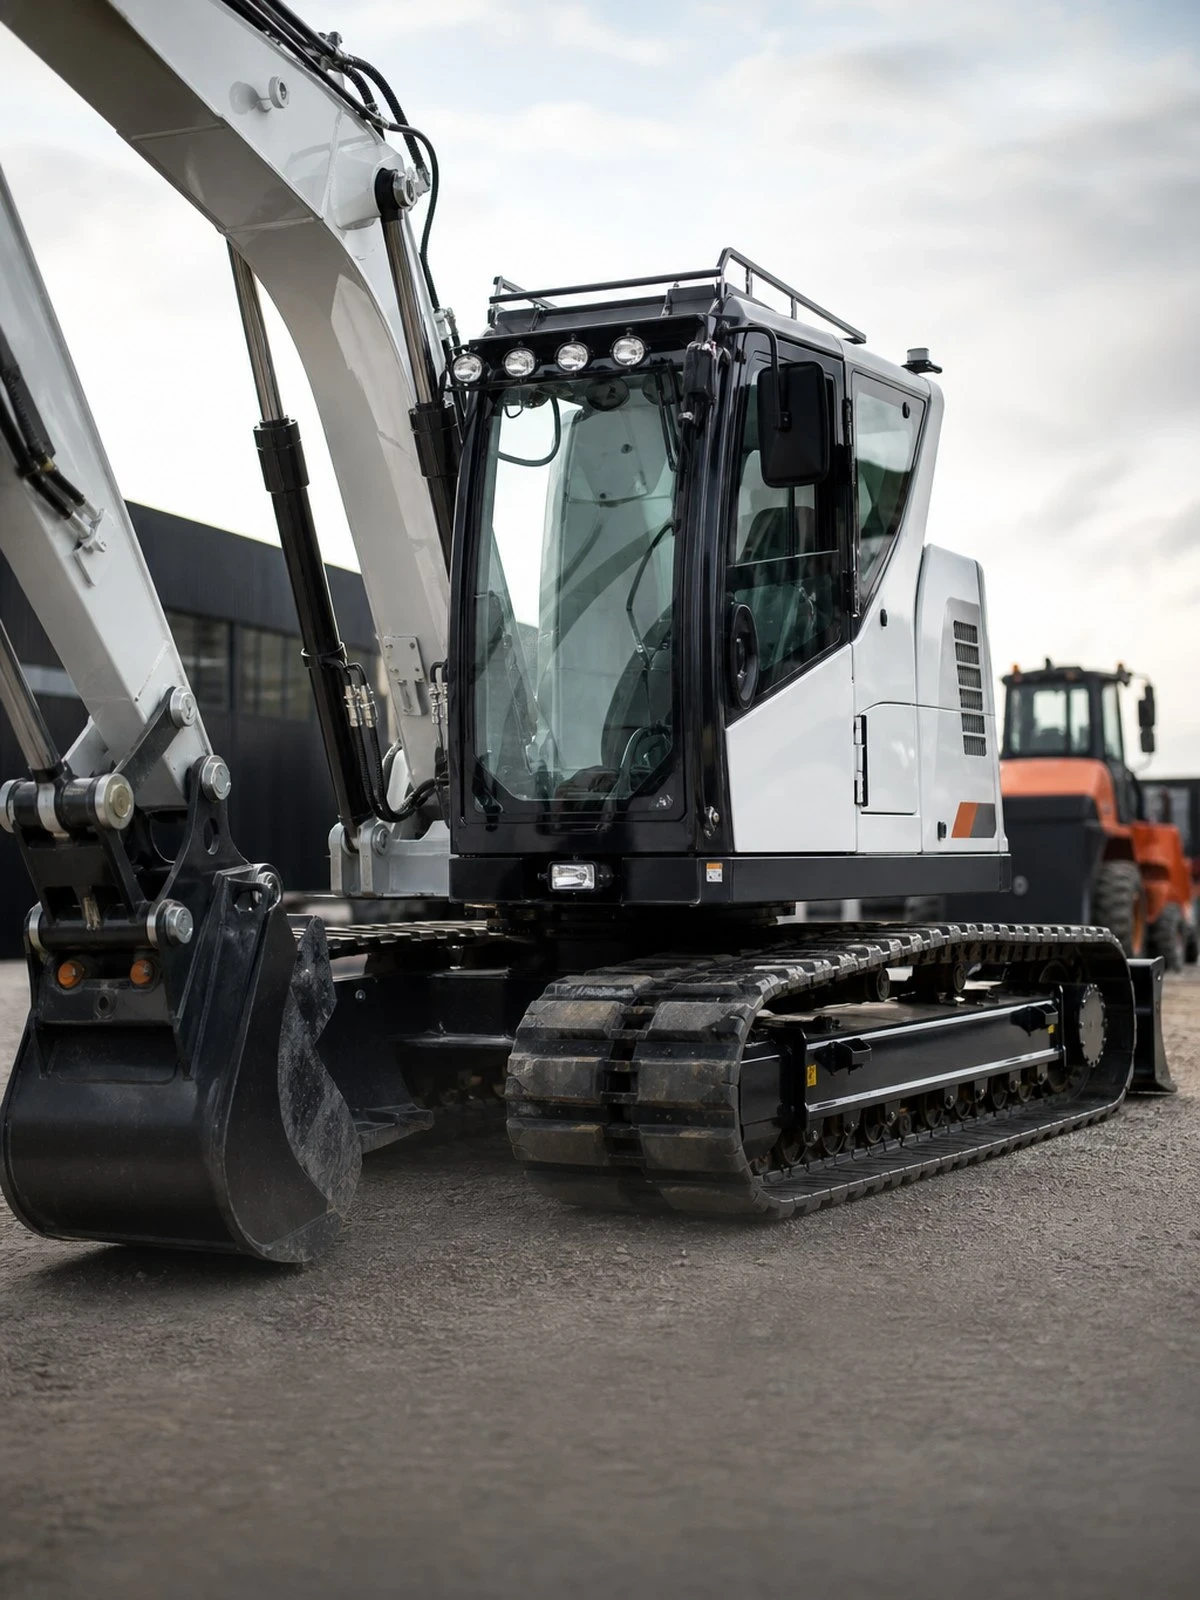 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to and theft of the machine, including inherent defect.
What comes into play with breakdown and transport.
What is covered
| Situation | Covered |
|---|---|
| Theft from the building site | Sometimes |
| Fire and storm damage | Yes |
| Inherent defect in the hydraulics | Sometimes |
| Damage to cables and pipes | Sometimes |
| Normal wear and tracks | No |
| Damage due to deferred maintenance | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Tools, fixings and detached façade components fall straight down. The damage that causes to parked cars, to a roof or to a passer-by is liability damage under Article 6:162 of the Dutch Civil Code. When such a claim is reported, insurers look first at how the area beneath the basket was cordoned off and at how tools were secured. If both were missing, that affects your position, even where the cover itself is in order.
If during the work you damage the glazing, the frames or the cladding you are working on, the care, custody and control exclusion comes into play: damage to the work object is excluded on many policies, while damage to the rest of the building is covered. In façade maintenance that distinction decides almost every claim. Ask for an extension for items being worked on and check the limit that applies to it.
Hanging a load on the rail, taking a window unit up in the basket or using the machine to pull something: it happens daily and it falls outside the manufacturer’s specification. Insurers exclude damage arising from use for which the work equipment is not intended, and from overloading the basket. An expired inspection is also a ground for declining a claim, because the soundness of the work equipment is then not established.
At height the danger is not in the ground but in the air. A boom or basket that comes too close to a high-voltage line or an overhead contact line causes flashover, injury and a network outage. The network operator recovers the repair costs and sometimes the consequences of the outage as well. Keep to the prescribed safety distances, record that they were discussed, and check whether your cover includes damage to networks without restriction.
Access platforms are subject to annual inspection. Without a valid certificate you are in a weak position when you claim.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
Often not. Most liability policies exclude damage to the object you are working on, while damage to the rest of the building is paid for. In façade maintenance that distinction is decisive. Ask for an extension for items in your care, custody and control or for the work object, and check which limit applies.
That is damage to third-party property or personal injury and runs through your liability insurance under Article 6:162 DCC. The insurer will look at how the area beneath the basket was cordoned off and at how tools were secured. If the area was not cordoned off, that strengthens the allegation and can affect how your claim is settled.
Only where the manufacturer has provided for it and the load chart allows. Hanging a load on the rail does not come under that. Use outside the intended purpose of the work equipment and overloading of the basket are excluded as standard, so that after a loss you bear both the machine and the liability yourself.
The network operator recovers the repair costs and possibly the consequences of the power cut as well. That is liability damage, but insurers will ask whether the prescribed safety distance was maintained and whether the risk was discussed beforehand. Record those arrangements for each project and check whether damage to networks is insured without an additional restriction.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.