

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
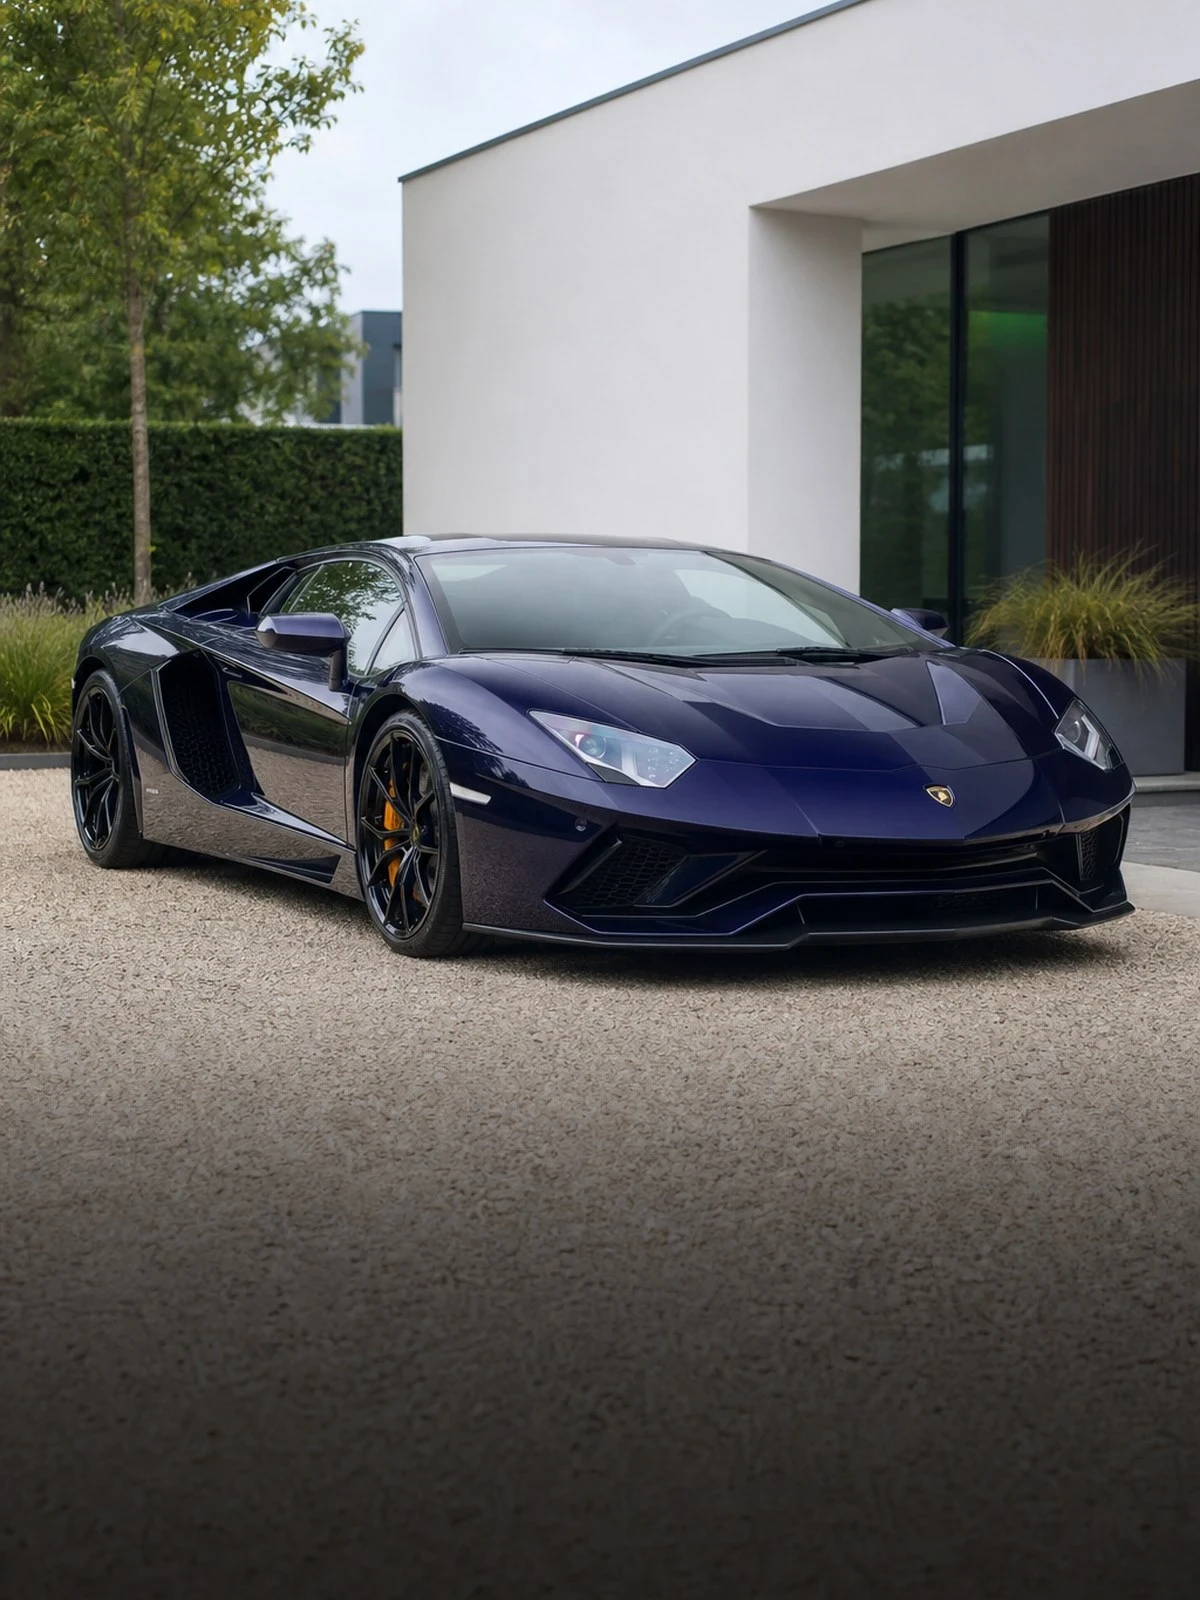
A Lamborghini stands out, is exceptionally wide and low, and is lent or hired out more often than other cars: those three characteristics determine where this policy goes wrong.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The top models are built around a carbon fibre monocoque. Such a tub is not straightened or welded: it is assessed, and the verdict is often that the car can no longer be economically repaired. As a result the question of exactly what the insured value is arises far sooner on these cars. Without an a prior valuation under Article 7:960 of the Dutch Civil Code you end up arguing that out after an accident.
The claims that actually occur are very ordinary. Because of the width, the low ground clearance and the limited view to the rear, most damage arises at low speed: ramps in car parks, speed humps, drives and bollards. A front splitter making contact with asphalt is own-damage in its own right and counts in your claims history as normal, however slight the incident seems.
The third point is who is behind the wheel. These cars are regularly lent, taken to events or made available for payment as a driving experience. Hire and any form of use for payment are excluded as standard. That is no formality: after a claim the payment comes to light and the cover for the whole event lapses.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Carbon fibre does not deform like metal. It either fails or stays intact, and damage is not always visible from the outside. If the monocoque is affected, a write-off often follows rather than a repair. That is precisely why the recorded value is the most important part of your policy. Have the valuation report set out the exact specification, the paint finish and the options, and note the period of validity included in the policy.
Front splitters, side skirts and the underside of the bumper are damaged by speed humps, ramps and kerbs. A lifting system for the front axle limits that, but does not cover it. This damage is own-damage and costs you no-claims years. So with small amounts always work out whether paying yourself is cheaper than the loss of a step and the excess together.
These cars attract attention and that leads to scratches, damaged paint and contact damage while parked on the street. Vandalism and damage by unknown parties usually fall outside the cover under third-party, fire and theft and are only covered under a comprehensive form. Insurers therefore often make requirements as to storage. If you regularly park the car on the public road, declare that, because a different form of storage affects both acceptance and payment.
Lending occasionally to someone you know is usually permitted, provided that person falls within the declared group of drivers and no age exclusion applies. As soon as there is a payment, even if it is petrol money or a driving experience, it is hire and the cover has lapsed. Use as a prop in commercial filming falls under that too. If you do want that, separate hire cover is needed.
This is what people ask us most.
Only if you want to claim. It is own-damage, so reporting it usually means losing no-claims years plus your excess. Work out what the repair costs and set that against the effect on the premium over several years. On these models, however, splitter parts are rarely cheap, so make that calculation with a concrete estimate in hand and not by feel.
He may if he falls within the declared group of drivers and meets any minimum age. Check whether your policy works with a fixed main driver or with an open group, because that differs by insurer. If you ask for a payment, in whatever form, it is hire and the cover lapses. That distinction really is checked after a claim.
Only under comprehensive own-damage cover. Under third-party, fire and theft, vandalism and damage by unknown third parties are excluded, because that form is aimed at fire, storm, theft and glass damage. Always report it to the police and record the place and time, even where the culprit remains unknown. Without a police report many insurers refuse notifications of this kind after all.
A technical assessment follows rather than an immediate repair. Carbon fibre does not always leave damage visible, so the structure is assessed for strength. If the verdict is that repair is not justifiable or not economic, the car is written off and the recorded agreed value counts. Without a valid valuation you fall back on market value at that moment.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.