

Liability insurance for a self-employed tiler
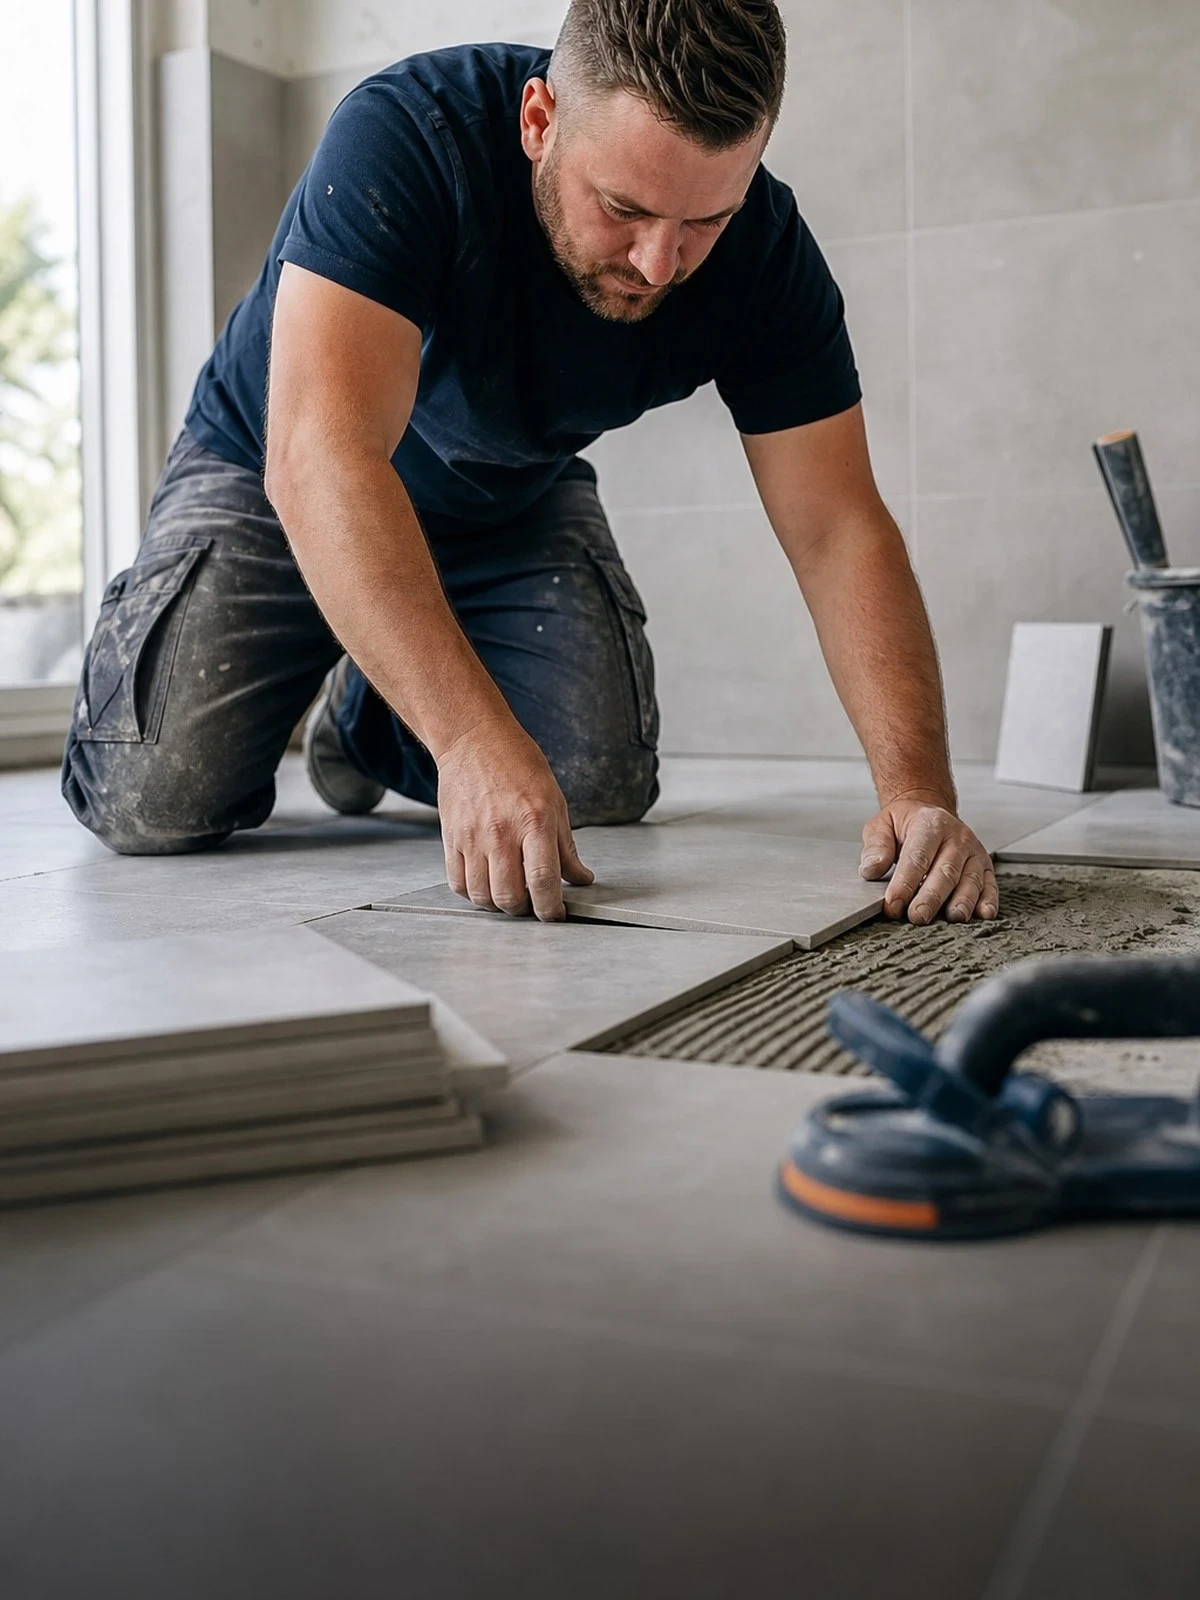
In tiling the risk sits behind the tile. A waterproof layer that does not run through is noticed by nobody on the day of handover and by everybody six months later, usually on the ceiling below.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
A liability insurance for businesses pays for injury and damage to other people's property. In tiling that almost always comes down to one scenario: water that escapes under the tiles through a pipe penetration, a wall-floor joint or a floor with the wrong fall, and reappears a storey lower. The damage to the ceiling, the contents and the finishes at the neighbours' is property damage to a third party and that is what this policy is intended for.
Retiling the same bathroom is not. Putting right your own work is excluded on every AVB, even where the work has to be broken out to reach the leak. That is the sharpest distinction in this trade: you pay for the bathroom, the insurer pays for the ceiling below. The same boundary applies to tiles you break while laying them, because that is material in your keeping.
Two other items belong elsewhere. A client who withholds the final instalment because he does not like the grouting is a dispute about performance and not a liability claim; legal expenses insurance (rechtsbijstandverzekering) exists for that business legal expenses insurance. And knee or lung complaints from years of laying and cutting are a question of income, for which disability insurance is the appropriate route.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Where things go wrong in tiling
Four subjects that determine a claim for a self-employed tiler.
The waterproof layer under the tile
Joint tapes, collars around penetrations and a liquid membrane running through everywhere: if one transition is not right, a leak arises that only becomes visible months later. Photograph the waterproofing you applied before you tile. In a claim that is the only evidence left of it, because the system lies under a floor that has to be broken out first.
Tiles the client bought himself
If you break material the client purchased while laying it, that is damage to property you have in hand. The care, custody and control exclusion makes that your cost, unless you take cover for property being worked on. It becomes worse if the batch is sold out and the colour difference with the reorder remains visible. That argument is then no longer an insurance matter but a supply matter.
The substrate you find
A deflecting timber floor, a screed that has not cured or levelling compound laid by someone else causes cracks and hollow-sounding work. If you did not lay the substrate yourself, note at the start what you found and where you entered a reservation. Without that, the complaint stays with you and runs into the exclusion for defective work of your own, even where the cause lies beneath your tiles.
Drilling, cutting and the pipes behind
In a bathroom, water pipes, underfloor heating and electrics run just below the finish. If you strike one, the consequential damage to the house is insurable property damage; retiling the part broken open is not. It is also best to cut wet: dry cutting ceramics produces respirable silica dust, and that is an exposure with a long tail.
What does your premium depend on?
- Turnover or days worked: the basis for calculating the premium
- Type of work: bathrooms, floors, facades or swimming pools
- Type of buildings: flats bring a greater risk of leaks reaching neighbours
- Property being worked on: included or not, and up to what amount
- Supply of materials: whether you buy tiles and adhesive yourself or the client supplies them
- Excess per claim: a higher excess lowers the premium
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | Basic | Extended |
|---|---|---|
| A leak under your tiling damages the ceiling and contents of the neighbour below | Yes | Yes |
| A tile falls from the scaffold onto the neighbour's car | Yes | Yes |
| A newly laid poured floor in the hall is scratched because you drag material across it | No | Provided that |
| Asbestos turns out to be under the old floor adhesive and the house has to be decontaminated | No | No |
| The main contractor charges a penalty because the bathrooms were finished later | No | No |
| Dust from dry cutting settles on a newly fitted kitchen that has to be cleaned | Provided that | Yes |
Extended here means a policy with cover for property you have in hand; redoing your own tiling remains at your expense in both cases.
Frequently asked questions
This is what people ask us most.
The neighbour below has water damage from a bathroom I tiled.
The damage at the neighbours' is third-party property damage and covered in principle, provided you are liable under Article 6:162 of the Dutch Civil Code. Report it immediately and admit nothing: the cause may also lie with a plumber or with the shower drain. Breaking open and retiling your own work to reach the leak remains at your expense.
I broke the client's tiles while laying them. Is that covered?
Only with cover for property being worked on. Without that extension, material you are laying falls under the care, custody and control exclusion and you pay for the replacement yourself. For large or expensive batches, ask for that cover in advance and watch the limit per event; with natural stone or large-format ceramics it is quickly too low.
The floor has started to crack. Is that automatically down to me?
No. Whoever holds you liable must show that there was a fault on your part and that the damage results from it. Deflection of a timber floor, a missing movement joint in the screed or a substrate loaded too early are causes that lie outside your work. Your notes and photographs of the substrate at the start are decisive here.
Do I need liability insurance as a self-employed professional?
It is not compulsory by law, but the risk bears no relation to the size of your business: one leak in a block of flats can affect several homes. Besides, contractors, construction firms and VvE managers generally require a policy schedule before you start work. Without cover you bear the costs of legal defence as well as the compensation.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a self-employed plastererCovering up, moisture, adhesion
- Liability insurance for a self-employed paverSubsidence, trips, substrate
- Liability insurance for a self-employed demolition contractorStrip-out, load-bearing parts, hired equipment
- Liability insurance for a self-employed carpenterPipes in the wall, finished floors, measuring
- Liability insurance for a tiling businessSeries losses, supply, lifting
- Liability insurance for a self-employed service engineerDiagnosis, switching back on, your own parts
- Liability insurance for a self-employed mechanicProperty being worked on, call-out service, downtime
- Liability insurance for an air conditioning firmRefrigerant, condensate drainage, certification