

Liability
- Cables and pipes during excavation
- Impact damage to buildings and fencing
- Injury to bystanders
LiuGong wheel loaders and excavators are keenly priced, but parts supply and current value determine how long you are out of action after damage and what you get back.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
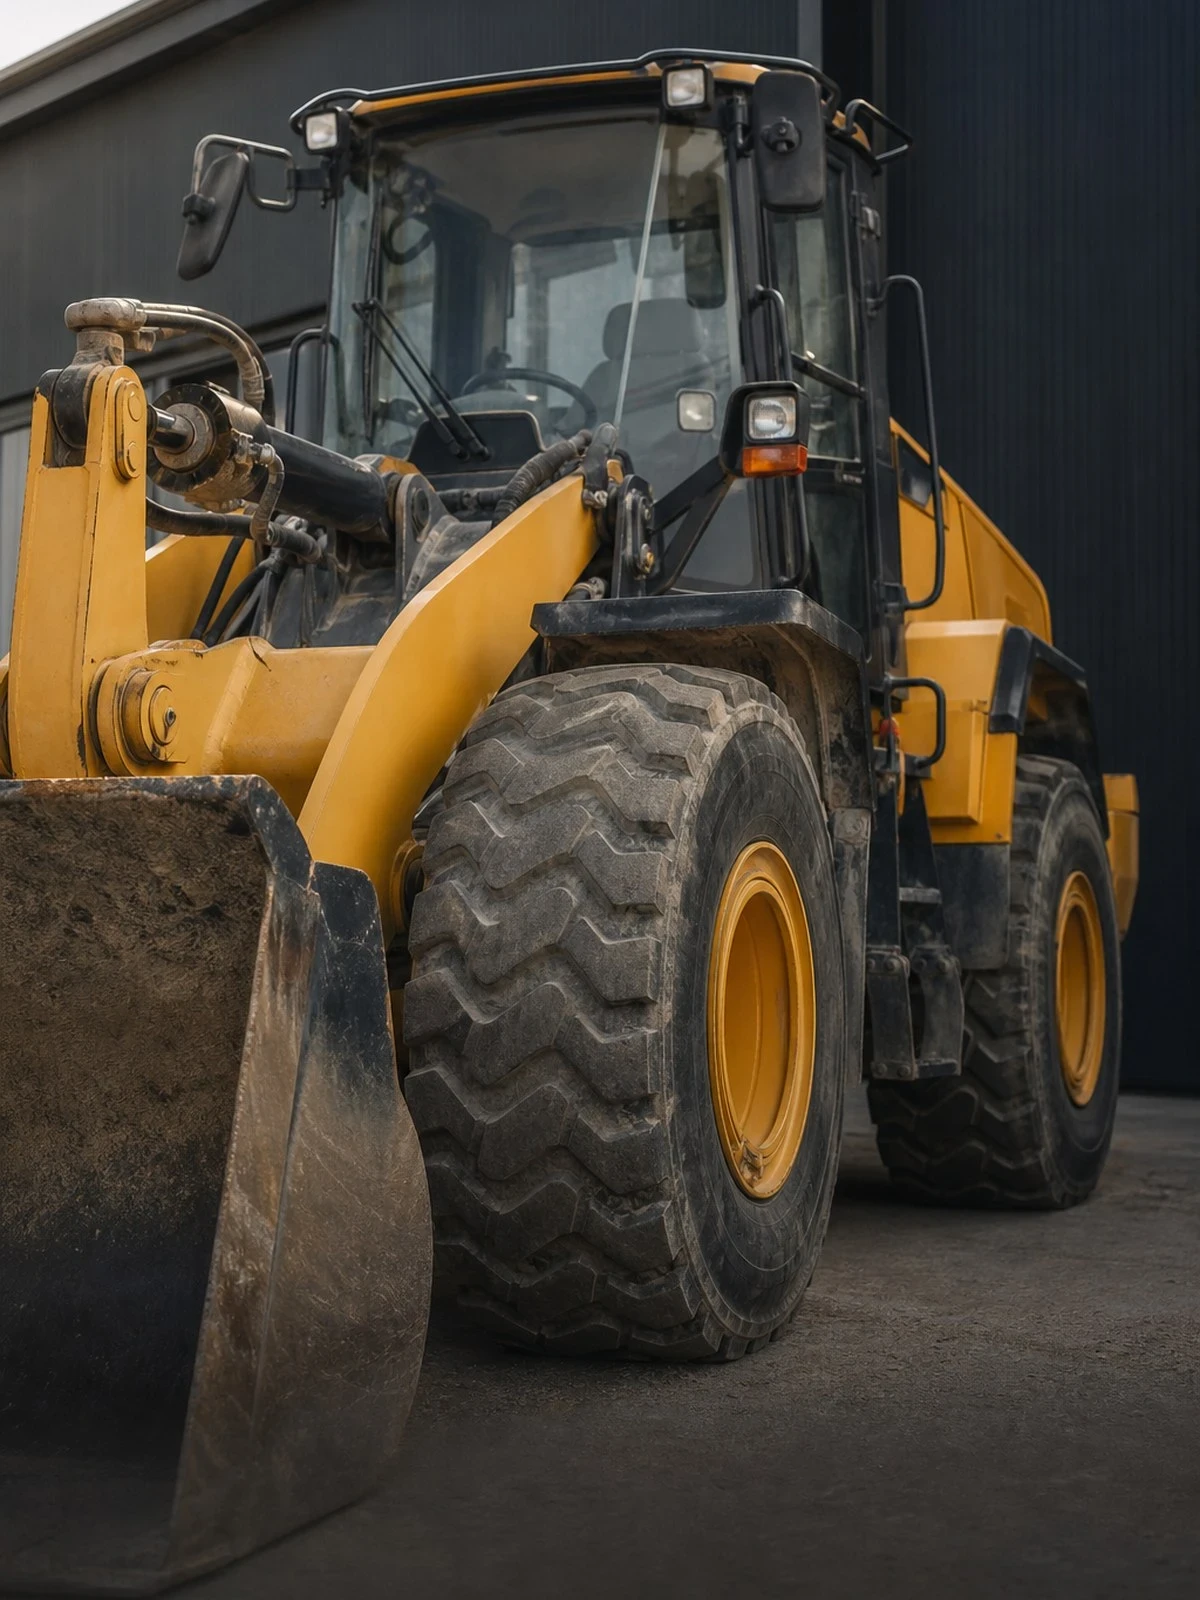
LiuGong is a Chinese manufacturer of earthmoving and loading equipment, known in Europe mainly for wheel loaders and crawler excavators, supplemented by mini and midi excavators, telehandlers and aerial work platforms. The machines are sold in the Netherlands through dealers and are often chosen by contractors, agricultural contractors and recycling companies looking for a robust machine at a lower purchase price than the well-known European, Japanese or American brands.
That lower purchase price has consequences for insurance. The current value can fall more quickly and the second-hand market is smaller, so in a total loss the question arises which value the insurer will use. Choose deliberately between a new-value, purchase-value or current-value arrangement and keep the sum insured up to date. In addition, the availability of parts determines how long a machine is out of action after damage: not every part is in stock at the dealer.
We insure LiuGong equipment as construction equipment, with liability, own-damage cover and, where needed, cover for hiring replacement equipment. To do so, we compare several insurers and pay attention to the acceptance of this brand, which is not the same with every company.
A mortgage, loan or investment often touches your insurance too. We look at the bigger picture and point you to the right specialist whenever something falls outside insurance itself.
 Financial
 Overview
 Advice
Cover for a LiuGong machine depends on the valuation arrangement, the type of work, the storage location and how long you can absorb downtime.
Damage you cause to others with a LiuGong loader or excavator, on site and on the road.
Damage to and theft of the machine, with a valuation arrangement that matches the purchase price.
Costs if the machine is waiting for parts after damage or is moved to another site.
What is covered
| Situation | Covered |
|---|---|
| Theft from the building site | Sometimes |
| Fire and storm damage | Yes |
| Inherent defect in the hydraulics | Sometimes |
| Damage to cables and pipes | Sometimes |
| Normal wear and tracks | No |
| Damage due to deferred maintenance | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Six points that come into play when insuring LiuGong equipment.
A LiuGong wheel loader is cheaper to buy than a comparable machine from a European brand, and the residual value follows the same pattern. In a total loss, a current-value policy pays what a comparable machine costs at that moment, and with a smaller second-hand market that value is harder to establish. A purchase-value arrangement in the first years avoids discussion. Also keep the sum insured up to date: if the machine is underinsured, the insurer may apply the average clause to partial damage.
After damage to, for example, a boom, cab or hydraulic block, the part sometimes has to come from a central warehouse in Europe or from the factory. That can take longer than with brands that have a large Dutch dealer network. Own-damage cover pays for the repair, not for the days the machine stands idle. If you depend on a single loader at a recycling yard or agricultural contracting business, it is wise to take out cover for hiring replacement equipment, with an indemnity period that matches realistic lead times.
LiuGong wheel loaders are widely used to move rubble, green waste, compost and wood chips. On such sites, combustible material builds up around the engine and exhaust, and fire is one of the biggest own-damage risks. For this use, insurers often ask about daily cleaning and sometimes about an automatic fire suppression system. Tyres and windows also suffer damage more quickly from sharp material; on many policies such damage is covered only to a limited extent or counts as wear and tear. We state the use correctly in the application.
Not every insurer has experience with LiuGong equipment. Some companies accept the brand without further ado, others ask for additional information about the dealer, maintenance or security, or apply a higher excess. This is mainly due to unfamiliarity with claims history and repair costs. By comparing several insurers you avoid being tied to a single offer. Keep the purchase invoice and maintenance records; they help with acceptance and with assessing a claim.
Mid-sized excavators and loaders are stolen for export, often at the weekend. Attachments such as buckets, pallet forks and quick couplers also regularly disappear. For higher values, insurers set security requirements, such as a track-and-trace system, an immobiliser or storage on a locked site outside working hours. Check whether the machine's telematics are accepted as a tracking system. Declare attachments separately with their value, so that they too are covered in the event of theft.
With a LiuGong crawler excavator, groundwork inevitably brings you close to cables and pipes. Damage to a gas pipe or fibre-optic cable falls under liability cover, but insurers expect you to make a KLIC notification in advance, check the location with trial trenches and dig carefully in line with the applicable guidelines. If you work as a subcontractor, also read the main contractor's terms: they often state that you remain liable for damage caused by your machine.
Questions owners of LiuGong equipment ask us.
The premium is often lower because it is partly based on the sum insured, which is generally lower for LiuGong. On the other hand, an insurer may apply a higher excess or extra conditions for less familiar brands. Use, security and your claims history also weigh heavily. A comparison between insurers gives the best picture.
For a new machine, you declare the replacement value including attachments and options, as stated on the purchase invoice. For a used machine, the purchase price or a current market value. Declaring too low a value lowers the premium, but can lead to underinsurance when a claim arises. Have the value adjusted periodically, especially if you add attachments or the machine stays in service for years.
Not as standard. Own-damage cover pays for the repair or the value of the machine, but the cost of hiring a replacement loader usually falls outside it. For that you take out additional cover for hire costs or business interruption, often with a waiting period of a few days and a maximum per day. For a brand whose parts are not always immediately available, that is worth considering.
Self-propelled equipment that drives on public roads generally needs a registration number and is then subject to compulsory third-party liability (WA) insurance as a motor vehicle. A policy that only covers the machine as equipment on site is not enough for this. If the loader regularly travels between sites or to customers, we arrange the motor vehicle cover together with own-damage and liability cover for the work.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.