

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
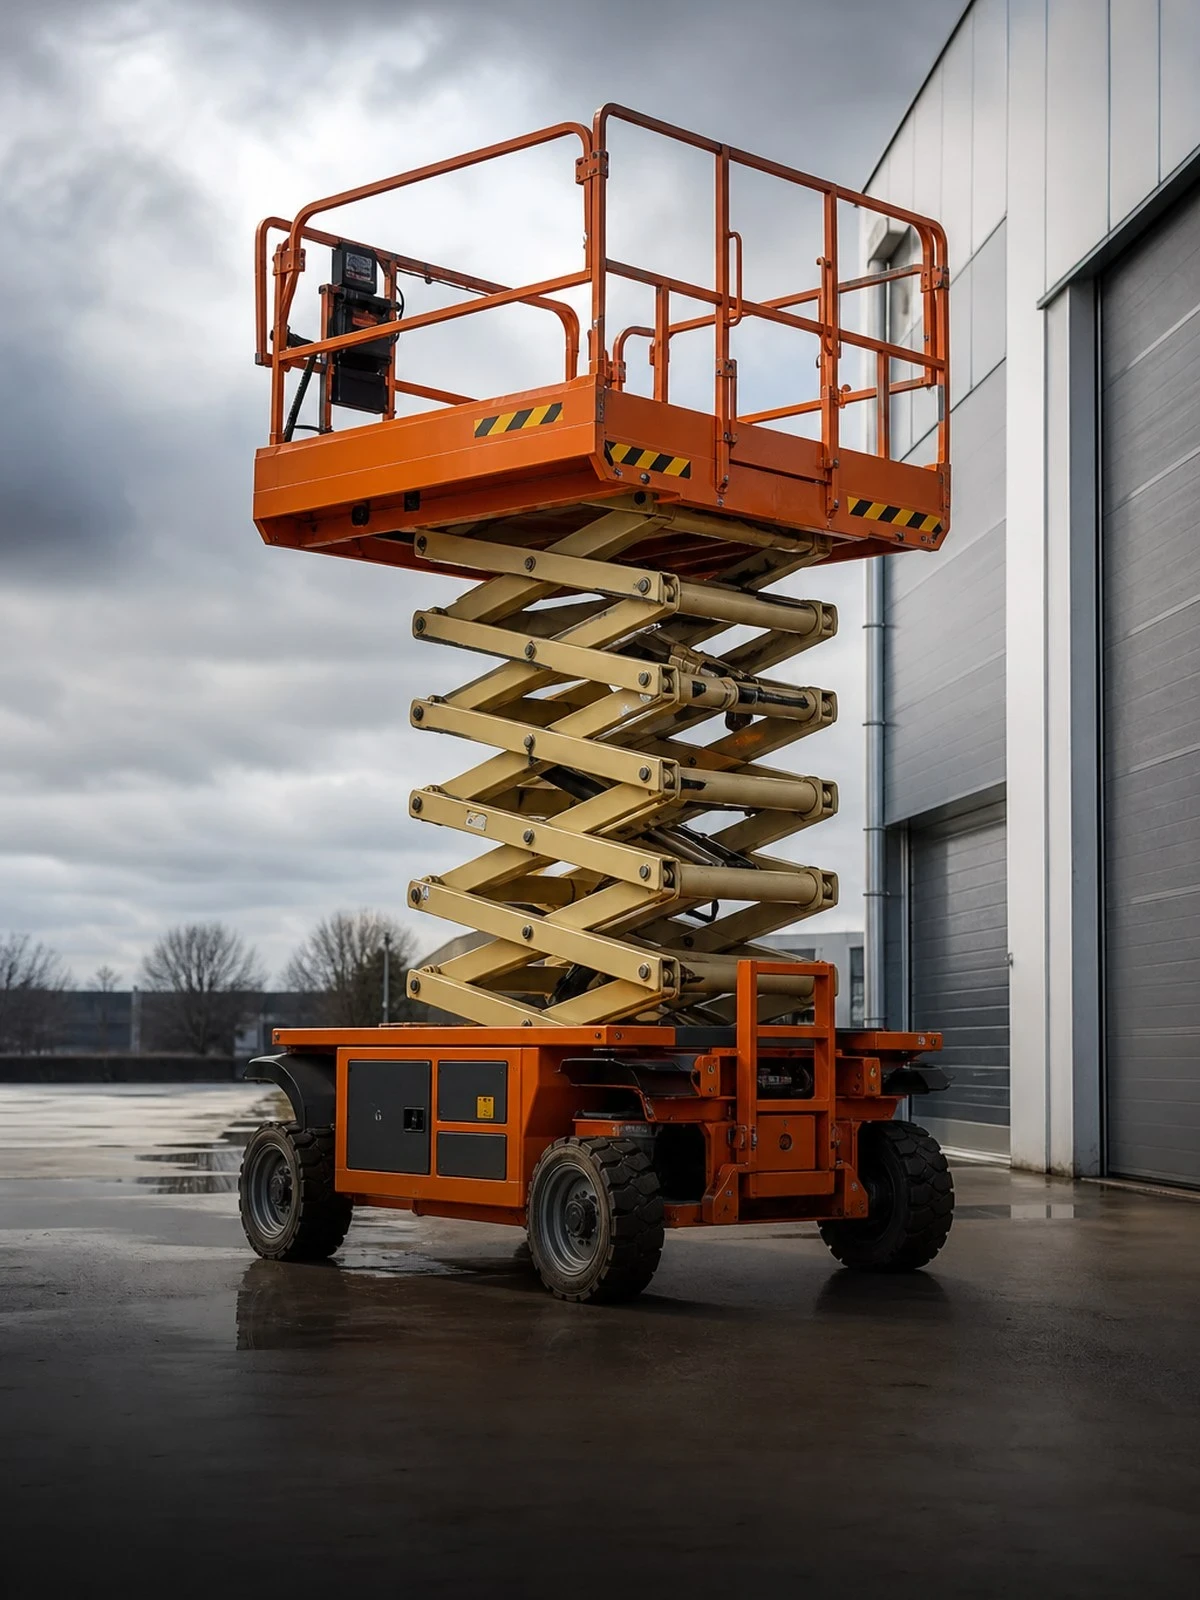
A scissor lift usually works indoors, where the floor beneath the machine and the services above it determine the risk.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The weight of a scissor lift rests on four small, hard wheels. That creates a point load which an upper floor, a parking deck or a basement deck cannot necessarily take. Sagging or cracking means damage to your client's building and therefore liability, not own damage. Asking the building manager for the load capacity and recording that in writing is therefore not a formality but your defence.
The second risk is above the machine. A platform moving upwards enters the zone of sprinkler heads, cable trays, air ducts and lighting. A sprinkler head that is struck floods a building, and that water damage to contents and stock runs higher than any damage to machinery. Look before you go up and limit the final height if there are services in the way.
Third: a machine built for indoor use is soon operating well beyond the limits of its specification outdoors. Small wheels on gravel or an uneven building site, and wind on an extended platform, are the usual causes of tipping. We test that use when applying for your plant and machinery insurance.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
On an upper floor, parking deck or basement deck the question is whether the structure can take the point load of four wheels plus the platform and the people on it. Ask the building manager for the permitted floor loading and record in writing that you did so. Use load-spreading platesif necessary. If the floor sags, that is damage to someone else's building and the load figure you obtained becomes the heart of the file.
Sprinkler heads, cable trays, air ducts, lighting and ceiling grilles sit at exactly the height at which you are working. A sprinkler head that is struck causes water damage to contents and stock throughout the building. That is liability towards the owner and the tenants. Establish what is above the platform before you go up and limit the lifting height if services are in the way.
Most scissor lifts have small wheels, a limited permitted gradient and a low wind class. On a building site with gravel, ruts or an unmade surface such a machine tips over at the smallest unevenness. If you work outdoors, choose a version intended for that; use outside the specification is not an unforeseen event but a ground for exclusion in the policy.
Overloading the platform, stepping out of the basket at height or material shifting on the guard rail are familiar causes of falls and tipping incidents. If your own employee is injured in the process, the duty of care in Article 7:658 of the Dutch Civil Code applies and employer's liability cover comes into play. An expired periodic inspection can in itself also be a reason to refuse payment.
This is what people ask us most.
That is damage to someone else's building and falls under liability, not under own-damage cover. The assessment turns on whether you asked for the permitted floor loading and whether you used load-spreading plates. If you can show that the building manager stated the loading in writing and that you stayed within it, your position in the discussion is considerably stronger.
The water damage that follows is damage to third-party property and belongs in the liability section. The amount can run up considerably because the contents and stock of several tenants may go with it. So set your sum insured to match the buildings in which you work. Check what is hanging above the platform before you go up and limit the lifting height.
Only if the machine is built for it. Standard versions have small wheels, a low permitted gradient and a limited wind class. If the machine tips over outside that specification, that is not an unforeseen event but use contrary to the usage limits, and that is an exclusion. For outdoor work choose a rough-terrain version and check the stated wind class.
The insurer can then refuse to pay, even where the cause of the loss has nothing to do with the inspection. A valid periodic inspection is included as a policy condition. That affects both damage to the machine and third-party claims. Keep the inspection log with the machine and put the expiry date in the same diary as your other inspection obligations.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.