

Liability insurance for a self-employed plumber
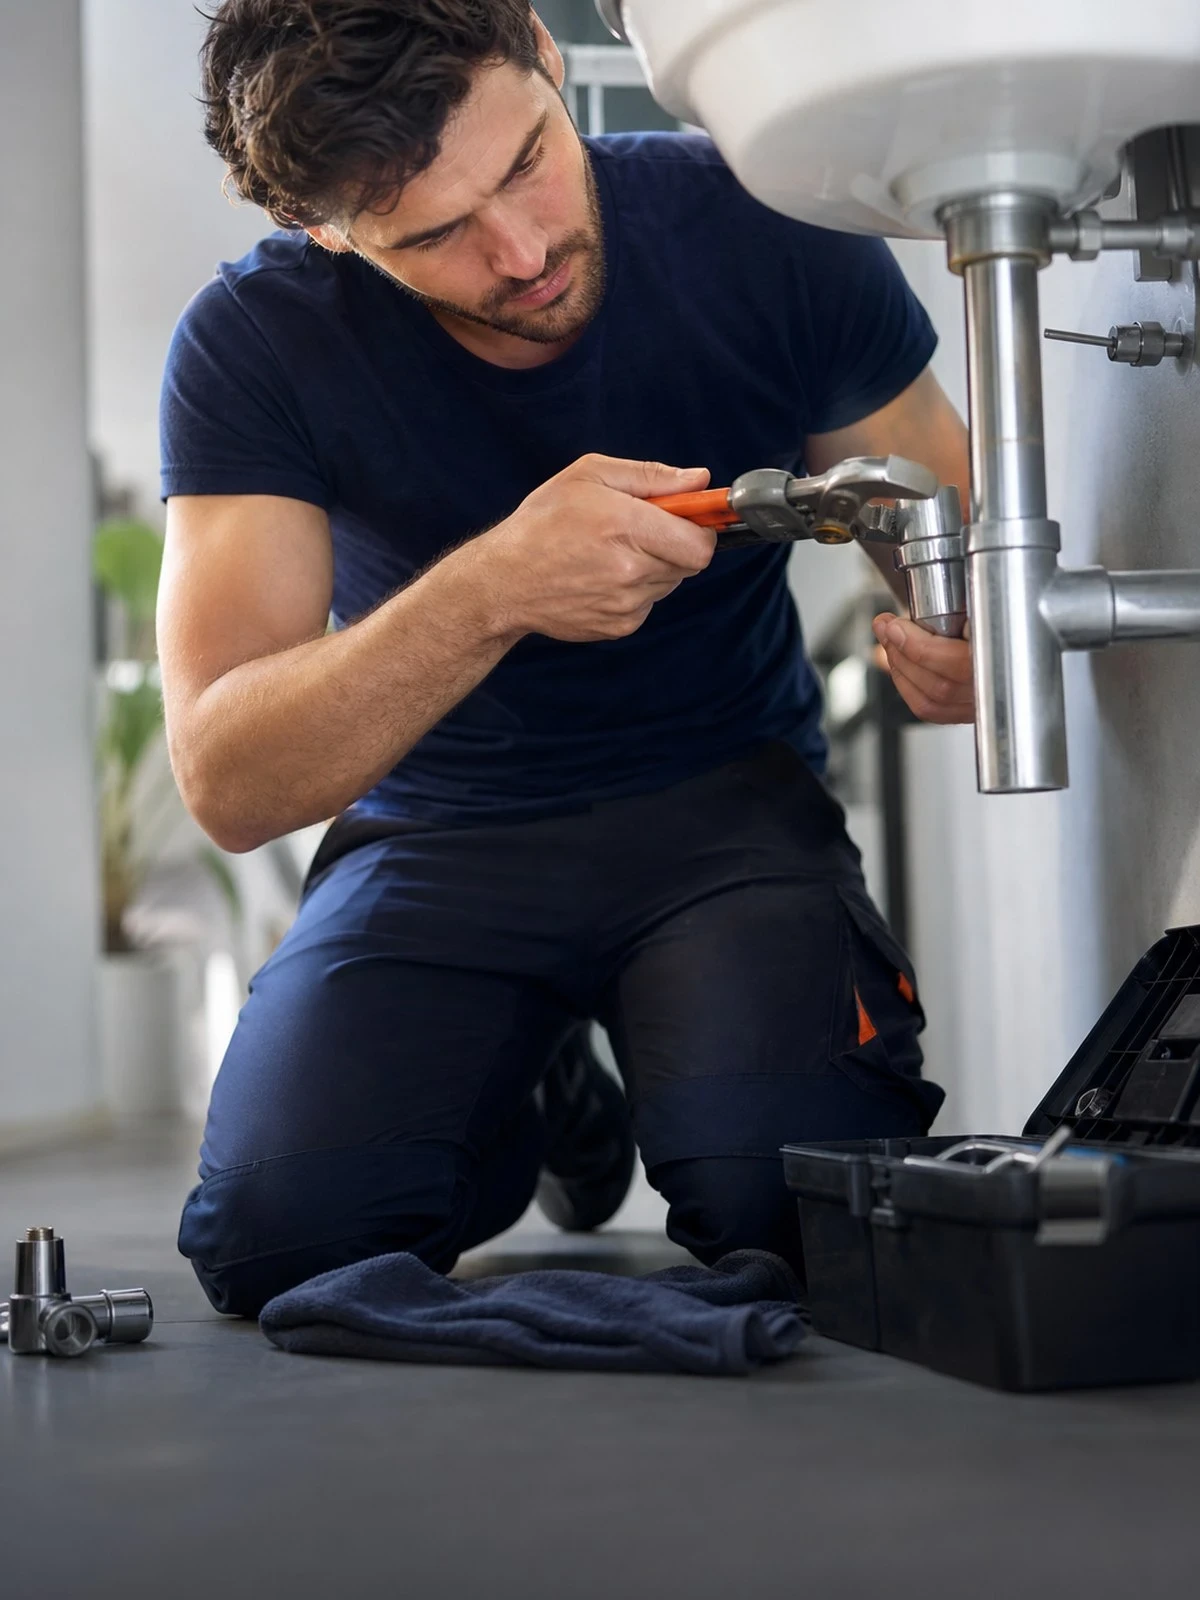
With plumbing work the loss is almost never in the coupling that leaks, but in the floor, the ceiling and the contents below it. The policy treats those two very differently.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
Start with the distinction every claims handler makes. The your own work - the coupling, the pipe, the connection you made - is excluded under the provision on work carried out. The consequential loss that results from it is not: a soaked plasterboard wall, a warped parquet floor, a kitchen unit and the contents of the neighbour below are damage to other property and belong on the AVB. In a block of flats you often have three injured parties at once: the client, the neighbours and the VvE.
The second provision that counts is care, custody and control. If you work in a bathroom or meter cupboard, you have that part of the home in your care. Insurers usually limit the exclusion to the items you are actually working on: the tap replaced or the pipe itself stays out, the rest of the home does not. Ask how your policy draws that line, because a wide care, custody and control provision leaves little of the water damage claim.
Two other risks deserve attention of their own. Brazing with a naked flame in a crawl space, duct or timber floor structure is the most common cause of fire in installation work; insurers set a clause for it with screening and a follow-up check. And with alterations to a pipe system in a care institution, hotel or sports facility, legionellacomes into play: an infection that leads to injury can be laid at your door years later.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Where the water damage claim is decided
Four points that determine the outcome of a leak claim.
Your work against the rest of the house
An insurer splits the loss into putting your own installation right and the damage around it. You pay for the first, the second is insured. Expect the loss adjuster to look at the pipework: a pressure test not checked or a missing test record moves the conversation from cover to fault.
Overnight leaks and timely notification
Water damage is often only discovered days later, so that its extent increases. Report as soon as you know: Article 7:941 of the Dutch Civil Code requires notification as soon as you are reasonably aware of it, and requires you to limit the loss. Costs to prevent worse, such as drying and extraction, often fall under the duty to mitigate the loss.
Working with fire in a timber floor
Soldering beside joists, reed or insulation calls for screening, extinguishing equipment within reach and a check afterwards. If the clause is not complied with, the fire is not covered. Where possible consider press or compression fittings; that is not only safer but also limits the insurer's underwriting questions.
What the client loses
If a cafe cannot open for two days after a leak, that loss of turnover is consequential on property damage and can be included. If there is only delay with no damage, because you arrive late for instance, that is pure financial loss and excluded.
What does your premium depend on?
- Turnover or days worked: the usual basis for a sole trader
- Share of service and breakdown work: work in occupied homes weighs differently
- Work on gas installations: this requires demonstrable certification
- Jointing technique: a naked flame increases the fire risk
- Type of buildings: flats bring more injured parties per loss
- Sum insured and excess: per claim and per insurance year
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| A visitor to a sports club bar contracts legionella after your alteration to the pipe network | Provided that | No |
| While hanging a radiator you drill through an underfloor heating hose | Yes | No |
| A client suffers burns because the thermostatic valve you set delivers water that is too hot | Yes | No |
| The decorator who follows you slips on water left standing on the hall floor | Yes | No |
| The boiler you disconnected and put in the utility room falls over and is damaged | No | No |
| Your advice to leave the existing riser in place turns out to be wrong and the home has to be stripped after all | No | Yes |
With water damage the loss adjuster always separates your own pipework from the damage around it first.
Frequently asked questions
This is what people ask us most.
Is the floor destroyed by my leak covered?
In principle yes. The floor is a different item from the pipe you installed, and that property damage is exactly what public and employers' liability insurance is intended for. Replacing the failed coupling itself stays at your expense. Note the scope of the care, custody and control provision in your policy: it can partly exclude the room you were working in.
What happens if my client's neighbours suffer damage?
They hold you liable under Article 6:162 of the Dutch Civil Code. Their relationship with your client is irrelevant. Their contents or buildings insurer then recovers the amount paid from you. That is an ordinary liability claim and insured, provided you report in good time and the loss does not fall under work carried out or care, custody and control.
Am I still liable if the leak only appears after two years?
You may be. What matters is whether the defect can be attributed to your work, not how much time has passed. For cover, what counts is whether your policy is based on the moment of the act or on the claim. If you stop the insurance, arrange run-off, otherwise you carry claims about old work yourself.
Does the policy cover fines or penalty payments?
No. Administrative fines and penalty payments are excluded on liability policies, because they are a punishment and not compensation. Damage caused intentionally stays outside cover as well; Article 7:952 of the Dutch Civil Code provides for that expressly. So what a regulator imposes on you, you bear yourself.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a central heating firmCombustion gases, certification, hot work
- Liability insurance for a self-employed central heating engineerAuthority in your name, water damage, subcontracting
- Liability insurance for a self-employed installation engineerWater damage, combustion, certification
- Liability insurance for an air conditioning firmRefrigerant, condensate drainage, certification
- Liability insurance for a self-employed rooferOpen roof, torch, care, custody and control
- Liability insurance for a self-employed carpenterPipes in the wall, finished floors, measuring
- Liability insurance for a self-employed welderWorking alone, follow-up checks, the workpiece
- Liability insurance for a self-employed painter and decoratorOverspray, burning off, care, custody and control