

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
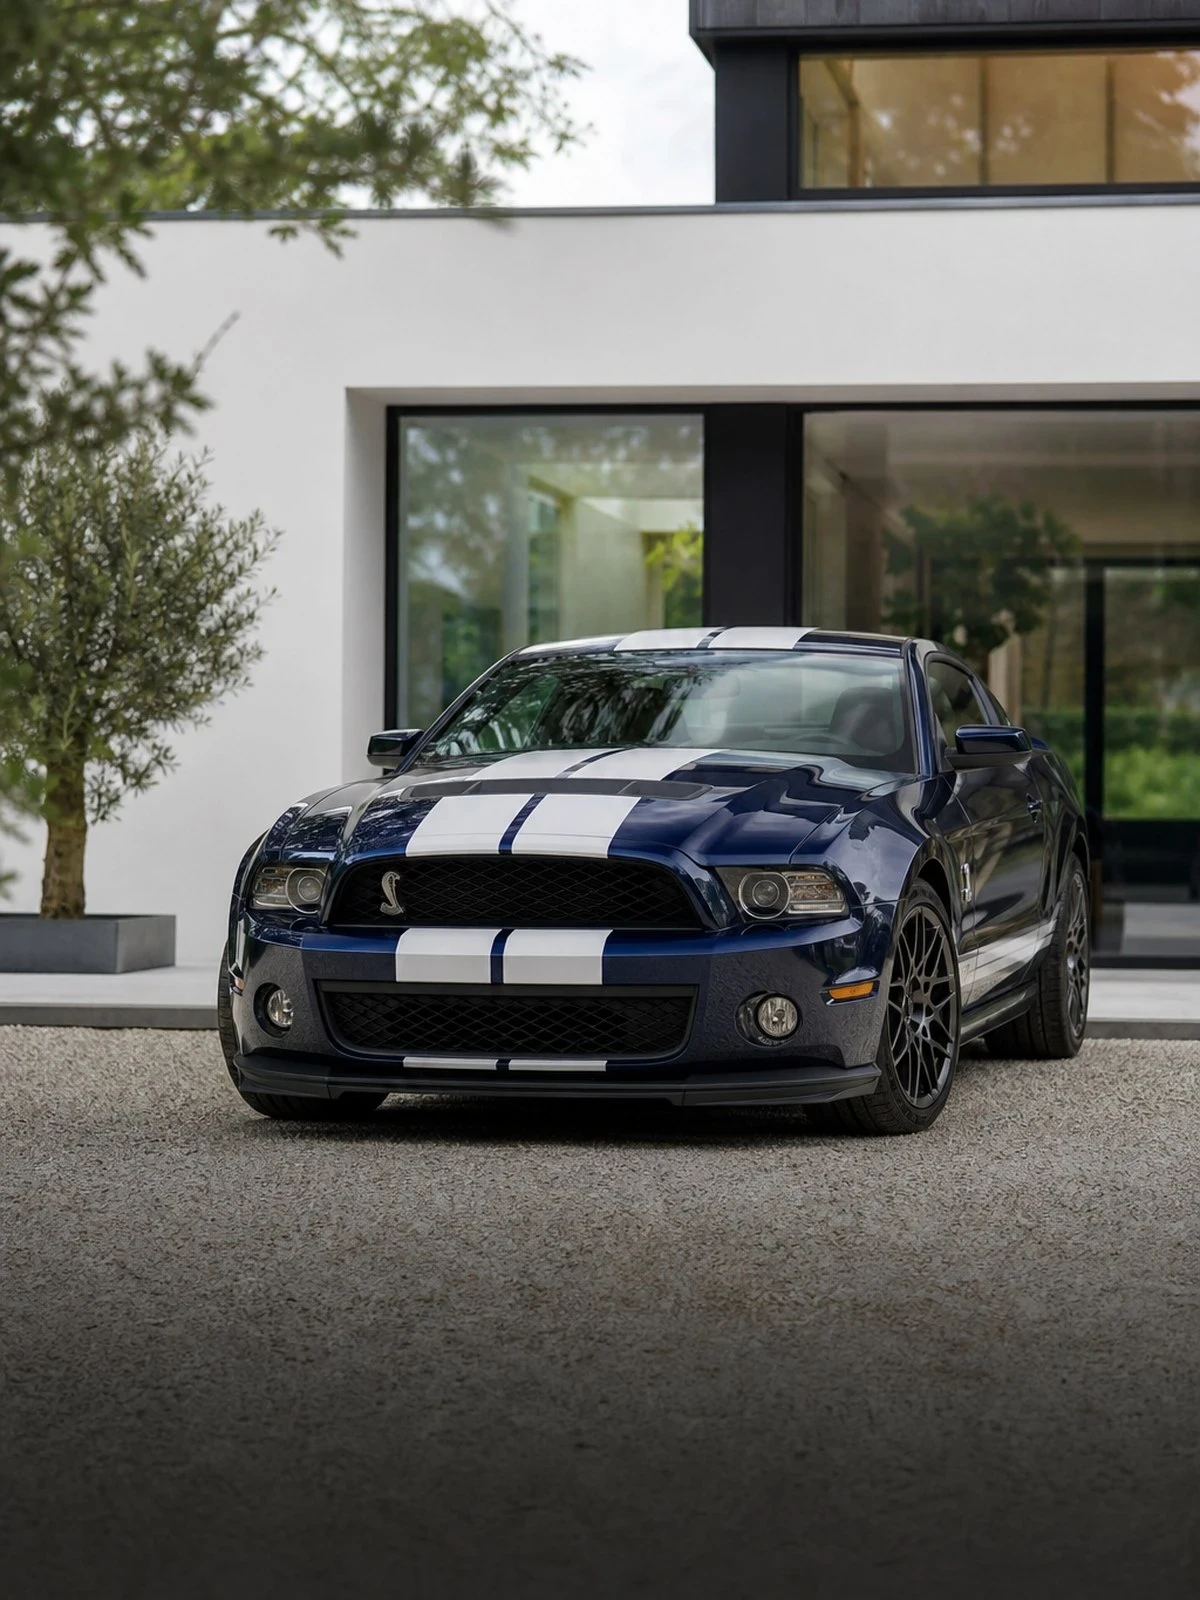
With a Shelby the first question is not which cover you want, but exactly what the registration certificate says: original, modified by Shelby, or a replica.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Very different cars fall under this name: original examples from the 1960s, modern Ford Mustangs converted by Shelby American, and replicas of the Cobra registered as self-builds or kit cars. For an insurer those are three separate risks with a value question of their own. So start with the paperwork: the registration certificate, the registration after import, the year of manufacture the RDW applies and the documentation showing what the car really is.
With imports from the United States, the admission route comes on top of that. The car has been inspected and registered, but variations such as lighting, the odometer or modified parts can come up again when there is a claim. Keep the inspection report and the import documents with the policy. Parts often come from the United States, which lengthens the repair time; your own-damage cover pays for the repair and not for the time you are without the car.
If it is an original or a well-documented example, a valuation report is the starting point. A fixed value under Article 7:960 of the Dutch Civil Code prevents a calculation after a claim from being made on a market value drawn from a market that hardly exists here. On older examples there is also a classic car or enthusiast's arrangement to consider, with conditions of use of its own.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
An original example is valued on its history and documentation, a modern Mustang modified by Shelby on the standard car plus the documented modifications, and a replica on the quality of the build and the technology used. All three lead to a different policy. State precisely on the application which of the three it is and support that with photographs, invoices and, where available, a registration number. An unclear declaration is the main source of argument here.
Superchargers, different camshafts, modified intakes and exhaust systems are common on these cars and cannot always be traced in the vehicle register. For the insurer it is the actual specification that counts. If the car is on the policy as standard while the power has been increased considerably, the risk differs from what was accepted. Have the modifications recorded with an invoice; they also help determine the valuation figure.
On classic examples the fuel system and the wiring are the most common cause of damage in storage. Fire is covered under third-party, fire and theft, but not where it results from poor maintenance that you knew or ought to have known about. Have lines, hoses and wiring checked periodically and keep the job sheets. Disconnect the battery during long periods of standing and check whether your storage is included in the policy as a condition.
Outside the cover are: sprint, drag and handling competitions and any use on a circuit; hire and driving wedding or experience trips for payment; mechanical failure, wear and engine damage without a collision; damage arising during work on the car by you or by a firm that is not approved; and damage or theft while the car was outside the storage declared, or during use that an enthusiast's arrangement excludes.
This is what people ask us most.
Yes, but on a different basis from an original. The insurer looks at the builder, the technology used, the quality of the finish and the way the car came to be registered. A valuation is virtually always needed here, because there is no list price or market value. Provide the build file, invoices and photographs with the application.
Yes. The actual specification determines the risk, even where the modification does not appear in the vehicle register. If you do not declare it, the declaration is incorrect and the insurer can reduce the payment or end the policy. An added advantage of declaring it is that the modifications can count in the valuation figure, instead of being ignored when there is a claim.
Only once the car has been inspected and holds a Dutch registration. From that moment the duty to insure under Article 2 of the WAM applies. For the period before that, such as transport from the port or a journey to the inspection, separate solutions are needed. Keep the import documents and the inspection report; they are regularly asked for when there is a claim.
Not on an ordinary private policy. Hire and carrying passengers for payment are excluded as standard, even where it is a single trip a year and the payment is limited to expenses. If you want to do this regularly, a business policy is needed in which this use is expressly included.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.