

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
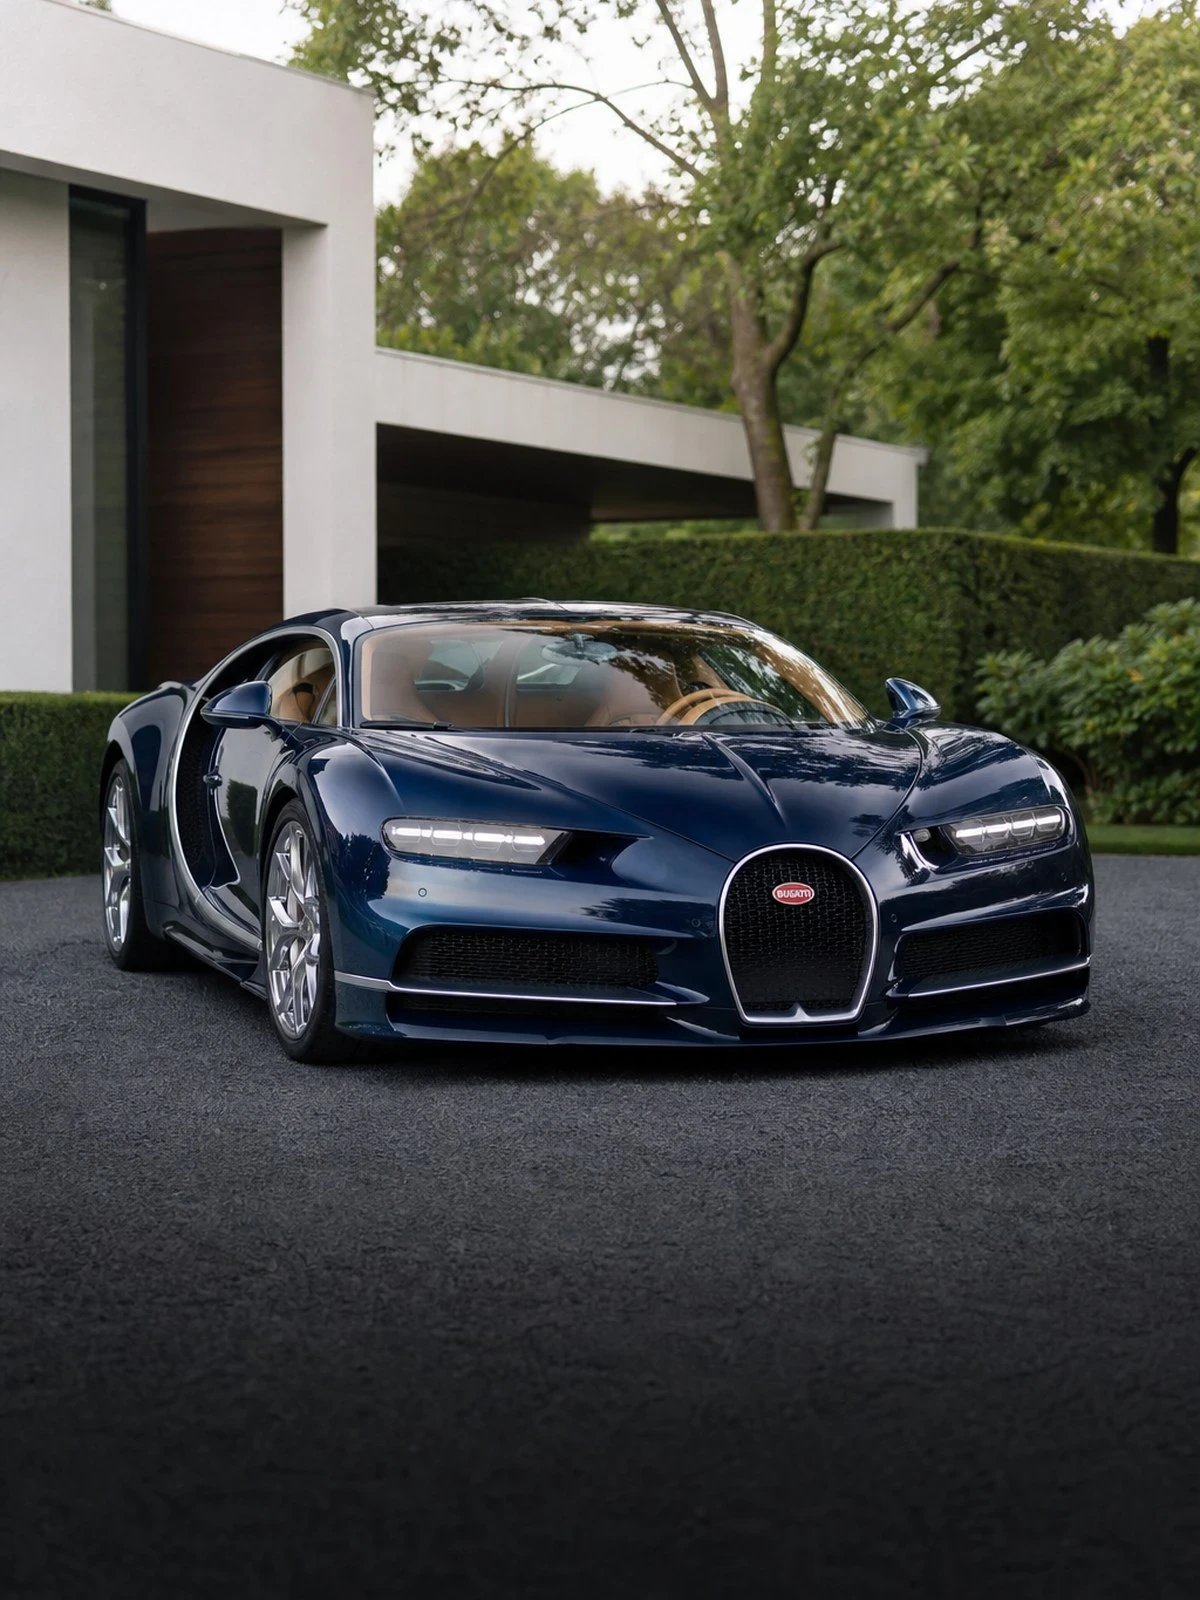
A Bugatti cannot be insured through the ordinary market: here it is a matter of an agreed value, a specialist insurer and firm arrangements about storage and use.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The difficulty with a Bugatti is not that the car is worth a great deal, but that there is no market from which to read that value. Standard own-damage cover works from market value and depreciation tables built on models of which tens of thousands are on the road. With a production run in the hundreds, such a table says nothing. That is why a policy here always works with a value agreed in advance from a valuation report, so that the question of value is no longer a point of argument after a loss; Article 7:960 of the Dutch Civil Code makes that agreement binding.
The second particular feature is repair. Servicing and accident repair are done at a limited number of designated points, often abroad. That means a loss is not only about repair costs but also about transport, waiting for parts and the period the car stands idle. Have it recorded who arranges the transport, who bears the risk during that transport and whether carriage in an enclosed trailer is compulsory.
Acceptance here turns mainly on use and storage: how many kilometres a year, in what space the car is kept, what fire and burglary protection is present there and who may drive it. Those declarations are not a formality but the heart of the policy. If the reality differs from them, the insurer can reduce the payout under Article 7:930 of the Dutch Civil Code. Arranged along similar lines is the Pagani.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A valuation report from a recognised assessor fixes the value, but not for ever. Most policies apply a period of validity, after which revaluation is needed. If that period expires without action, you fall back on market value when you claim, precisely the basis that is unusable on this type of car. Put the expiry date of the report in your diary and have the revaluation done before the period runs out.
Insurers accept these cars on the basis of a described place of storage: a locked space, a stated alarm or detection level and sometimes requirements as to fire separation where several cars stand together. If the car is temporarily kept elsewhere, for example at a specialist or during an event, report that in advance. Theft or fire at a location that has not been declared is one of the few situations in which an otherwise covered event is nonetheless not paid for.
A Bugatti more often goes to a destination on a trailer than under its own power. During that carriage your car policy is usually not the cover that applies. The risk lies with the carrier or with separate transport cover. Check the carrier's limit of liability, because it is usually far lower than the value of your car. For events, also ask about the cover on the site itself.
The following remain outside the cover: taking part in speed trials, top speed events, track days and skill events, even where these are organised by the manufacturer or a marque club; mechanical failure, wear and engine damage without a collision; damage during transport by a third party; a fall in value after a proper repair unless expressly insured; and damage or theft outside the agreed area of cover or away from the declared place of storage.
This is what people ask us most.
As a rule no. The usual acceptance systems do not know this segment and work with market value and list price. For these cars the work is done through specialist insurers or underwriting agents who work from a valuation and assess the risk individually. That also means the application takes longer: the car, the storage and the driver are all looked at.
That is stated in your policy and follows the period of validity of the report. Once that period expires, the agreed value lapses and the insurer assesses the loss on market value after all. On a car whose value moves, revaluing in good time matters more than on an ordinary car, because the difference between the two bases can be very large here.
Not under the ordinary policy. Circuit use, speed trials and top speed events are excluded as standard. Separate day cover exists for events, but it has to be arranged in advance and is assessed case by case. Not every insurer offers it for this segment. If you drive without that cover, you bear the full own-damage loss yourself.
Usually the carrier, and that liability is limited to an amount per kilogram or per consignment. That falls far short of the value of this car. So have it arranged in advance that the transport falls under your own policy or under separate transport cover, and have it recorded that carriage is in an enclosed trailer.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.