

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
On a Ligier the policy turns on value: which basis applies in the event of a total loss, and how quickly that basis shifts in the years after delivery.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A new Ligier represents an amount that many buyers underestimate, and that value falls fastest in the first years. That is exactly where the choice of cover comes down. Does your policy calculate a total loss on the replacement value as new, on a depreciation scheme or on the market value at the time of the loss? You only notice that difference at the moment the vehicle can no longer be repaired.
Insurance never pays more than the loss actually suffered. That principle is set out in Article 7:960 of the Dutch Civil Code. A depreciation scheme does not change that, but it records in advance which value the parties take as their starting point. Such a scheme runs for a limited period, often applies only to the first owner and lapses on sale. Ask for the period and the source of value used before you sign.
If you buy second-hand, the market value is the basis and the condition of the vehicle counts heavily. How the levels of cover differ from one another is set out at the page on light quadricycle insurance. If you drive an electric version, read on at the electric light quadricycle (brommobiel).
We compare your moped insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
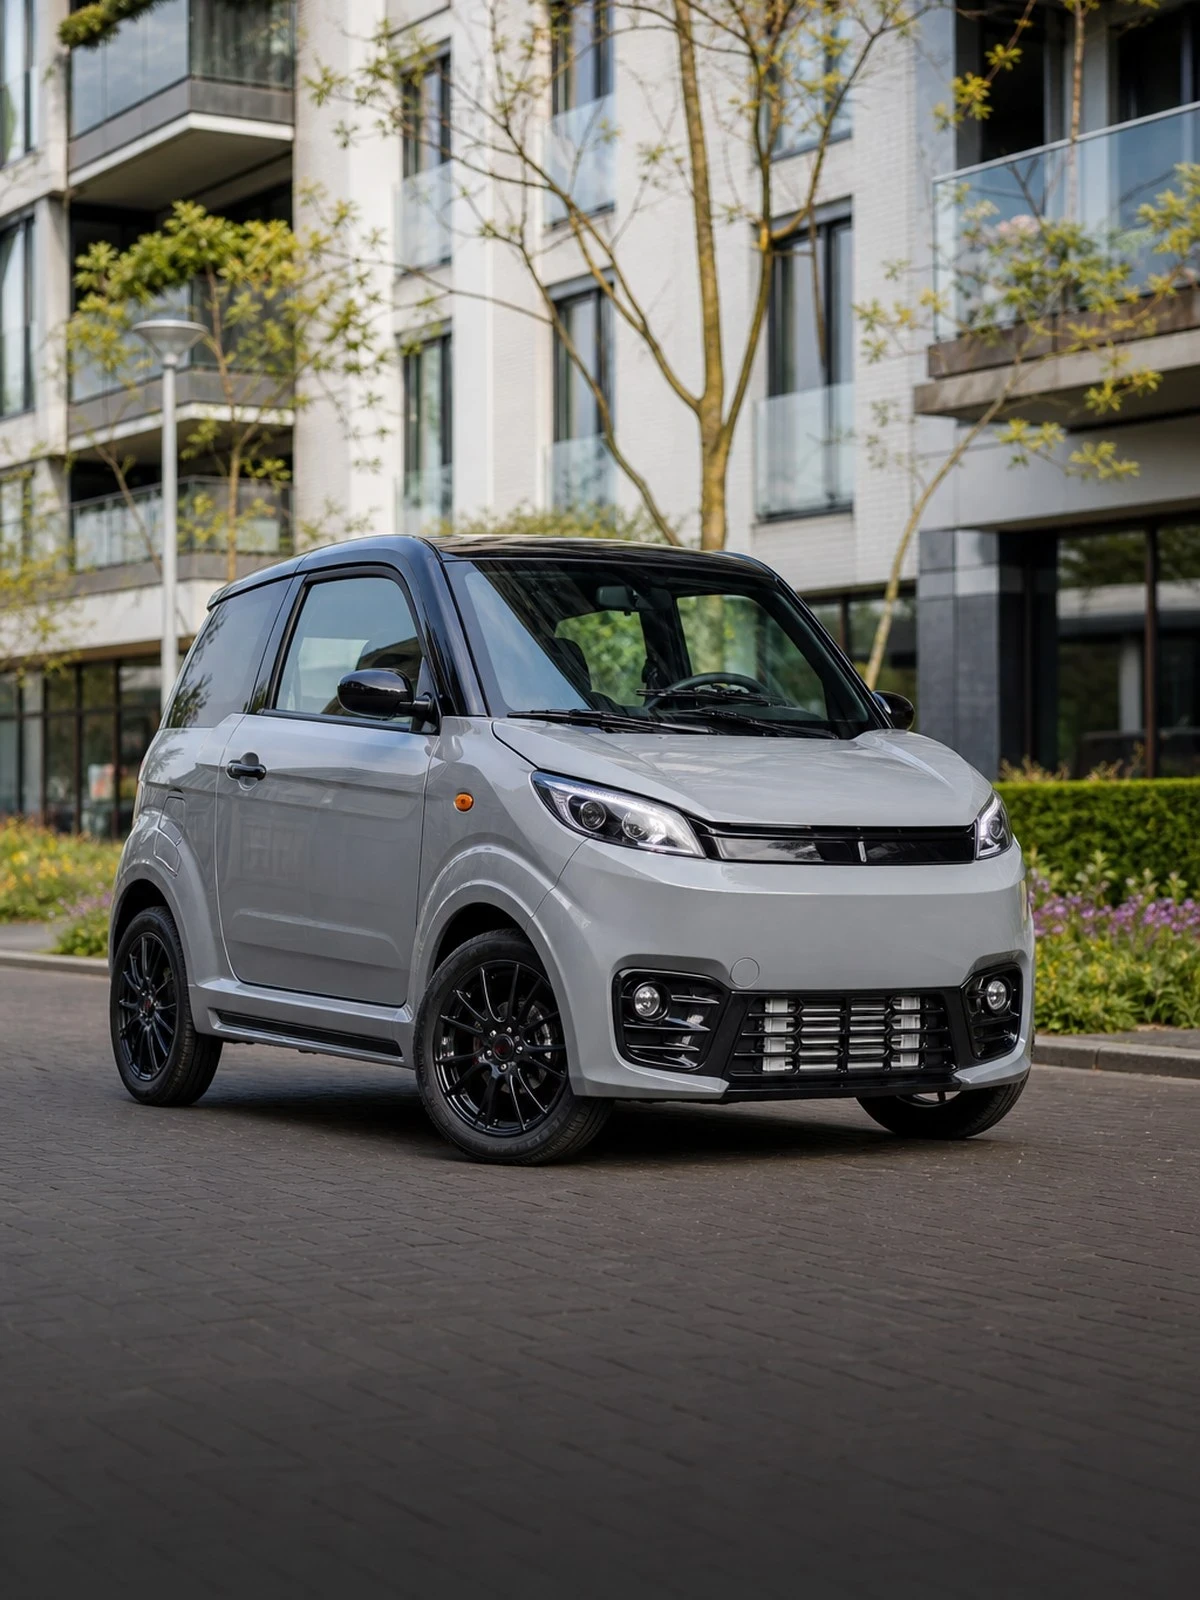 Moped insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Three bases determine what you receive in the event of a total loss. The replacement-value-as-new scheme takes the price on delivery as its starting point and applies for a defined period. After that comes a depreciation scheme that lowers the value step by step. Once that expires too, the market value remains: what a comparable example costs at that moment. Ask which of the three is in your policy and when the next one takes effect.
On a used example the insurer determines the value after the event, at the time of the loss. That leads to argument where you have paid more than the market indicates. Keep the purchase invoice, photographs of the condition and the service history. On a special version or one with many options you can have an agreed valuation included in advance. If so, record the period of validity of that report in writing as well.
In this vehicle category, repairs run through a limited network of dealers and the supply of parts takes longer than for a car. Damage that looks modest in money terms can therefore keep the vehicle off the road for weeks. Plastic body panels are also replaced rather than beaten out, so repair costs exceed the market value more quickly and the insurer moves to a total loss.
Outside the cover are: loss of value remaining after a proper repair; wear to the drive belt, clutch and brakes and the consequences of postponed maintenance; mechanical or electrical faults without an external cause; damage while hired out or used for lessons without this being declared; an altered or derestricted construction; and damage through intent or wilful recklessness, see Article 7:952 of the Dutch Civil Code.
This is what people ask us most.
That differs from insurer to insurer and is set out in the policy conditions. The scheme always runs for a defined period after the first delivery date and in most cases applies only for as long as you are the first owner. If you sell the vehicle, the scheme lapses for the buyer. Ask for the exact period and the basis that follows before you sign the policy.
Because the repair costs are set against the market value. Plastic body panels are replaced rather than repaired and the labour time runs up because of the limited stock of parts. On an older example with a low market value that threshold is reached quickly, even where the damage looks limited to the eye. You then receive the market value less the residual value and the excess.
At the registration and the cover taking effect on the same day, so that no uninsured moment arises. Also have it checked that the design speed is original. A vehicle derestricted earlier gives rise to an exclusion after a loss that you run into as the new owner. Keep the purchase invoice and the service history as support for the value.
On a special version, one with many options or a used example with an unusual value, that is sensible. An agreed valuation records the value in advance, so that no argument arises about it after a loss. Note the period of validity of the report: once that has passed, you fall back on the market value the loss adjuster establishes at the time of the loss.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.