

Liability
- Cables and pipes
- Damage to buildings and road surfaces
- Injury to bystanders
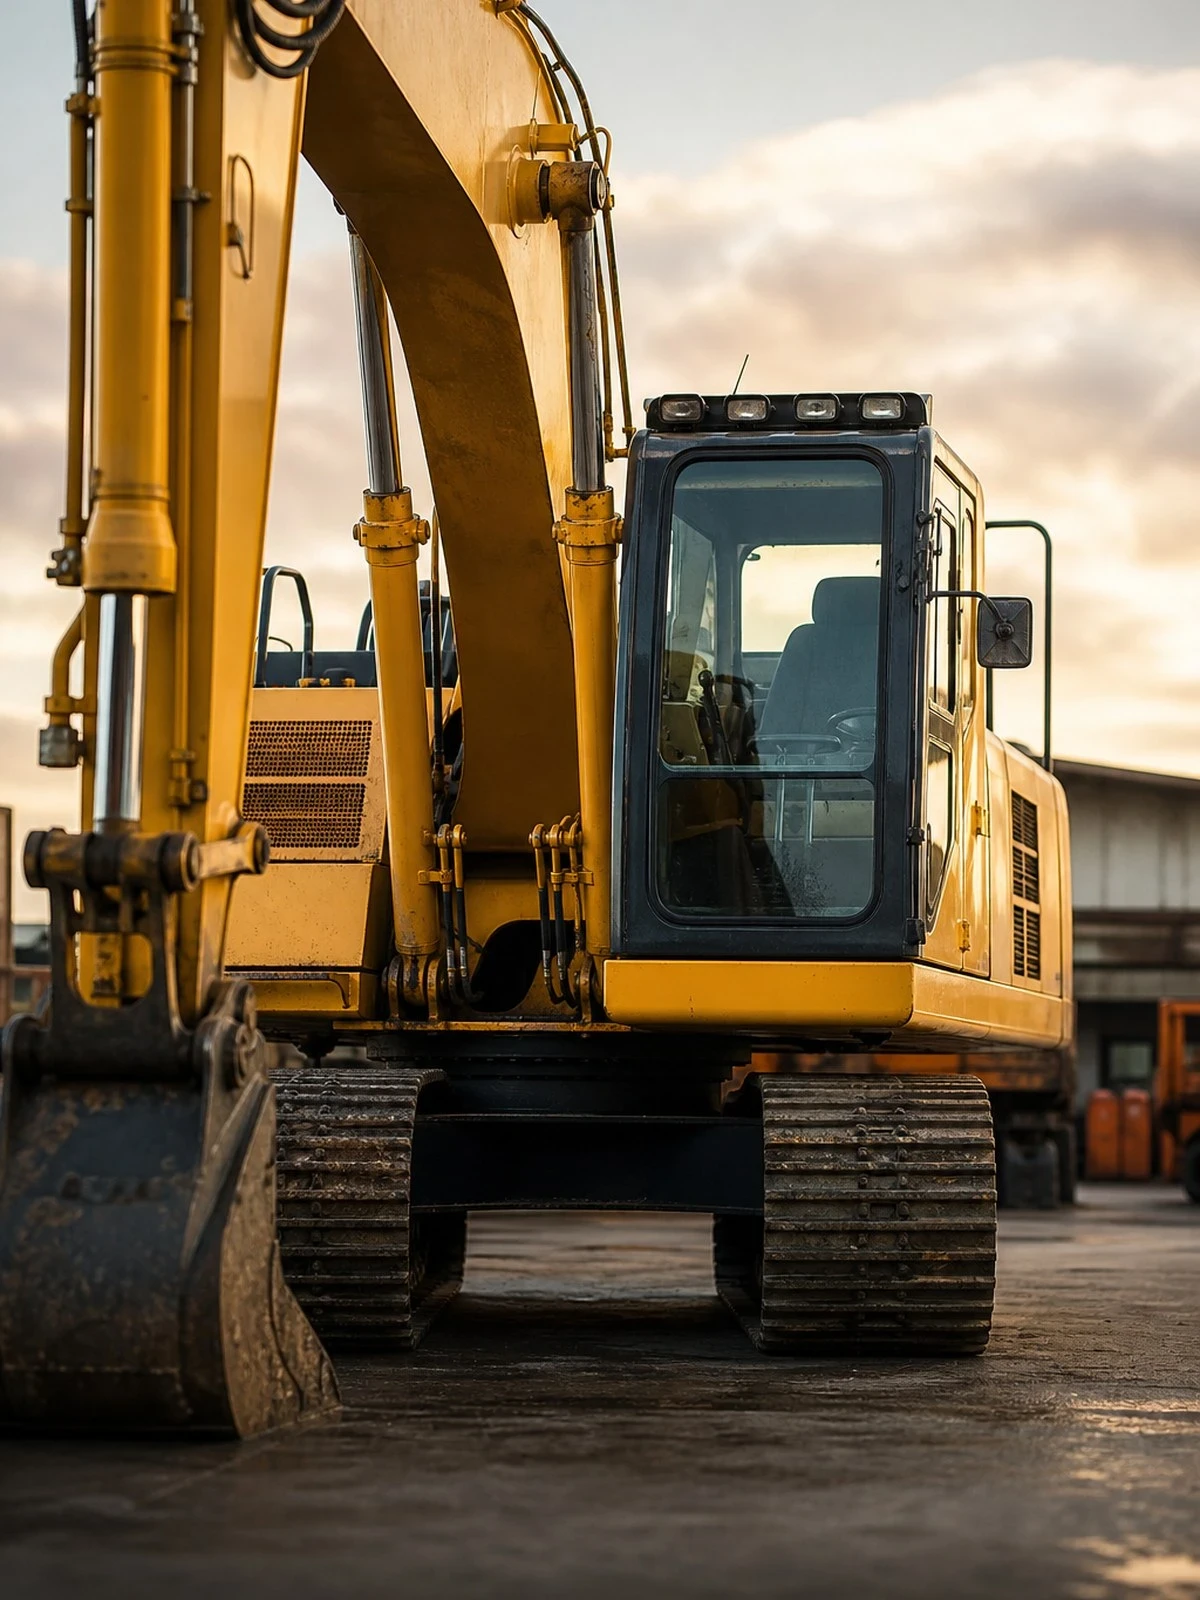
Komatsu excavators, bulldozers and dumpers work on large infrastructure projects with costly 3D machine control; the GPS equipment and the project conditions determine how the policy should be set up.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
In the Netherlands, Komatsu supplies a broad range of earthmoving equipment: crawler excavators in the PC series such as the PC210 and PC290, wheeled excavators in the PW series, wheel loaders, bulldozers and articulated dump trucks. A notable feature is the intelligent machine control Komatsu fits at the factory on models including the PC210LCi and the D61PXi, with GNSS receivers, a display and software that automatically keeps the bucket or blade at design height. As an indication, a PC210 costs € 200,000 to € 270,000; the control equipment can easily account for € 30,000 to € 60,000 of that.
That equipment is the first pitfall. Separate receivers, antennas and displays from Topcon, Trimble or Leica mounted on the machine are sought after by thieves and are unscrewed from the cab after working hours. Under an own-damage policy they are only covered if they have been declared with make, type and value, and often on condition that they are removed from the machine at night or that the machine is parked on a locked site.
The second pitfall is the project. Komatsu equipment is often used on tendered infrastructure works with a construction all risks (CAR) policy taken out by the client or main contractor. That policy covers the works, not your machine and not your liability. We arrange a plant and machinery policy in which the control equipment, subcontracted work and transport between projects are explicitly covered, and compare several insurers for this.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
Cover for Komatsu equipment depends on the value including machine control, the type of projects, the main contractor's contract conditions and transport between sites.
Damage to cables, pipes, roads, buildings and people that you cause with the Komatsu on an infrastructure project; compulsory once the machine goes on the road.
Damage to and theft of the machine, including the declared 3D control equipment and attachments.
Hire costs of replacement equipment during downtime after damage, and cover during transport on a low loader between projects.
What is covered
| Situation | Covered |
|---|---|
| Theft from the building site | Sometimes |
| Fire and storm damage | Yes |
| Inherent defect in the hydraulics | Sometimes |
| Damage to cables and pipes | Sometimes |
| Normal wear and tracks | No |
| Damage due to deferred maintenance | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Six situations from deploying Komatsu equipment on infrastructure projects.
The GNSS receivers, the antennas on the boom and the display in the cab of a Komatsu with intelligent machine control are stolen to order; a complete set changes hands on the black market for thousands of euros. Insurers only cover this equipment if it is listed as a separate item on the policy, and often require loose components to be removed from the machine outside working hours or the machine to be parked on a locked and lit site. Factory-integrated control is usually included in the machine value, provided that value takes it into account. For each machine we record which equipment is fitted and how it is secured.
On a dyke reinforcement or road widening, the client or main contractor takes out CAR insurance. Subcontractors often assume their equipment is covered by it. That is rarely the case: the 'works' section covers the construction work, and the section for construction plant and site cabins is usually limited or only applies to the main contractor. Your Komatsu, its attachments and your liability must be on your own plant and machinery policy. Moreover, main contractors' hire conditions often include a clause stating that you remain liable for damage caused by your machine. We read the project conditions with you before you start the job.
Komatsu excavators are used in dyke reinforcement and nature development on embankments, on soft peat soil and along water. Overturning, sinking or ending up in the water are the own-damage claims that count there, and recovering a 25-tonne machine from a ditch or an embankment alone costs tens of thousands of euros. Many own-damage policies cover recovery costs up to a maximum or as a percentage of the sum insured. Work on pontoons or with a long boom in water is excluded by some insurers unless included. We state the type of projects in the application and check the recovery and hydraulic engineering clauses.
On road widenings and site raising, gas, water and data cables lie just below the works. A struck high-voltage cable or fibre-optic connection leads to a liability claim that quickly runs into tens of thousands of euros. Insurers cover cable damage under the liability section, but apply a higher excess and may restrict cover if the KLIC notification is missing or the CROW 500 guideline for careful excavation was not followed. An operator digging on the basis of 3D control must also have the cable drawings. We record in your policy which excess applies to cable damage and advise on the evidence file per project.
Komatsu equipment regularly moves between projects and is then carried on a low loader, sometimes by your own tractor unit and sometimes by a haulier. Damage during loading, transport and unloading is a separate part of the plant and machinery policy: not every own-damage cover includes the transport risk, and the haulier's liability is limited to a low amount per kilo. An excavator sliding off the ramps or a boom hitting a viaduct is a major uninsured loss without transport cover. We include transport in the own-damage cover and check whether loading and unloading on site are also covered.
A Komatsu on an infrastructure project runs 1,500 to 2,500 hours a year and therefore loses current value quickly. Insurers often offer a new-for-old arrangement for the first two to three years, after which the current value at the time of the loss applies. Anyone still insuring the purchase value after four years pays too much premium; anyone setting the value too low is underinsured in a total loss. The value of the machine control must be tracked separately, because that equipment depreciates differently from the machine. We update the insured values every year based on year of manufacture, hours and used-machine prices.
Frequently asked questions about insuring Komatsu equipment.
Only if that equipment has been declared. Komatsu's factory-integrated control belongs to the machine and falls under the sum insured, provided that value includes the control system. Retrofitted systems from Topcon, Trimble or Leica with separate receivers and displays must be listed as a separate item with make, type and value on the policy. Insurers often set requirements for removing loose components outside working hours. We include the equipment for each machine.
Usually not for your machine and often only to a limited extent for your liability. The CAR policy covers the works themselves and sometimes construction plant of the insured parties, but subcontractors' own equipment generally falls outside it or is only covered up to a low amount. The project conditions also often place liability for damage caused by your machine on you. Your own plant and machinery insurance with liability and own-damage cover therefore remains necessary. We check whether the project conditions and your policy dovetail.
For machines above a certain value, often from € 50,000 to € 100,000, insurers require a track-and-trace system with a recognised certificate, an immobiliser or PIN code and storage on a locked site outside working hours. On newer machines Komatsu supplies its own Komtrax system, which transmits location and operating hours, but not every insurer recognises it as a security class. Additional requirements apply to the loose control equipment. We check in advance which class applies to your machine.
The network operator or cable owner holds you liable for the repair costs and sometimes for consequential losses of businesses left without a connection. The liability section of your plant and machinery policy covers that damage, with an excess that is often higher for cable damage than for other claims. The insurer will ask about the KLIC notification and how the digging was done; if the notification is missing or the guideline was not followed, cover may be restricted. Keep the notification and drawings for each project.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.