

Professional indemnity insurance (BAV) for an acupuncturist
In acupuncture the loss is in the patient and not in a report. A policy that covers only financial detriment leaves you uninsured for precisely your biggest risk.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
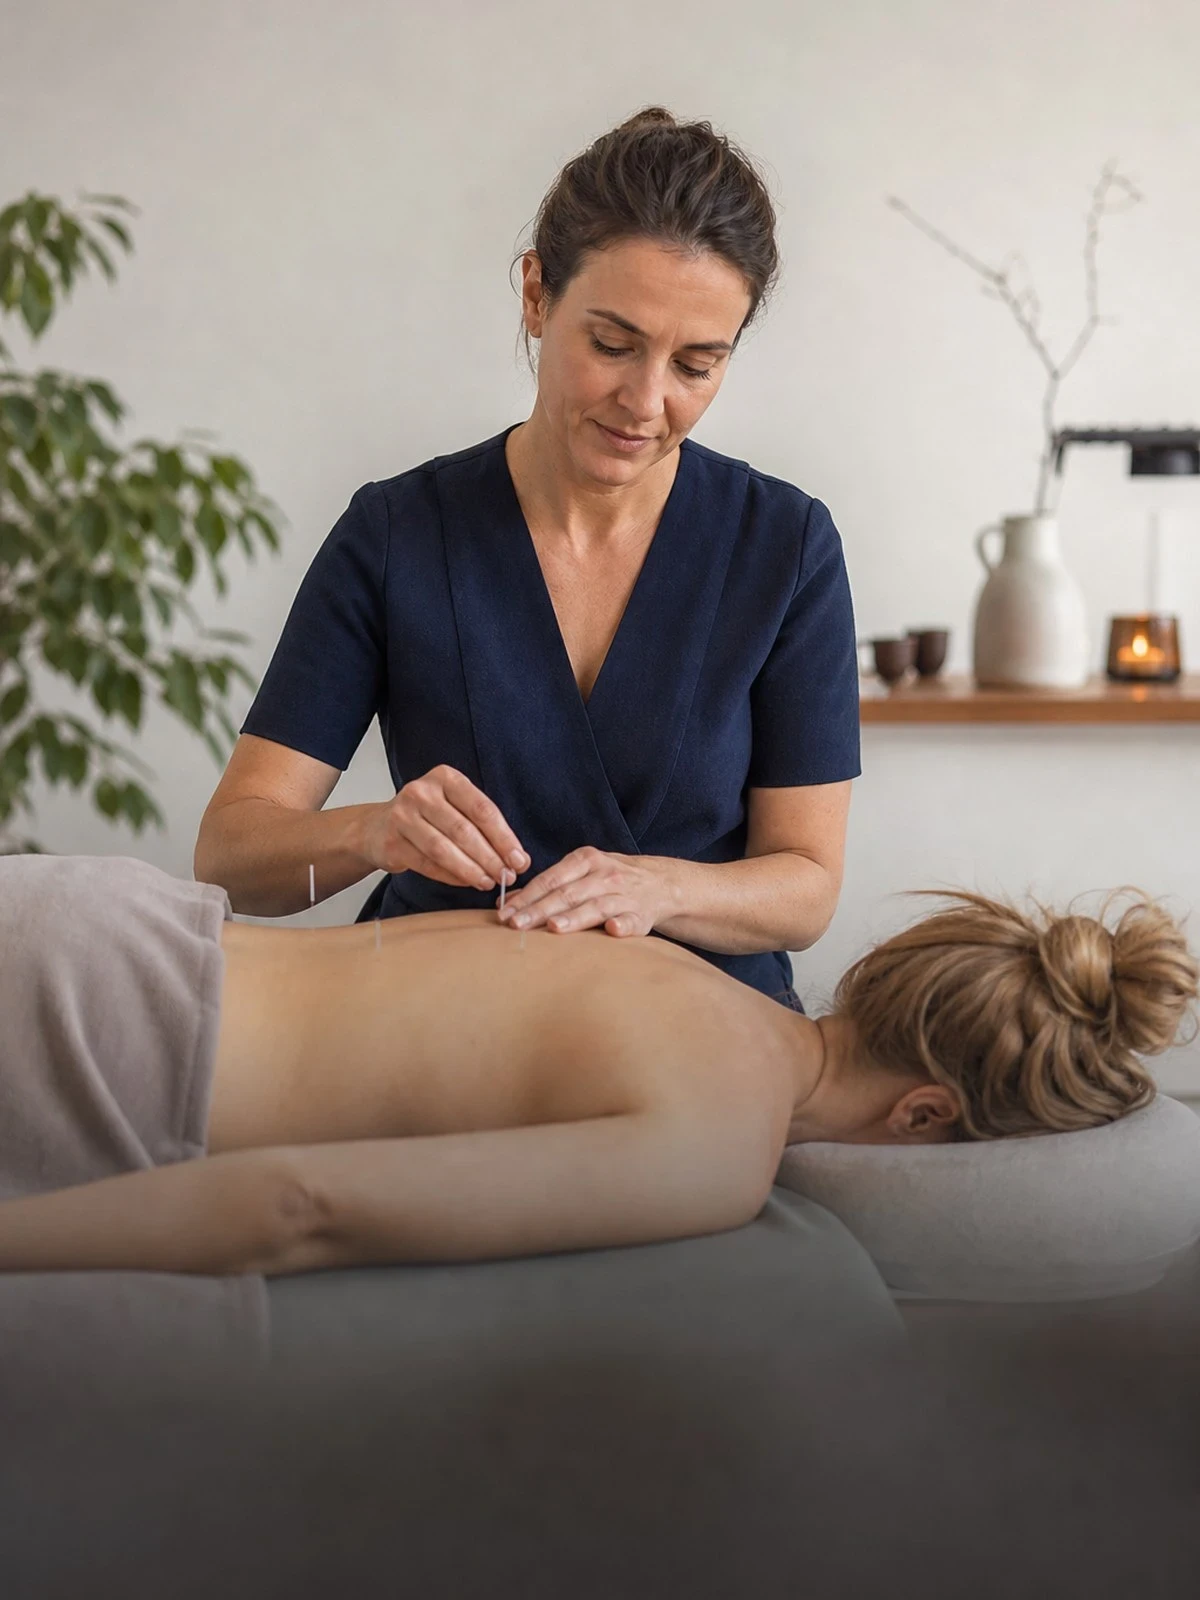
What goes wrong in acupuncture is rarely a calculation error. It is a needle at a point around the thorax or the shoulder that goes too deep and causes a pneumothorax, an infection or a substantial haematoma after a needle, a needle missed during counting, or a burn from moxibustion or cupping. That is injury to a patient caused by your own actions. For healthcare professions there is therefore a version of professional indemnity insurance that includes personal injury arising from treatment. A policy covering only pure financial loss is not suitable for you.
The standard is that of a good care provider under Article 7:453 of the Dutch Civil Code. The WGBO, Article 7:446 and following, also applies to many complementary practitioners, including the duty to inform and obtain consent under Articles 7:448 and 7:450 of the Dutch Civil Code and the duty to keep records under Article 7:454 DCC, with a retention period of twenty years. That long tail matters in insurance terms: a complaint can arrive years after the last treatment, by which time your policy may long since have ended.
Injury unconnected with the treatment belongs elsewhere. If a patient trips over a threshold in your waiting room, that is an ordinary accident on your business premises and it falls under public and employers' liability insurance. If you work with several practitioners or let out rooms, different questions apply. Those are set out on the page about the acupuncture practice.
This page deals with one situation. The full overview is on Compare professional indemnity insurance (BAV).
Independent, personal, sorted quickly
We compare your professional indemnity insurance (BAV) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Professional indemnity insurance (BAV)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four points that cause more discussion for a self-employed acupuncturist than the size of the sum insured.
Personal injury arising from treatment must be stated in so many words
Many standard forms of the BAV are written for advisers and limit the cover to pure financial loss. A collapsed lung or an infection is not financial loss but injury. Ask for the healthcare version, in which liability for personal injury caused in the course of your profession is expressly included, and do not be fobbed off with the assurance that it is covered anyway.
Contraindications and referral
Some claims are not about the needle but about what you did not do: continuing treatment when persistent symptoms point to something else, or needling a patient on anticoagulants, with a pacemaker or during pregnancy without discussing it. Record the intake, the contraindications and the advice to see the GP in the file. Without a file it is your word against the patient's.
The working methods you declare are the limit of the cover
Insurers accept you on the basis of your training, your registration and the techniques you declare. If you later add dry needling, injections, cosmetic applications or laser treatment without telling them, the insurer can rely on the duty of disclosure under Article 7:928 of the Dutch Civil Code and the consequences of this in Article 7:930 of the Dutch Civil Code. Reporting a change costs one email.
What falls outside the policy
As a rule the following are excluded: herbal preparations and supplements that you supply yourself, because that is product liability within the meaning of Article 6:185 of the Dutch Civil Code; intent and wilful recklessness under Article 7:952 of the Dutch Civil Code; fines, penalty payments and disciplinary sanctions; and the repayment of your own fee or redoing a course of treatment.
What does your premium depend on?
- Annual turnover from treatments: the usual basis for a practice at home or in commercial premises
- Techniques used: moxa, cupping and electro-acupuncture weigh more heavily than needling alone
- Training and registration: membership of a recognised professional body is a condition of acceptance with many insurers
- Treating at other locations: working at patients' homes or in a care institution changes the assessment
- Retroactive period requested: the further back your practice years run, the higher the premium
- Sum insured and excess: the amount per claim and the annual maximum together determine the premium
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| A needle at a point around the shoulder causes a collapsed lung | No | Yes |
| A patient develops an infection at a needle site after treatment | No | Yes |
| A moxa cone leaves a burn mark on a patient's back | No | Provided that |
| Your treatment couch collapses and the patient falls to the floor | Yes | No |
| Spilt massage oil ruins a patient's coat | Yes | No |
| A patient demands the fee for ten treatments back because the symptoms persisted | No | No |
Only a BAV with express cover for personal injury arising from treatment catches the left-hand column. An ordinary healthcare form does not do so automatically.
Frequently asked questions
This is what people ask us most.
I have an AVB. Is a needle incident covered by it?
Usually not. Public and employers' liability insurance covers injury you cause as a business, but it almost always excludes liability arising from the practice of the profession itself. Needling is exactly that. For that you need professional indemnity insurance that includes personal injury arising from treatment.
A patient is complaining about a treatment from four years ago. Am I insured?
That depends on the form of the policy. Under a claims made policy what counts is the moment the claim is brought and notified, not the moment of the treatment. If your policy is still running and the treatment date falls within the prior-acts cover, there is cover. Report the complaint at once; Article 7:941 of the Dutch Civil Code requires you to notify as soon as you reasonably know that a claim is coming.
Are the herbs I hand out insured?
Not on the professional indemnity insurance. As soon as you supply a preparation, it is a product and not advice. Loss caused by a contaminated or incorrectly composed remedy falls under product liability, for which you need separate cover. If you only advise on a remedy that the patient buys elsewhere, that is professional practice.
Does the policy cover a disciplinary complaint or a complaint under the Wkkgz?
Defence costs in a civil liability case are covered, but disciplinary proceedings or a referral to the disputes body often are not. As a care provider you are in any event required under the Wkkgz to have a complaints officer and a disputes body. For assistance in proceedings that fall outside the liability cover, you could consider legal expenses cover for self-employed professionals.
Every situation is different. For these situations we have a separate page.
- Compare professional indemnity insurance (BAV)The main page
- Professional indemnity insurance (BAV) for a chiropractorManipulation, informed consent, contraindications
- Professional indemnity insurance (BAV) for a chiropractic practiceInformed consent, contraindications, record keeping
- Professional indemnity insurance (BAV) for a speech therapy practiceSwallowing assessments, red flags, locums
- Professional indemnity insurance (BAV) for a dental hygiene practicePeriodontal care, anaesthesia and X-rays, spotting the signs
- Professional indemnity insurance (BAV) for a dietitianDietary advice, matching medication, product sales
- Professional indemnity insurance (BAV) for a dental hygienistActing on instructions, competence, care on location
- Professional indemnity – PhysiotherapistLocum work, manual techniques, disciplinary complaints
- Professional indemnity – DentistExtractions, endodontics, nerve damage