

Third-party liability
- Damage to other vehicles and injury
- Compulsory under Article 2 of the Dutch Motor Insurance Liability Act (WAM)
- Injury to your passenger as well
- No cover for the Rocks-e itself
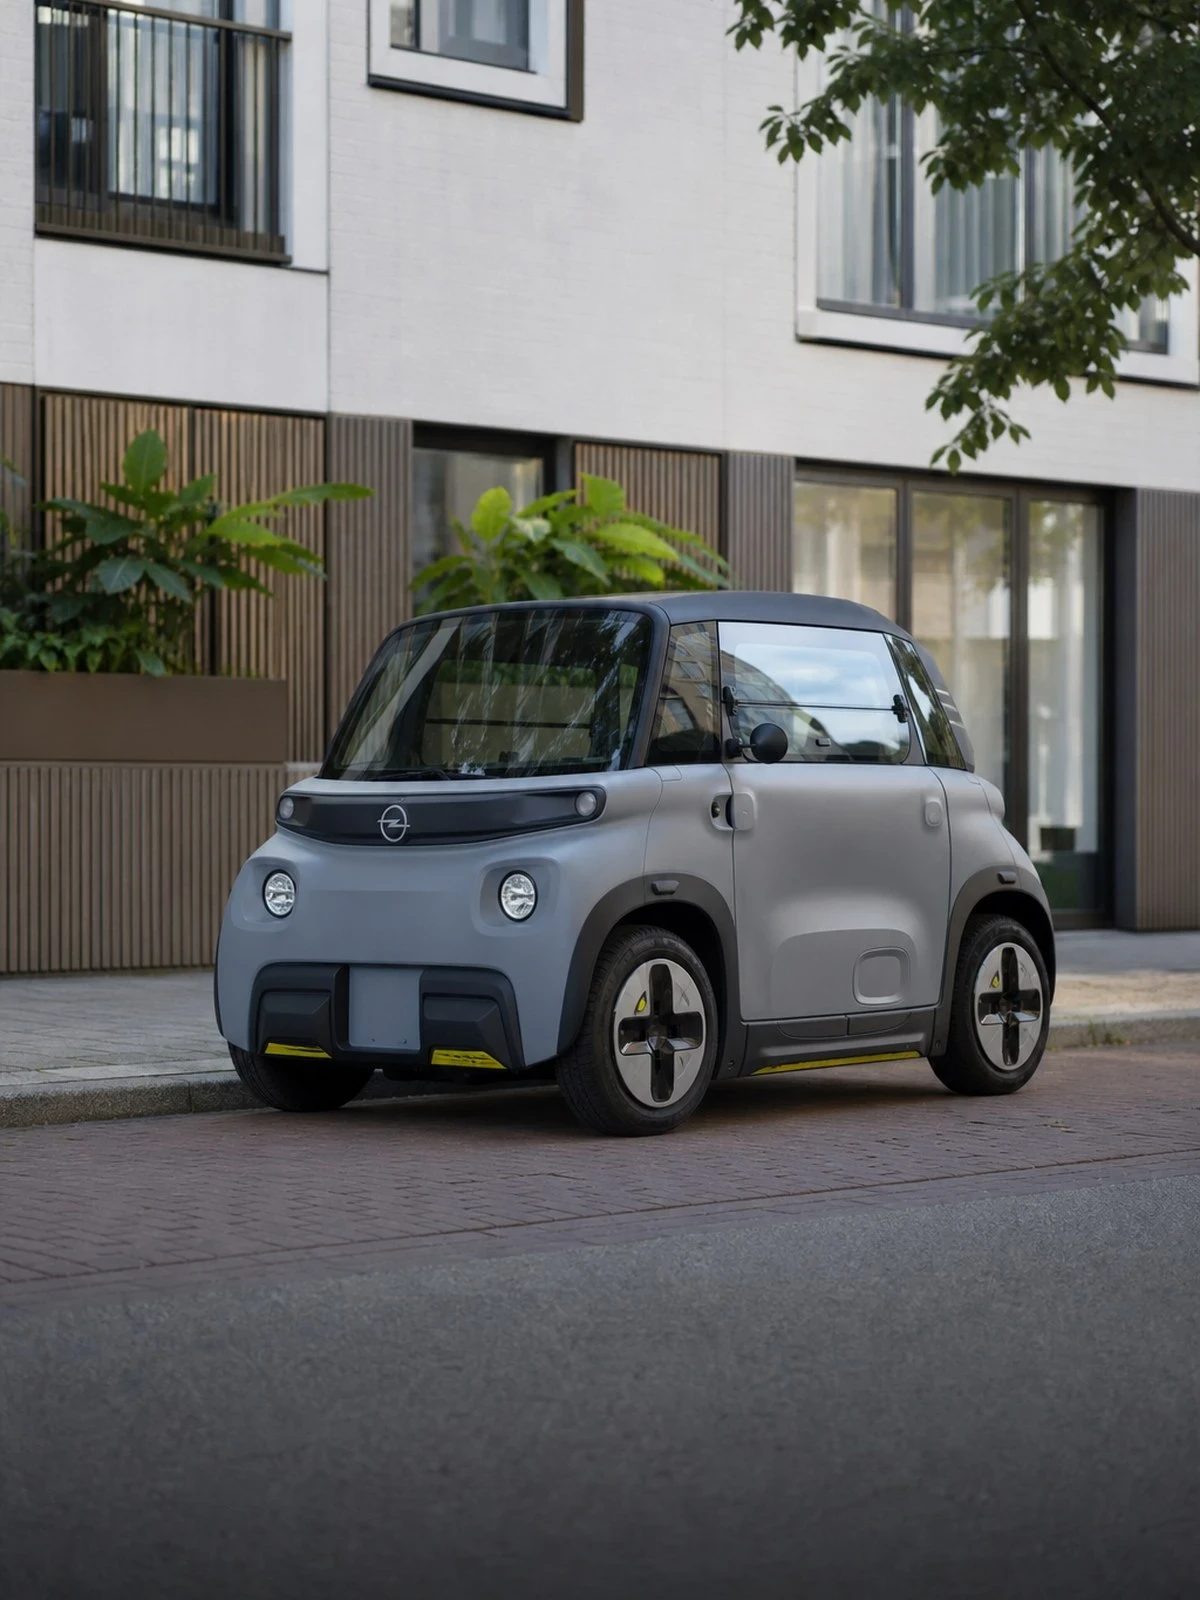
The Opel Rocks-e is an electric light quadricycle (brommobiel) with a moped registration. In law it is not a car but a moped on four wheels, and that determines the whole of the insurance.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The Rocks-e is a light quadricycle: a light, electrically driven four-wheeler with a closed body, restricted to 45 kilometres per hour and registered as a moped. It looks like a small car, but it is not insured as a passenger car. On the public road the insurance obligation of Article 2 of the Dutch Motor Insurance Liability Act (WAM)applies; for as long as the registration is in your name and is not suspended, valid third-party liability cover must be in force.
On top of third-party liability you can choose third-party, fire and theft or comprehensive cover. On a light quadricycle, own-damage cover matters more than the low top speed suggests: the body panels are plastic, there is no large stock of parts as there is for an ordinary car, and a collision that is small in itself therefore quickly leads to a high repair bill or to an economic total loss.
Two points are specific to the electric drive train. Check whether the battery is your property or is hired, and whether damage to the battery pack comes under own-damage cover. On these vehicles that question is often dealt with separately. And check what requirements apply to charging: charging with an unsuitable cable or a faulty domestic connection can lead to argument in the event of fire damage.
We compare your moped insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Moped insurance
 Compare
 Get covered
Three levels of cover, with the situations that arise most often on this vehicle set out beneath them.
The legally required cover for damage you cause to others.
On top of that to third-party liability, a fixed list of events beyond your control.
Also damage to your own light quadricycle (brommobiel) through your own doing or with no other party involved.
What is covered
| Situation | Third-party liability | Comprehensive |
|---|---|---|
| Damage you cause to someone else with the Rocks-e | Yes | Yes |
| Injury to your passenger | Yes | Yes |
| Theft with the prescribed security in use | No | Yes |
| Parking damage with no known other party | No | Yes |
| Damage to the battery pack after a covered accident | No | Provided that |
| Driving without a valid licence for the category | No | No |
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that determine whether the policy actually fits when you claim.
The Rocks-e is registered as a moped. That means a moped registration, a design speed of 45 kilometres per hour, no access to the motorway and a licence requirement that goes with the moped category. In insurance terms the vehicle therefore comes under a light quadricycle policy and not under car insurance. If you take out car insurance all the same, the cover does not match the registration and argument arises about the basis after a loss.
Ask whether the battery pack comes under own-damage cover and whether a separate limit or depreciation applies. On electric vehicles the battery is often the most expensive component. Also check whether conditions apply to charging, such as using the cable supplied or a sound connection. Because the body panels on this model are plastic and the supply of parts is limited, a repair bill comes to more than the extent of the damage suggests.
The following, among others, are outside the cover: driving without a licence valid for the moped category, or by someone who does not meet that requirement; taking part in races, speed trials and gymkhana events; use away from the public road or off-road where the policy gives no cover; and theft without the prescribed security. Gradual decline in battery capacity, wear and damage through intent or recklessness are also excluded, the last of these under Article 7:952 of the Dutch Civil Code.
Light quadricycles are often used by young drivers or, conversely, by people who no longer hold a car licence. Whoever regularly drives the vehicle determines the premium and must be declared. On taking out the policy, the duty of disclosure under Article 7:928 of the Dutch Civil Code; breaching it can cause the payout to lapse (Article 7:930 of the Dutch Civil Code). If you use the Rocks-e for delivery or other professional carriage, report that separately: a private policy generally does not cover it. You report a loss as soon as is reasonably possible (Article 7:941 of the Dutch Civil Code).
This is what people ask us most.
In law, a moped on four wheels. The vehicle has a moped registration, is restricted to 45 kilometres per hour and may not use the motorway or a dual carriageway. You therefore insure it with light quadricycle insurance, not with car insurance. The insurance obligation under Article 2 of the Dutch Motor Insurance Liability Act (WAM) applies in full: without valid third-party liability cover on an unsuspended registration, a penalty follows.
That differs from insurer to insurer and you should check it in advance. Damage to the battery pack through a covered event generally comes under own-damage cover, sometimes with a separate limit or depreciation by age. Gradual loss of capacity through normal use is not damage but wear and is not paid. If you hire the battery, check who bears which risk under the hire contract.
Often it does in the early years. The body panels are plastic and the supply of parts is limited, so repair after a small collision works out relatively expensive and the vehicle is quickly an economic total loss. As the market value falls, third party, fire and theft or third-party liability alone becomes more attractive. Assess that each year against the current value and your excess.
Someone holding a licence valid for the moped category in which the vehicle is registered. A car licence is generally enough for that. If someone drives without valid entitlement, damage to the vehicle itself is not covered and the insurer may recover from you the payment made to the other party. So always declare regular drivers.
Under third party, fire and theft or comprehensive cover, theft is covered, provided the security requirements in the policy have been met. If the prescribed security is missing or the vehicle was left unlocked, no payment follows. Always report it to the police straight away, notify the insurer of the theft and hand in all keys. Payment is based on the market value, or on the purchase value if your policy provides for that in the initial period.
Every situation is different. For these situations we have a separate page.
Request a quotation by registration number without obligation. We check the level of cover, the battery and the security requirements.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.