

Liability
- Damage to third parties
- Employers' liability
- Care, custody and control as an extension
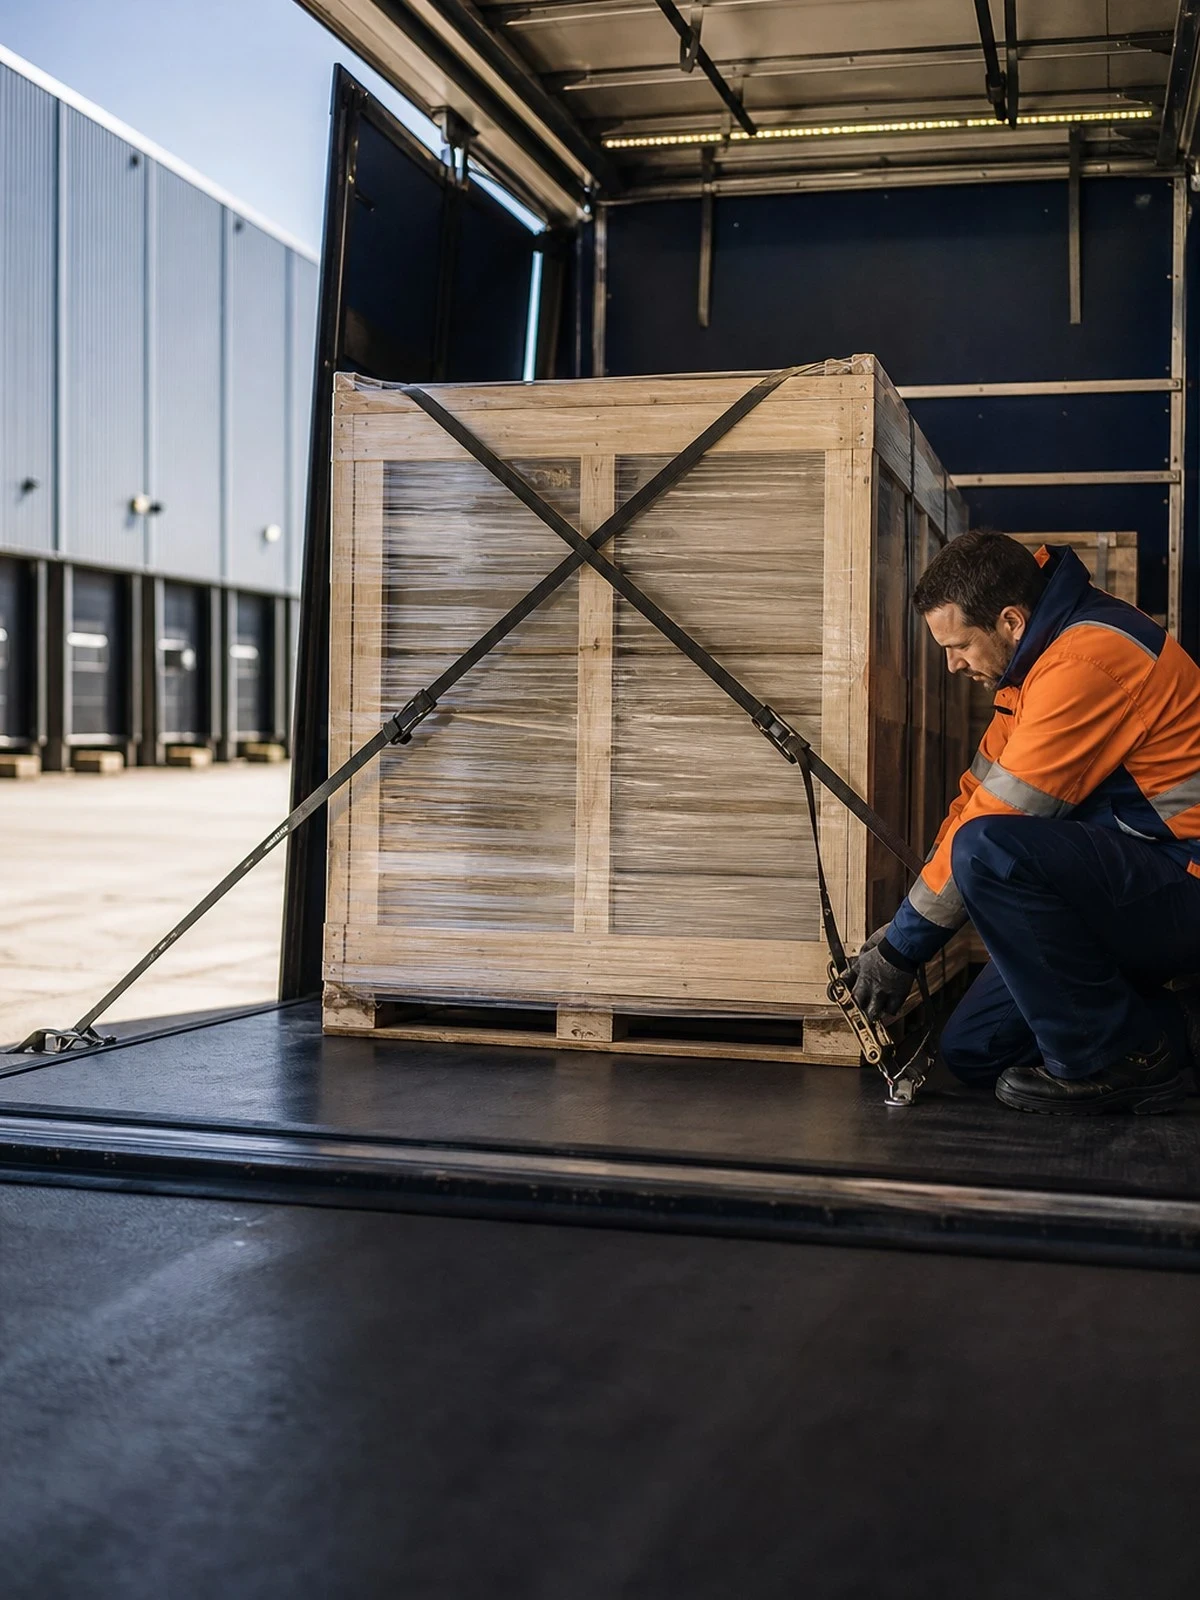
Your liability as a carrier is capped per kilogram by law and by treaty, while the value of the cargo is not.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
That is the essence of the carrier's risk. In cross-border road transport the CMR Convention applies, with a liability limit of 8.33 SDR per kilogram of cargo damaged or lost. In domestic transport the AVC conditions apply with a limit of € 3.40 per kilogram. If you carry light, valuable goods, that limit covers a fraction of the actual value and the rest stays with the cargo interest.
That cap works both ways. It protects you against unlimited claims, but it also means clients assume you carry more than you do. So record in writing beforehand who takes out the goods in transit insurance. If that is not done, it turns out after a loss that nobody had insured the value and the dispute becomes whether you are entitled to rely on the limit at all.
Carrier's liability insurance is separate from your public and employers' liability insurance: the first covers damage to the cargo carried, the second damage to third parties outside the contract of carriage. If you also do loading, unloading or storage work, you touch a third regime, because storage falls under different conditions from carriage.
We compare your personal liability insurance (AVP) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Personal liability insurance (AVP)
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
AVB for property damage and injury, BAV for professional errors.
Business contents, goods and lost turnover during downtime.
Sickness absence, accidents and the traffic risk.
What is covered
| Situation | AVB | BAV | Cyber |
|---|---|---|---|
| Injury to a visitor or customer | Yes | No | No |
| Damage to a client's property | Sometimes | No | No |
| Financial loss caused by an advisory or calculation error | No | Yes | No |
| Downtime after a ransomware attack | No | No | Yes |
| Data breach involving personal data | No | Sometimes | Yes |
| Damage to property in your care | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
You cannot rely on the limit per kilo in cases of intent or equivalent wilful recklessness on your part or that of your subordinates. A driver who leaves the tractor unit with a full trailer unattended in an unsecured car park when the instructions said otherwise puts your entire protection under the limit at risk. Set the parking and routing policy out in writing and monitor compliance. That file determines your position.
Under the CMR a claim is in principle time-barred one year after delivery, and three years in cases of intent. Visible damage has to be noted by the consignee on delivery, and damage that is not visible within a short period afterwards. Have your driver obtain a signature on the consignment note at every delivery and photograph the cargo at loading and at delivery. A clean consignment note is your strongest defence.
If you subcontract trips, you remain liable to your client as the contractual carrier. You then recover your charter's loss from them, provided they are insured and recovery is possible. Check the policy, the licence and the registration number for every new charter, and do not work with parties who only make contact by telephone; cargo theft through a forged charter agreement is a real scenario.
Damage caused by an inherent defect in the cargo and by inadequate packing by the consignor is excluded, as is damage resulting from the client's own instructions. Under the CMR, delay damages are limited to no more than the carriage charge. Customs duties and fines arising from an incorrectly completed customs document do not fall under ordinary cover. And damage to your own tractor unit and trailer is own-damage, not liability.
This is what people ask us most.
The CMR is a convention that applies mandatorily to cross-border road transport between contracting states, with a limit of 8.33 SDR per kilogram. The AVC are general conditions that parties agree for domestic carriage, with a limit of € 3.40 per kilogram. You cannot contract out of the CMR. The AVC only apply if you validly declared them applicable when the contract was concluded.
Not as the carrier. Goods in transit insurance insures the interest of the owner of the cargo and pays the actual value, regardless of who is liable. The client often takes it out. Agree expressly who does so and record it in the transport order, because with light valuable goods the difference between the limit per kilo and the value is the whole amount of the loss.
Theft of the cargo falls under your carrier's liability, up to the applicable limit per kilo and provided you met the conditions. Insurers set requirements for parking, alarms and leaving vehicles unattended. Theft of the trailer itself is own-damage on the motor policy. Where cargo is stolen after a forged transport order, there is often an argument about whether there was carriage at all.
Storage is a different service from carriage and falls under different conditions, with its own liability regime. Short-term storage that is inseparable from the trip is sometimes included; independent storage in a warehouse almost never is. Declare storage activities expressly, otherwise a gap appears at exactly the moment the goods are standing still.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.