

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
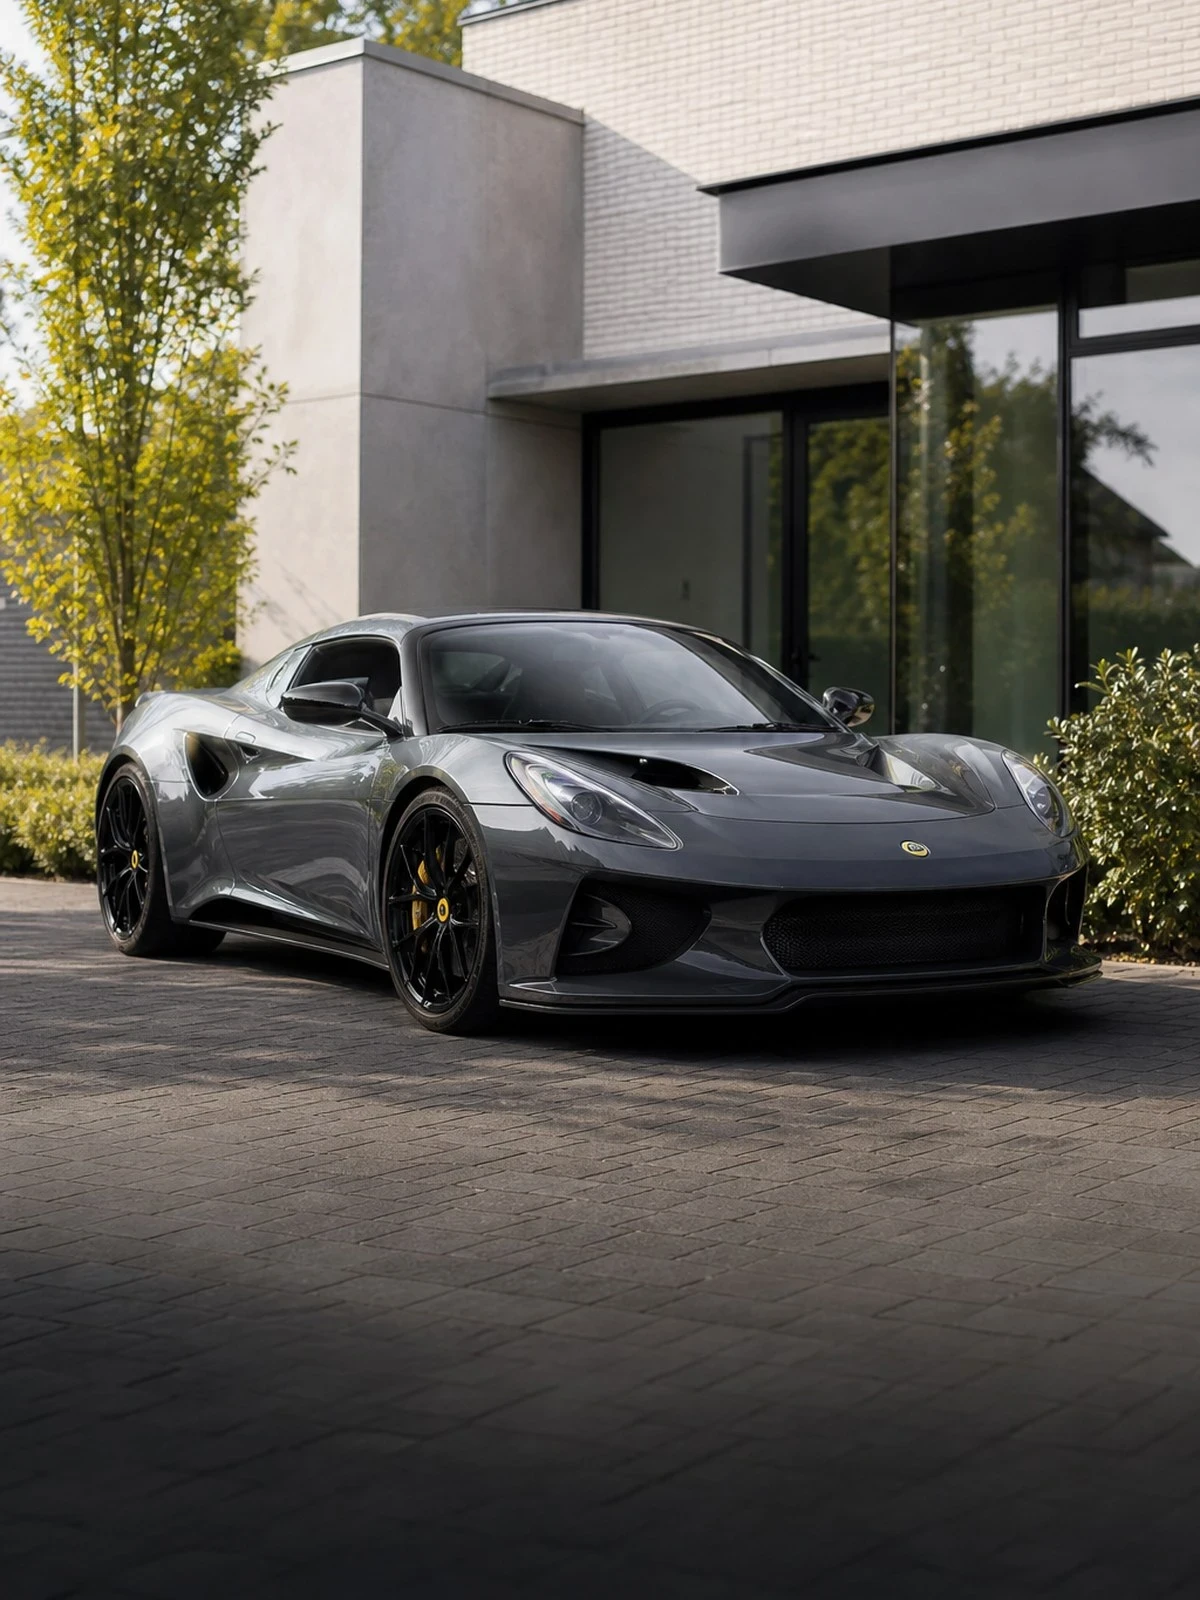
A Lotus is built light on a bonded aluminium chassis and is used on circuits more often than average. The policy differs on both points.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The chassis is the decisive factor here. Models such as the Elise, Exige and Emira are built around an extruded aluminium frame whose sections are bonded and riveted. A structure like that cannot be straightened like a welded steel floor pan. If the frame is damaged, replacing a section or the complete chassis is the only technically justifiable route. As a result a collision that looks limited in a photograph can still lead to a total loss.
The second point is use. A considerable proportion of Lotus drivers take part in track days, touring runs and club events. Driving on a circuit is excluded under practically every ordinary policy, including an instruction or introduction day and even where no times are taken. Separate day cover can sometimes be arranged, but always in advance. Reporting afterwards that the damage arose on a track leads to refusal of the own-damage part.
Modifications are common with this make: different suspension, a roll bar, bucket seats with a harness, a supercharger or a modified exhaust. Modifications of that kind change the risk accepted and must appear on the policy schedule. An undeclared change in power falls under the duty of disclosure in Article 7:928 of the Dutch Civil Code and can affect the payout through Article 7:930 of the Dutch Civil Code. See also comprehensive or third-party, fire and theft for the choice of cover.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
With a damaged aluminium frame, measuring it matters more than the visible bodywork. If the chassis is out of tolerance, replacement of a section or of the whole follows, with practically the entire car dismantled. The labour hours involved mount up quickly in relation to the value. After a loss, always have a chassis measurement carried out by a specialist first, before a repair estimate is made on the basis of the bodywork alone.
Track days, sprint runs, club competitions and skill trials fall outside the standard cover. That applies to instruction laps and to sessions in which no times are taken as well. Separate day covers exist for own-damage on track. You take those out before you enter. Liability for damage to the track itself or to other participants is moreover often dealt with separately in the participants' regulations, outside your car policy.
Modifications that increase power, different suspension or wheel sizes and safety equipment such as a roll bar or harness change both the risk and the value. If the car appears on the policy as standard and it is not, there is an incorrect declaration. Moreover, parts not stated are usually not paid for when you claim. Have the modifications recorded and keep invoices and fitting certificates; that also forms the support for a valuation.
The following remain outside the cover: any form of use on a circuit or site where speed or skill is tested; wear and mechanical defects, including clutch and engine damage without a collision; damage to or caused by undeclared modifications; damage to the hood fabric of an open version through ageing; and damage during carriage on a trailer, which falls under the carrier's cover or separate transport cover.
This is what people ask us most.
Because the car is light and its value therefore stays limited, while chassis damage is an expensive operation. The bonded aluminium frame cannot be straightened. A section or the whole chassis has to be replaced, with the car taken almost completely apart. The labour hours then quickly exceed the market value.
Not on the ordinary policy. There are specialist day covers for own-damage during a track day, taken out per event and in advance. Note too that the track's participants' regulations often provide that damage to crash barriers and track equipment is at your expense. That does not fall under ordinary car insurance.
Yes. Every modification that affects the power, the handling or the value belongs on the policy schedule. If you do not do that, the insured object differs from reality and the insurer can reduce the payout. Parts not declared are moreover usually not paid for at all when you claim.
On a well-maintained example with documented modifications it is. Without a valuation the assessor judges the market value against comparable cars for sale, which for this make are few and vary widely. A valuation report fixes the value in advance and takes the modifications into account, so that the argument about the amount of the payout after a loss falls away.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.