

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
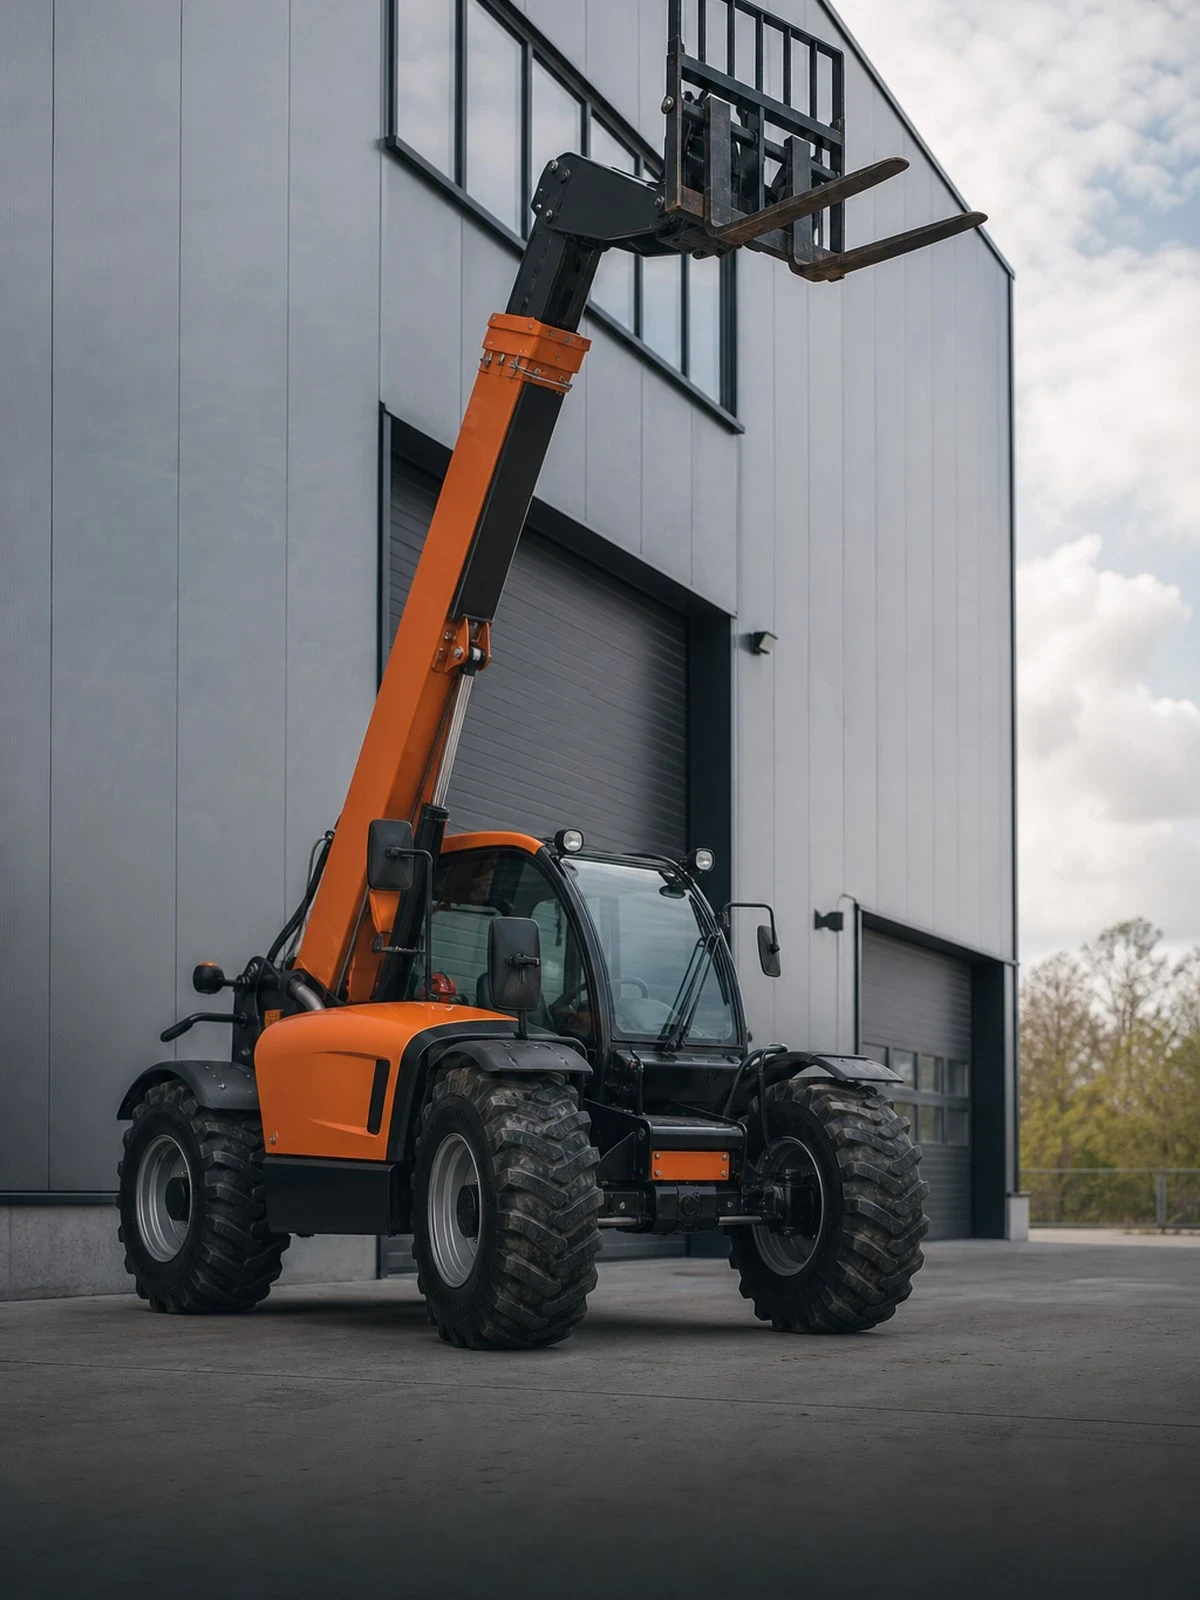
On a telehandler the carrying capacity falls with every metre the boom extends forward, and with every attachment you fit the chart changes again.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A telehandler is not a forklift truck with a long mast and not a crane with outriggers. What characterises the machine is the telescopic load moment: the further the boom extends, the smaller the load the machine can still carry without tipping forward. Every attachment has its own load chart for that. Working outside that chart is a ground for exclusion in almost every policy, including for own damage to the machine itself.
The second feature is interchangeability. With forks you are a forklift truck, with a bucket a loader, with a hook and sling you are lifting, and with an approved work platform you are lifting people. Those attachments are not automatically insured: they are separate items with their own value.
The third feature is that the load is almost never yours. Roof tiles, trusses, bulk bags or bales that you lift and place on scaffolding or a roof are things in your care, custody and control. For how the cover is built up, see the plant and machinery insurance.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The permitted weight depends on the extension length and the boom angle, not on what the machine can get onto the forks. Anyone who bypasses or overrides the load moment limiter to place a load anyway is working outside the manufacturer's specification. If the machine then tips forward, that is a classic ground for exclusion, and not only the damage to the telehandler goes unpaid but so does everything around it.
Forks, rubble bucket, bale clamp, concrete skip, lifting jib and work platform together represent a considerable value and are not automatically insured; declare them separately. Operation matters just as much: after every change the matching chart should be selected and the quick coupler demonstrably locked. An attachment that comes loose because the lock was not checked is an operating error with a risk of injury to everyone in front of it.
If a pack of roof tiles slides off the forks or a bulk bag swings into a facade, this concerns things in your care. They fall under the care, custody and control exclusion in the liability cover, whereas own-damage cover relates only to the telehandler itself. If you damage the structure being worked on, that belongs with the project's construction insurance. Anyone who regularly carries and lifts materials needs an extension for care, custody and control.
A work platform on a telehandler is permitted where the platform and the machine have been approved as a combination and are correctly coupled. A pallet or a borrowed platform is not. If it goes wrong, you are liable under Article 7:658 of the Dutch Civil Code for the injury to your own employee and at the same time have a problem with your cover. If you regularly work at height with people, a aerial work platform is the appropriate means.
This is what people ask us most.
No. The pack, the bales or the skip you lift are things in your care and that exclusion appears in almost every liability cover. Own-damage cover applies solely to the telehandler itself. If you regularly move other people's materials, have a care, custody and control extension included with a suitable limit; without that extension it is precisely the most common loss that is uninsured.
Only with a work platform that has been approved together with this machine and is coupled and secured as prescribed. A pallet, a platform from another machine or an improvised structure will not do. If someone falls, you are liable as the employer under Article 7:658 of the Dutch Civil Code and the insurer will take the course of events into account in assessing cover.
Not automatically. Forks, rubble bucket, bale clamp, lifting jib and work platform are separate items that you have to declare with their value, otherwise there is no cover in the event of theft or damage. Also report it when you buy an additional attachment later. With lifting gear such as slings and chains, inspection and rejection are subject to their own regime.
Damage to the telehandler itself falls under own-damage cover, provided you worked within the load chart; use outside the manufacturer's specification is excluded. Damage to buildings or injury to bystanders runs through the liability cover. The load you were carrying falls outside that, because it is in your care. So a single incident touches three different questions of cover at once.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.