

Liability
- Cables and pipes
- Damage to crops or buildings
- Injury to bystanders
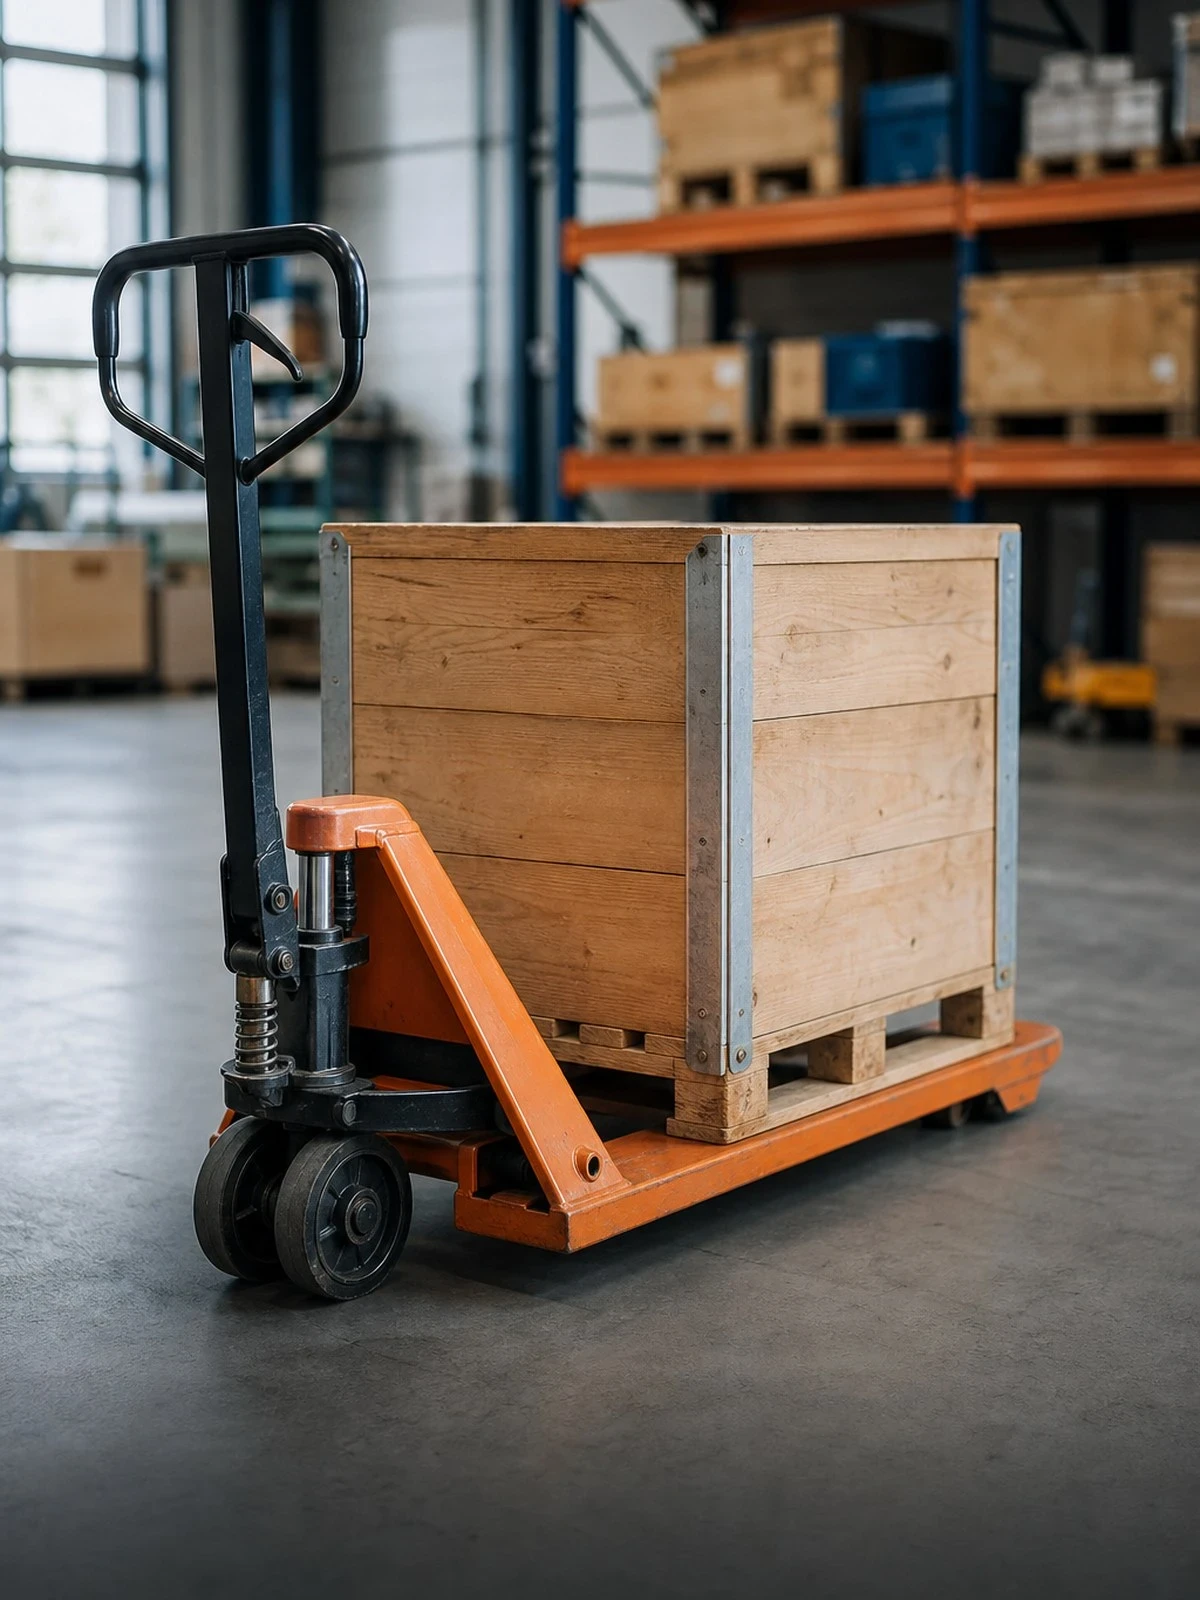
Warehouse plant drives indoors, between racking and people: the loss lies in the racking upright that has been hit, in the load on the pallet and in the colleague who gets trapped.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Hand pallet trucks, electric pallet trucks, stackers and order pickers are internal transport equipment. They rarely go onto the public road, so the insurance obligation under the WAM usually plays no part and the emphasis lies entirely on liability inside the building and on own-damage cover against fire and damage.
Two things make this category distinctive. First the inspection requirement: lifting and hoisting equipment has to be inspected periodically under the Dutch Working Conditions Decree, and where there is injury an expired inspection certificate is immediately a reproach directed at you. Second the load: what sits on the forks is property in your care.
Injury to an employee who is struck or trapped runs through Article 7:658 of the Dutch Civil Code. If your employee hits a third party, Article 6:170 of the Dutch Civil Code comes into play. The equipment itself belongs on the plant and machinery insurance.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage, theft and usually inherent defect as well.
What matters besides the machine itself.
What is covered
| Situation | Liability | Own-damage cover |
|---|---|---|
| Damage to crops, buildings or pipes and cables | Yes | No |
| Theft of the machine | No | Sometimes |
| Fire or storm damage | No | Yes |
| Inherent defect or operating error | No | Sometimes |
| Blades, teeth and tyres worn out | No | No |
| Deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Pallet racking is designed for vertical loading. A deformed upright loses a large part of its load-bearing capacity. After an impact the bay has to be emptied and assessed, and that means downtime in that aisle. The repair falls under liability if the building or the racking belongs to someone else. If you conceal an impact and the racking collapses later, Article 6:174 of the Dutch Civil Code comes into play for the building owner as well.
If a pallet of a customer's goods tips over, that is damage to property in your care, custody and control and that section is excluded or restricted on most liability policies. If you work as a logistics service provider, that risk is carried by goods or carrier's liability cover, not by the plant policy. Arrange this in advance, because the size of one toppled pallet of electronics comfortably exceeds the value of the truck.
The Working Conditions Decree requires periodic inspection of lifting and hoisting equipment, with an inspection record for each machine. Every operator must also have demonstrably been instructed. If either is missing when an accident occurs, your defence under Article 7:658 of the Dutch Civil Code has virtually no chance of succeeding and the insurer can refuse the own-damage claim for breach of the operating instructions. Agency workers and holiday staff are the most common gap here.
Electric warehouse equipment is charged overnight, often in a corner of the hall next to packaging material. Charging fires with lead and lithium batteries are a well-known cause of a whole warehouse burning down. Insurers therefore set requirements for a separate charging area, ventilation and the use of the original charger. Battery degradation itself, that is a battery losing its capacity, is never insured: that is wear.
For higher values, insurers require a tracker and agreements on where the machine is kept outside working hours.
Blades, teeth, cutting edges, tracks and tyres are wearing parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
Lifting and hoisting equipment falls under the inspection obligation in the Working Conditions Decree. The frequency depends on use, but annually is common practice. The inspection record should stay with the machine. After an accident that is the first document the Labour Authority and the insurer ask for. An expired inspection certificate makes your position under Article 7:658 of the Dutch Civil Code considerably weaker.
Not on the plant policy. Goods you handle with the forks are property in your care and that section is excluded as standard or insured up to a limited amount. For customers' stock, goods or logistics liability cover is the right place. For your own stock that is the commercial business contents and goods policy, not the cover on the handling equipment.
As the hirer you are responsible for a safe workplace and for instruction, including for temporary staff. Injury to the employee who was struck runs through Article 7:658 of the Dutch Civil Code against the employer and often against the hirer as well. The driver's own mistake is attributed to you under Article 6:170 of the Dutch Civil Code. So always record instruction given to agency workers in writing.
Yes, provided the equipment appears on the policy schedule and the location has been declared. Hand pallet trucks are often forgotten because they represent little value, but electric stackers and order pickers are certainly a target. Insurers look at the security of the building and at whether the keys or battery keys are stored separately after working hours.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.