

Extended cover
- Fire, smoke and lightning strike
- Storm from force 7 upwards
- Water damage and leakage
- Burglary damage
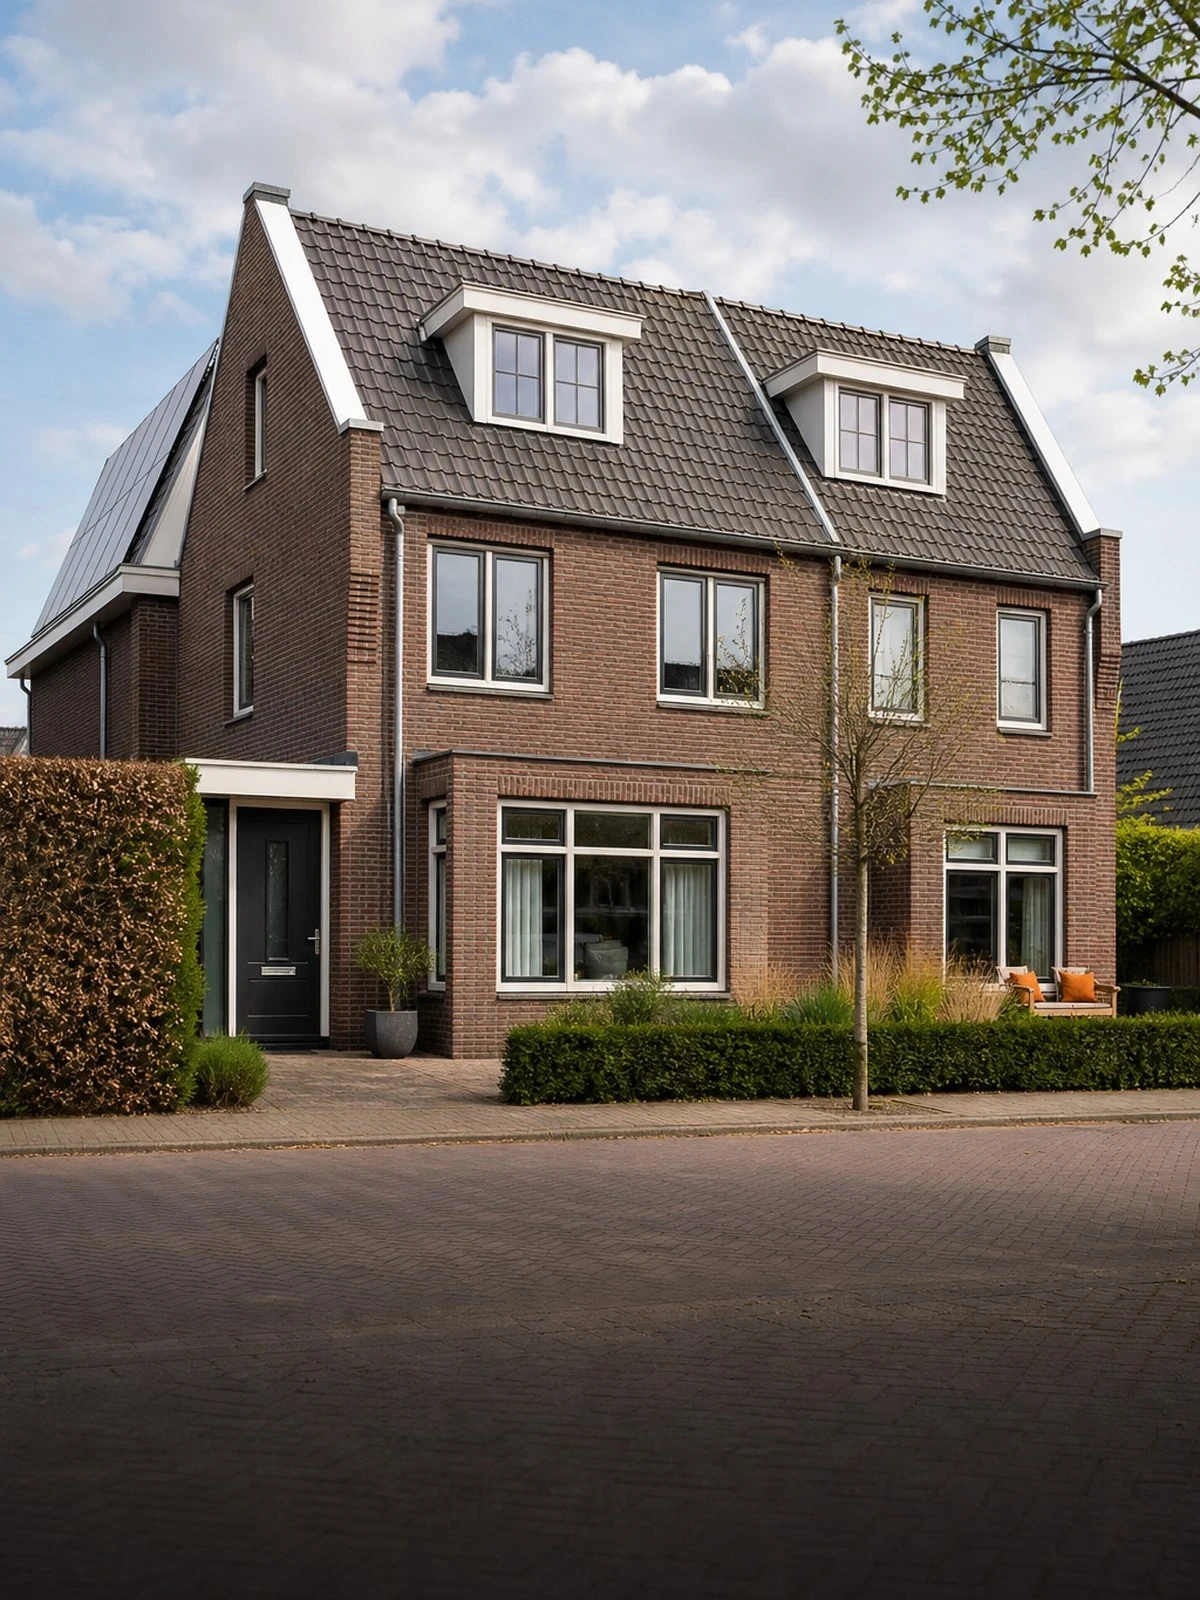
A semi-detached house is literally what the name says: you share not only a wall but usually a roof structure, a gutter and a roof surface with exactly one other owner.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The name points to what matters in insurance terms. With this type of house the roof structure often runs unbroken across both houses, with a system of purlins, a continuous gutter and sometimes a shared chimney flue. In many older houses the vertical party wall ends at loft level rather than above the roof surface, which makes the loft in effect a single space.
On the other hand you have three elevations of your own and usually your own drive. The rebuild value is therefore clearly higher than for a terraced house, and there are more often outbuildings on the plot: an attached garage, a carport, a garden shed. These are only covered if they have been declared.
The third point is that you depend on one neighbour. If his half of the roof is not maintained, if his gutter stays blocked or if he carries out work on the shared structure, that affects your house directly. A liability question between two owners runs through Article 6:162 or 6:174 of the Dutch Civil Code.
We compare your buildings insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Buildings insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The named perils: fire, storm, water, burglary and collision.
All sudden and unforeseen damage from outside, unless excluded.
Rebuild value with a guarantee against underinsurance, or a valuation.
What is covered
| Situation | Extended | Comprehensive |
|---|---|---|
| Fire, smoke and lightning damage | Yes | Yes |
| Storm damage from force 7 upwards | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Burglary damage to doors and frames | Yes | Yes |
| Drilling through a pipe while doing DIY | No | Yes |
| Subsidence, pile rot and deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
If the party wall stops at loft level, there is no barrier between the two houses under the tiles. A fire in one loft is then a fire in the other within minutes. For older houses insurers ask about this construction and can offer more favourable conditions if it is altered. If you are opening up the roof for insulation anyway, that is the moment to carry the separation up above the roof surface.
A continuous gutter running across both houses overflows when it is blocked, regardless of which side the leaves are on. The resulting leak is often gradual and therefore excluded, even under comprehensive cover. Agree with your neighbours who cleans it and when, and record that. In the event of a sudden break or a gutter bracket coming loose after a storm, there may well be cover, provided maintenance was demonstrably in order.
This type of house usually comes with an attached garage or store, sometimes a carport or a free-standing garden shed with electricity. Every outbuilding belongs separately in the declaration, together with its construction type: timber or corrugated sheeting is assessed differently from masonry with a hard roof covering. If they are missing from the sum insured, there is no cover for the outbuilding after a fire and you are underinsured on the whole as well.
Poor maintenance of the shared structure, so rot in a purlin, washed-out pointing in the party wall or a weathered gutter, falls outside the cover. The same applies to damp penetration and to settlement of the foundations under both halves; see foundation damage. If your neighbour carries out work on the shared wall and that causes damage, it is a liability matter under Article 6:162 DCC and not damage to your building.
An extension or dormer window raises the rebuild value. Report it after the work, otherwise you will become underinsured without noticing.
If you fill in the insurer's rebuild value calculator correctly, you will usually receive a guarantee against underinsurance: in the event of a claim the actual amount is paid, even if the sum insured turns out to be too low. Your policy schedule states whether you have that guarantee. Without it, the proportionality rule applies, and that also affects small claims.
This is what people ask us most.
Both owners, each for the half belonging to their house. In reality this only arises when there is damage: if the wall is damaged by an event at one of the two, the insurer of the affected house settles it and recovers where necessary. If the ownership boundary is unclear, check the deed of transfer and the land registry records.
For your own policy it is, as soon as damage results. A gradual leak caused by poor maintenance is excluded, even where it was the other party's maintenance that fell short. What remains is to hold your neighbour liable under Article 6:174 of the Dutch Civil Code as the owner of a defective structure. Set the situation down in writing and photograph the defects before damage occurs.
No. Outbuildings are only covered if they have been declared on the application, stating the construction type and floor area. That also applies to a carport, a garden shed with electricity and a canopy. If the garage is used for business or a classic car is kept there, report that separately; the use counts in the underwriting.
Because with this type of house the roof often runs across both properties. If the party wall stops at loft level, fire can travel unhindered under the tiles to the other half and the scale of the damage doubles. A separation carried up above the roof surface limits that considerably, and with some insurers it can lead to more favourable conditions.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.