

Liability insurance for a self-employed solar panel fitter
You work on your client's roof and on their electrical installation at the same time. That produces two very different losses: leaks and fire, each with its own policy argument.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
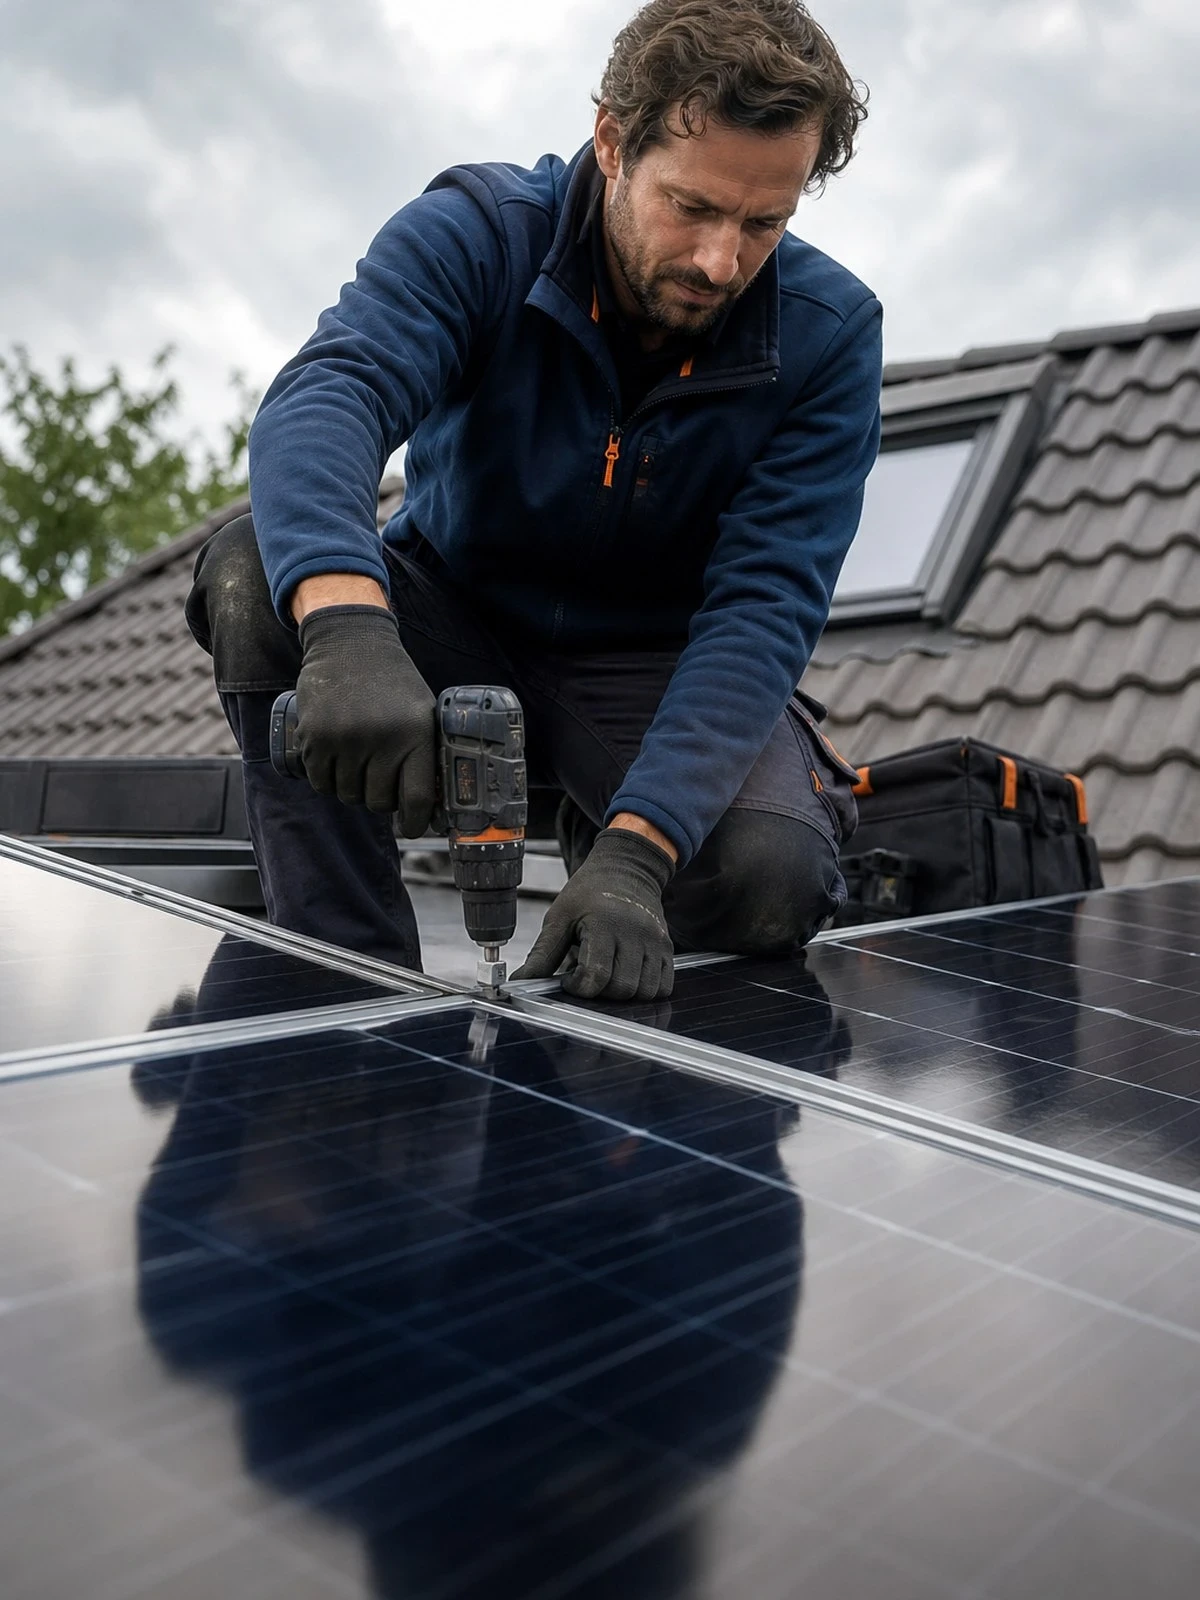
Every fixing on a pitched roof is a hole in a waterproof layer. A hook that lifts a tile, a penetration that is not properly sealed or a ballast system that damages the roof covering lets rain in. The damage to the ceiling, the insulation and the belongings below is property damage to a third party and fits within public and employers' liability insurance. Putting right your own penetration or resetting the system is not, and the roof area you are working on also falls under the care, custody and control exclusion.
The most serious damage comes from the direct current side. Connectors from different brands pushed together, a plug that is not fully tightened or a cable chafing on a sharp edge produce an arc in time. That fire rarely stops at the panels: the roof goes with it and sometimes the whole building. Insurers attach conditions to that, usually in the form of a work instruction, a final check and a test report at handover. Keep those reports, because after a fire they determine whether you are liable under Article 6:162 of the Dutch Civil Code.
What you calculate for the client is a third category. If the yield disappoints through shading, a wrong orientation or an inverter chosen too small, nothing is broken and the client has simply earned less. That pure financial loss belongs on a professional indemnity insurance. You insure your own fall from the roof with disability insurance.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four points that determine whether damage involving solar panels reaches the insurer.
Penetrations, fixings and load-bearing capacity
A roof structure is designed for snow and wind, not automatically for an additional system with ballast. If deflection occurs or water gets in, the owner holds you liable and can also be held liable himself as possessor of a defective structure under Article 6:174 of the Dutch Civil Code. Record what structure you found and on what information you based the fixings.
The direct current side and fire
Connectors that are not fully pushed home are the best-known cause of fire in PV installations. Follow the manufacturer's installation instructions, use connectors of the same type and record the final check and insulation measurement. If you depart from the requirements, the insurer can rely on the clause requiring compliance.
What falls outside the cover
Excluded are the panels and the mounting system you supplied and fitted yourself, the costs of recalling or refitting a whole installation, the roof area in your in your care has, asbestos on older shed and barn roofs, damage with an aerial platform or trailer (Article 2 of the Dutch Motor Insurance Liability Act (WAM)) and intent under Article 7:952 of the Dutch Civil Code.
What your stated capacity says
If you connect to the consumer unit yourself, or add home batteries or charging points, you are doing work on which insurers ask separate acceptance questions. If that is not in the description on your policy, the damage is not covered. If your range of work changes, report it; Article 7:928 of the Dutch Civil Code requires a correct disclosure when the insurance is taken out.
What does your premium depend on?
- Annual turnover: the basis for a self-employed professional without staff
- Type of roofs: tiled roofs, flat roofs and industrial buildings each carry their own risk
- Electrical work: connecting up yourself weighs more heavily than mounting only
- Home batteries and charging points: additional work with its own acceptance questions
- Sum insured: matched to the value of the buildings you work on
- Excess: regularly increased for fire and leak damage
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| Your ladder falls over and damages the neighbour's conservatory | Yes | No |
| You drill into a water pipe at the cable penetration and the meter cupboard floods | Yes | No |
| The client's dog receives a shock from a cable that has not yet been finished off | Yes | No |
| The optimisers you supplied turn out to be defective and all have to be replaced | No | No |
| You recommend a system that falls outside the subsidy scheme the client was counting on | No | Yes |
| You connect to an outdated consumer unit and it burns out shortly afterwards | Provided that | No |
Electrical work must appear in so many words in your description of capacity, otherwise it is precisely the most serious damage that falls outside.
Frequently asked questions
This is what people ask us most.
The roof leaks after installation. What does the policy pay?
The water damage to the ceiling, the insulation and the contents can be covered, because that is damage to the client's property. Making your own penetration watertight again falls outside it, as does the roof area you worked on in so far as it falls under the care, custody and control exclusion. Notify quickly; Article 7:941 of the Dutch Civil Code requires you to report the loss as soon as you reasonably know of it.
A fire has started at the inverter. Am I insured?
Damage to the client's building and contents is property damage and belongs to the core of this insurance, provided you are liable. The insurer will, however, investigate whether you followed the installation instructions and the conditions imposed. The panels and the installation you supplied yourself fall outside the cover as goods supplied.
Panels have blown off a flat roof and hit cars.
That is third-party property damage and fits within the cover if you are liable for the fixings. What is decisive is the ballast calculation or the mechanical fixing and the wind zone the building is in. Keep the calculation you relied on and the photographs of the completed situation, because in such a claim those form the factual defence.
The client says the yield is disappointing. Is that covered?
No. As long as nothing is broken and nobody is injured, it is about money the client expected to earn. That is pure financial loss and public and employers' liability insurance excludes it. If you make yield calculations or advise on the choice of system, insure that separately and set out in the quote what assumptions your forecast rests on.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a self-employed rooferOpen roof, torch, care, custody and control
- Liability insurance for a self-employed air conditioning fitterWorking in people's homes, facade fixings, care, custody and control
- Liability insurance for an air conditioning firmRefrigerant, condensate drainage, certification
- Liability insurance for a self-employed central heating engineerAuthority in your name, water damage, subcontracting
- Liability insurance for a self-employed chimney sweepOccupied homes, roof work, excess
- Liability insurance for a self-employed electricianSubcontracting, your own injury, care, custody and control
- Liability insurance for a roofing companyCare, custody and control, hot work, leaks
- Liability insurance for a self-employed installation engineerWater damage, combustion, certification