

Liability
- Cable and pipe damage with consequential loss during excavation
- Lifting with the excavator, provided it is within the lifting chart and with lifting equipment
- Damage to paving, adjacent buildings and vehicles on site
With Caterpillar equipment, the policy revolves around two things the insurer enforces strictly: the security you have committed to and a sum insured that has to keep pace with the replacement price.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
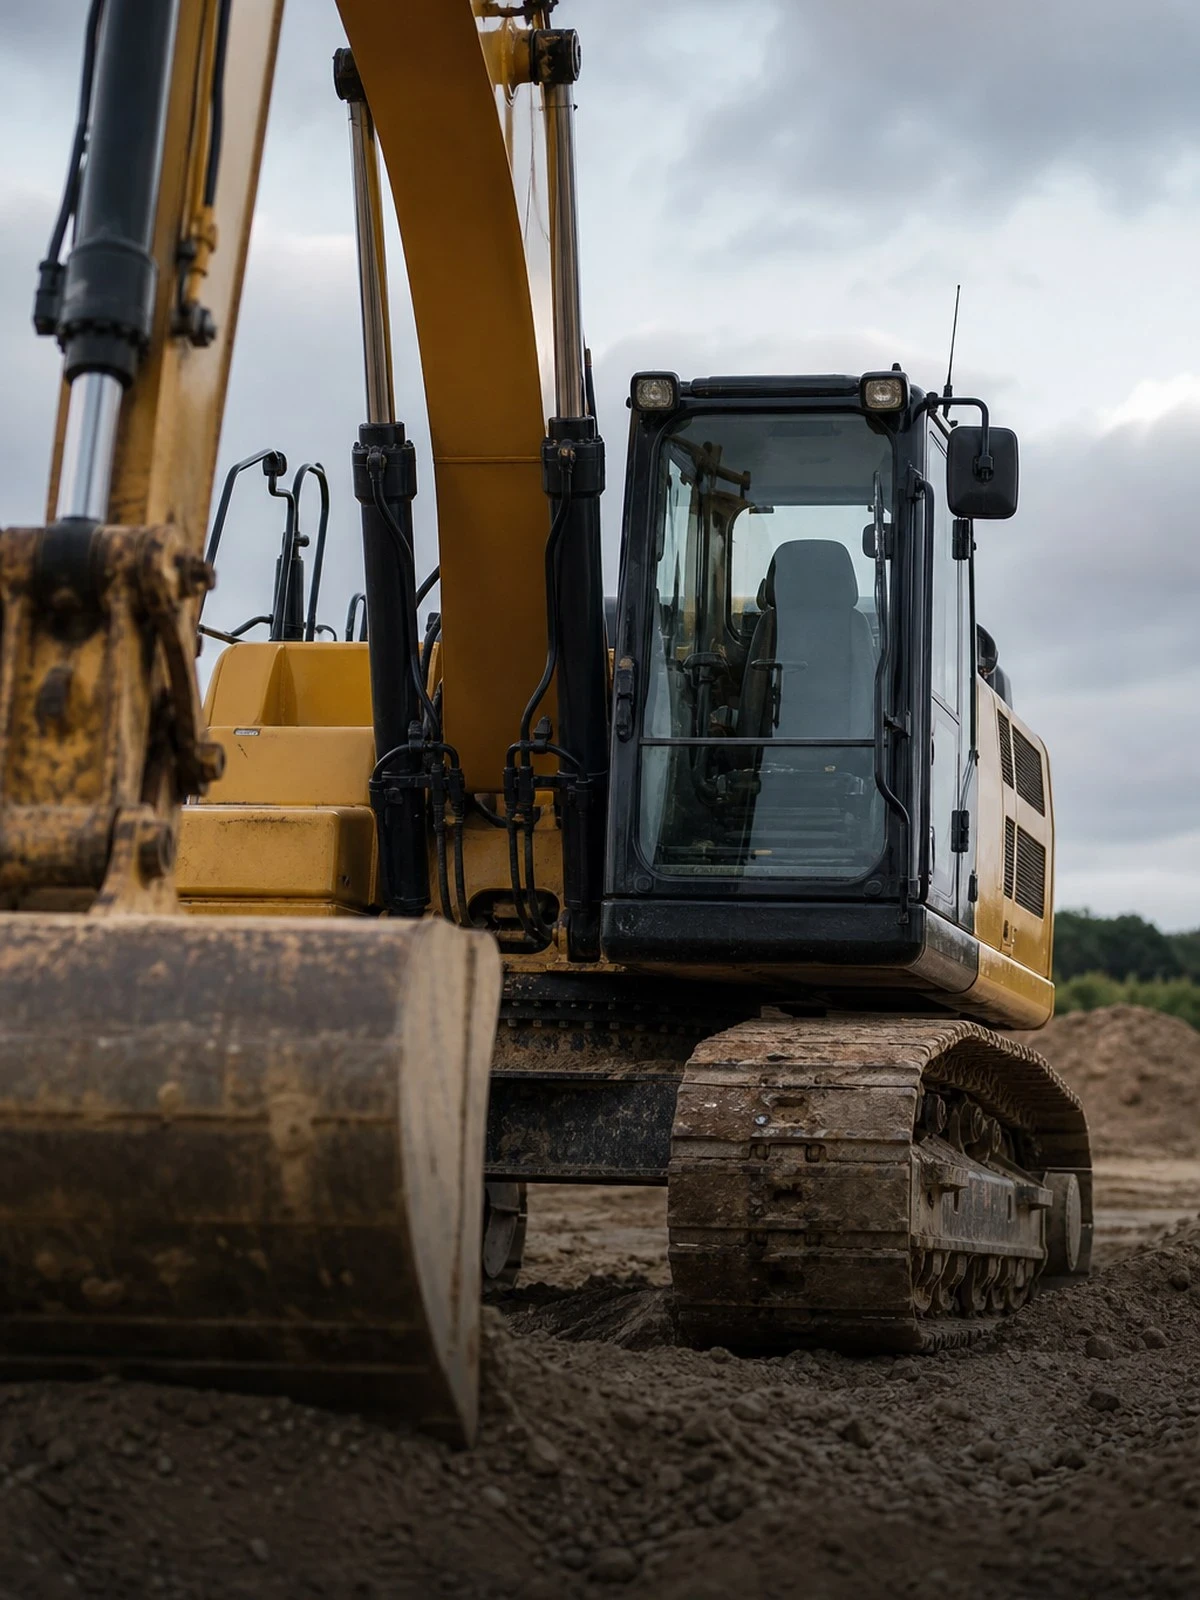
Caterpillar builds across almost the entire range of earthmoving: from compact crawler excavators and skid steers to the 320 and 336 series excavators, wheel loaders, dozers and articulated dump trucks. That means high values, from around € 50,000 for a mini excavator to several hundred thousand for a heavy excavator or wheel loader, and a machine that can be used and sold anywhere in the world. Stolen Cat equipment disappears in containers to Eastern Europe, Africa and the Middle East.
Insurers translate this into prevention requirements: a tracker with an active subscription, an immobiliser or PIN code via the Cat operating system, and agreements on storage outside working hours. These requirements are not advice but a warranty in the policy. If the tracker is not active at the time of theft, or the machine is not stored at the agreed location, the theft cover lapses or an excess applies that eats up a large part of the payout.
The second theme is the sum insured. A Cat machine that cost € 200,000 three years ago is more expensive to replace because of price increases and delivery times. A policy on current value then pays what the machine would fetch on the second-hand market, whereas a new-value or replacement-value arrangement follows the price of a new machine. We compare construction plant insurance for Caterpillar on security, value basis and liability for excavation and lifting work.
We compare your classic car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Classic car insurance
 Compare
 Get covered
For Caterpillar equipment, the choice of cover depends on the new value and age of the machine, its use in earthmoving, demolition or lifting, storage and transport between sites.
Covers the damage you cause to third parties with the Cat during work and, where necessary, on the public road under the WAM.
Covers damage to the Caterpillar itself: theft, fire, overturning, collision, vandalism and damage during work.
Covers the machine while idle and during transport between sites, on the low loader and during loading and unloading.
What is covered
| Situation | Covered |
|---|---|
| Theft from the building site | Sometimes |
| Fire and storm damage | Yes |
| Inherent defect in the hydraulics | Sometimes |
| Damage to cables and pipes | Sometimes |
| Normal wear and tracks | No |
| Damage due to deferred maintenance | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
With Caterpillar equipment, the pitfalls lie in the security clause, the value basis, lifting work and deployment in heavy work.
For Cat machines above a threshold that differs per insurer, often around € 50,000 to € 75,000, a tracker with an active subscription and an immobiliser or PIN code are a warranty on the policy. Caterpillar supplies its own tracking system via Product Link; insurers usually accept this, provided the subscription is running and alerts are set up. Check every year that the subscription is active and keep the proof. After a theft, the insurer first asks for the tracker data; if these are missing, the dispute about cover has begun.
A Cat 320 from 2022 cost around € 200,000 at the time; a new one now costs more and has a delivery time. A policy on current value pays the second-hand price in the event of a total loss, which for a well-maintained Cat is relatively high but not enough for a new one. New-value arrangements usually apply for one to three years; a replacement-value arrangement follows the price of an equivalent new machine for as long as one exists. Have the sum insured aligned annually with the Cat dealer's current price list and report price increases.
On many sites, a Cat excavator is used to lift sewer pipes, manholes and formwork. That is permitted within the manufacturer's lifting chart and with inspected lifting equipment, such as a lifting hook on the quick coupler and overload protection. Insurers cover lifting under the working risk, but after damage they assess whether the load was within the chart and whether the machine was equipped for lifting. A sewer pipe that slips out of a chain onto a worker or a pipe is a claim for which those documents will be requested.
Cat machines with a breaker, sorting grab or pulveriser work in rubble, dust and heat. Hydraulic hoses chafe through, oil reaches a hot exhaust and the machine burns out. Fire is covered under own-damage cover, but insurers set conditions for demolition use: a fire suppression system in the machine, daily inspection of hoses and no parking of a hot machine against combustible material. Declare demolition use when taking out the policy; a policy for earthmoving that is used for demolition may be assessed as an increase in risk after a claim.
A thirty-tonne Cat excavator travels from site to site on a low loader. Driving on, securing and unloading are the moments when most transport damage occurs: a machine sliding off the ramps, a boom hitting a viaduct or a load that shifts. The transport section of the construction plant policy covers this, provided the transport is carried out by you or on your behalf. If a haulier transports it, their limited liability applies; your own transport cover or an agreement on insurance is then needed.
Cat equipment is often deployed on projects of main contractors or hired out to other companies, with or without an operator. Without an operator, hiring out is usually excluded on a standard construction plant policy or requires a clause with a higher excess. With an operator, liability remains with you, including damage to the main contractor's works, for which their contractors' all risks (CAR) policy may not cover you. For every deployment with third parties, agree who bears the excess, who makes the KLIC notification and which policy pays for damage to the machine.
Questions owners of Caterpillar equipment ask us about their insurance.
For machines above a threshold that differs per insurer, often around € 50,000 to € 75,000, a tracker with an active subscription and an immobiliser or PIN code are standard, supplemented by locked storage outside working hours. Caterpillar Product Link is usually accepted as a tracker, provided the subscription is active. The requirement is a warranty on the policy; if the security is not active at the time of theft, the cover lapses or a high excess applies.
Only if the policy has a new-value or replacement-value arrangement and the machine falls within its term, usually one to three years. After that, the insurer pays the current value, the price on the second-hand market. For Caterpillar that is relatively high, but usually not enough for a new machine at today's prices and delivery times. Have the sum insured aligned annually with the dealer's price list.
Yes, within Caterpillar's lifting chart and with inspected lifting equipment, such as a lifting hook on the quick coupler and overload protection. Insurers cover lifting under the working risk, but after damage they ask about the load, the chart and the inspection. Exceeding the lifting chart or lifting without the equipment may be regarded as reckless and lead to a reduced payout. Record lifting work in the daily report.
Under a construction plant policy with a transport section, yes, provided you transport it yourself or on your behalf. Driving on, securing and unloading are usually included. If a haulier transports the machine, their limited statutory liability applies, often a low amount per kilo. In that case, agree that your own policy covers primarily or have the haulier take out additional cover. Also check that the low loader itself is insured.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.