

Liability
- Cables and pipes
- Damage to crops or buildings
- Injury to bystanders
With a field sprayer the risk is the product itself: what drifts across the field boundary or ends up in a ditch costs more than any damage to the machine.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
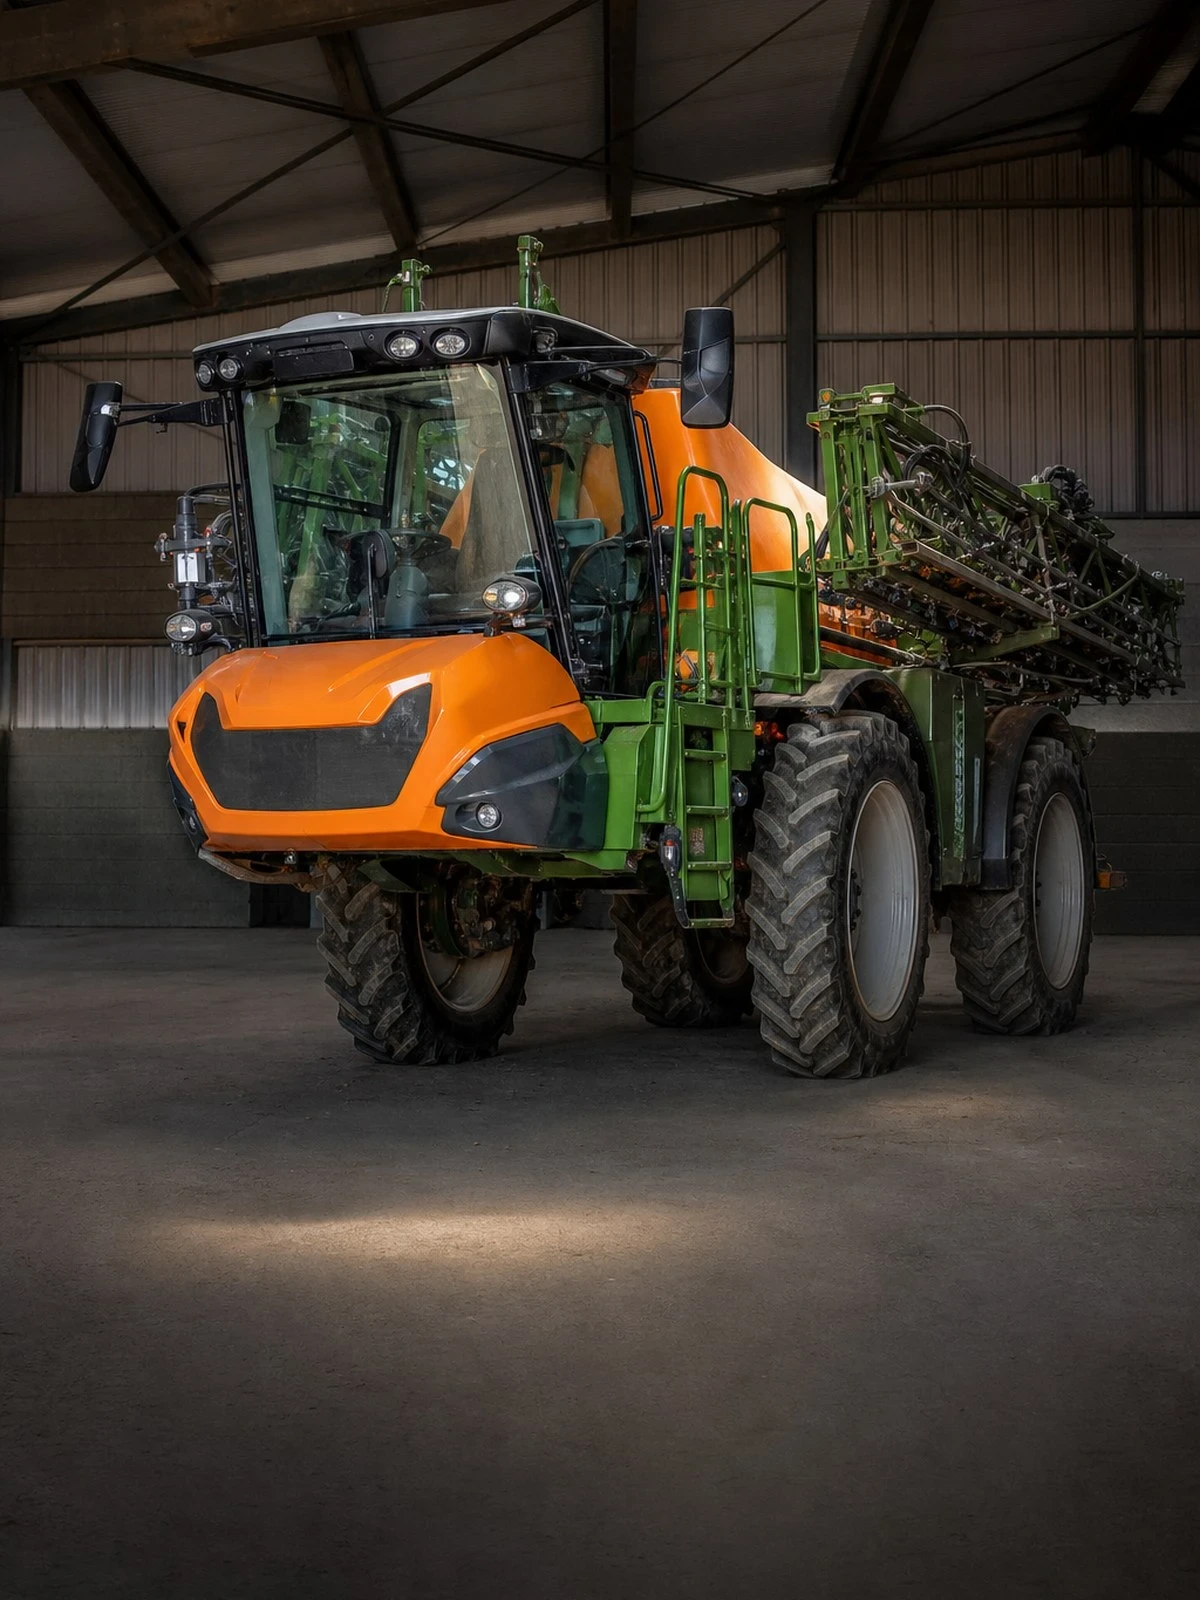
A trailed or self-propelled field sprayer is insured as plant and machinery, with own-damage cover for the machine and liability for the surroundings. What is special here is the load you carry: crop protection products are substances whose dispersal causes damage in its own right, without any collision or contact.
Drift onto a neighbouring field, an orchard or an organic crop causes crop damage and sometimes the loss of certification. That is damage to a third party’s property and falls under Article 6:162 of the Dutch Civil Code. If the product reaches surface water, an administrative dimension is added: the water board can enforce, and fines and penalty payments are never insured.
On liability cover there is almost always an environmental clause: only sudden, unforeseen contamination is covered, gradual loading of soil and water is not. The spray boom is also the most vulnerable part of the machine. The structure of the policy is set out on the plant and machinery insurance.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage, theft and usually inherent defect as well.
What matters besides the machine itself.
What is covered
| Situation | Liability | Own-damage cover |
|---|---|---|
| Damage to crops, buildings or pipes and cables | Yes | No |
| Theft of the machine | No | Sometimes |
| Fire or storm damage | No | Yes |
| Inherent defect or operating error | No | Sometimes |
| Blades, teeth and tyres worn out | No | No |
| Deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The wrong nozzle, too high a boom or spraying in unfavourable wind puts the product on someone else’s crop. With a neighbouring organic crop or a sensitive crop, the loss is not only the harvest but also the loss of certification. That is property damage to a third party and covered, provided it qualifies as a sudden event. Record the wind direction, wind speed and nozzle types used for each spraying operation.
Liability policies generally cover only sudden and unforeseen contamination. A split hose that lets hundreds of litres run into a ditch at once falls under it. Years of spraying too close to the ditch, rinsing residue away on the yard or a leaking filling point do not, because that is gradual. Cleaning up the soil beneath your own filling point is also your own loss and calls for separate environmental cover.
Spraying requires a valid certificate of competence, compliance with drift-reduction requirements and with the crop-free zone. If you breach them, enforcement follows from the NVWA (the Dutch food and product safety authority) or the water board. Fines, administrative penalty payments and criminal sanctions are not insurable under any policy. What is more, damage that is the direct result of deliberately acting contrary to a statutory rule is excluded under the intent provision in the cover.
An unfolded spray boom catches the ground at a ditch, or a post while turning on the headland. Bending caused by an identifiable impact is covered. A fatigue fracture after years of vibration is not. Also excluded are nozzles, filters, pump diaphragms and hoses as wearing parts, corrosion caused by aggressive products in the tank, and damage because the wrong or an incompatible product was mixed.
For higher values, insurers require a tracker and agreements on where the machine is kept outside working hours.
Blades, teeth, cutting edges, tracks and tyres are wearing parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
Yes, where it concerns demonstrable damage to his crop from a single spraying operation; that is damage to a third party’s property. Insurers will assess whether you complied with the drift-reduction rules. If you cannot show the wind direction, wind speed and nozzle type, the claim becomes difficult. The loss of organic certification is treated as consequential loss and is not always covered in full.
A sudden discharge, for instance through a burst hose, falls under the environmental clause and is covered, including the clean-up costs. Gradual loading is not. The water board also enforces independently: an order subject to a penalty or a fine is always for your own account. Report a discharge immediately, both to the insurer and to the competent authority.
If the bending is the result of a sudden impact with a post, a ditch edge or a tree, it falls under own-damage cover. Fatigue cracks in the folding hinges after years of use do not: that is wear. Have the damage recorded by a dealer, because with spray booms the argument about wear versus sudden damage comes up regularly.
No. Administrative fines, penalty payments and criminal sanctions cannot be insured under any Dutch liability policy. What can be covered is the civil damage suffered by third parties from the same event, provided there was no deliberate breach of a rule. Keep the spray log, the licence and the calibration records up to date; those documents determine how such a case unfolds.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.