

Liability insurance for a self-employed chimney sweep
You work indoors first, among a family's belongings, and then alone on a roof. Two very different risks in one working day.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
Indoors the risk starts at the fireplace. Soot spreading over a sofa, a rug or a bookcase is third-party property damage and therefore the territory of this policy. With a private client that often runs through his contents insurer, which pays and then recovers the loss from you. Do not admit anything yourself, report it immediately and let your insurer assess liability. Covering up before you start and a photograph of the room on arrival are the cheapest prevention there is.
On the roof the picture changes. A displaced tile, a crushed gutter, a broken solar panel or a damaged roof penetration are losses you cause to the client's building. They fall within the cover in principle, with one important exception: the part you are working on, so the chimney, the cowl or the flue itself, falls under the exclusion for property being worked on. Ask expressly, therefore, whether a care, custody and control clause is available and what it costs.
What you carry yourself: your own injury if you fall from the ladder, because liability insurance pays only for other people's losses. With no employer there is no duty of care under Article 7:658 of the Dutch Civil Code to protect you, so you end up with personal accident cover or disability insurance. Also excluded are asbestos, fines, redoing your work and claims that are only about money without injury or damaged property.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four points that make the difference when working alone in occupied homes.
Cover the contents and record the state of things
A cloud of soot in a living room quickly produces a claim for several items at once. Cover furniture and floors, work with a vacuum cleaner with a fine filter and photograph the situation before you start. Without those photographs it cannot be established afterwards which mark was already there, and then you contribute to damage that is not yours.
What you write down carries weight
Your sweep certificate or inspection note is an opinion that an occupier and his insurer rely on. If you spot a crack, a wrong connection or a missing outlet, report it in writing. A claim that is only about the consequences of your advice is pure financial loss and falls outside the cover of this policy.
You are not covered yourself
This insurance covers your liability towards others, not your own injury. If you fall from a roof, there is no employer who has to show that the workplace was safe and no continued pay. Work with inspected climbing equipment and assess for each house whether the roof can be walked on; where there is doubt, an aerial platform or turning the job down is the wiser choice.
Solar panels and fragile roofs
More and more pitched roofs are covered with panels and cabling. A broken panel, a damaged optimiser or a leak from a displaced tile is property damage that can mount up. Discuss with the occupier in advance which route you will take across the roof and record when in your view a roof cannot safely be walked on.
What does your premium depend on?
- Annual turnover: the basis for a sole trader
- Type of clients: private individuals, VvEs or maintenance firms
- Activities: sweeping only, or also inspecting, milling and renovating
- Working at height: ladder work, roof work or use of an aerial platform
- Care, custody and control cover: for the flue and the part of the roof you are working on
- Sum insured chosen: matched to the value of the homes you visit
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | Care, custody and control cover |
|---|---|---|
| Your sweeping rod knocks a roof tile loose which falls on the neighbours' shed | Yes | No |
| While removing the stove you scratch the tiles in front of the fireplace | Yes | No |
| The flue you are sweeping loses its pointing and cracks | No | Yes |
| The flue gas duct you dismantle for cleaning breaks when you put it back | No | Yes |
| The client demands the sweeping fee back because soot comes down again shortly afterwards | No | No |
| You carry on working in a 1975 house and disturb asbestos-bearing pipe insulation | No | No |
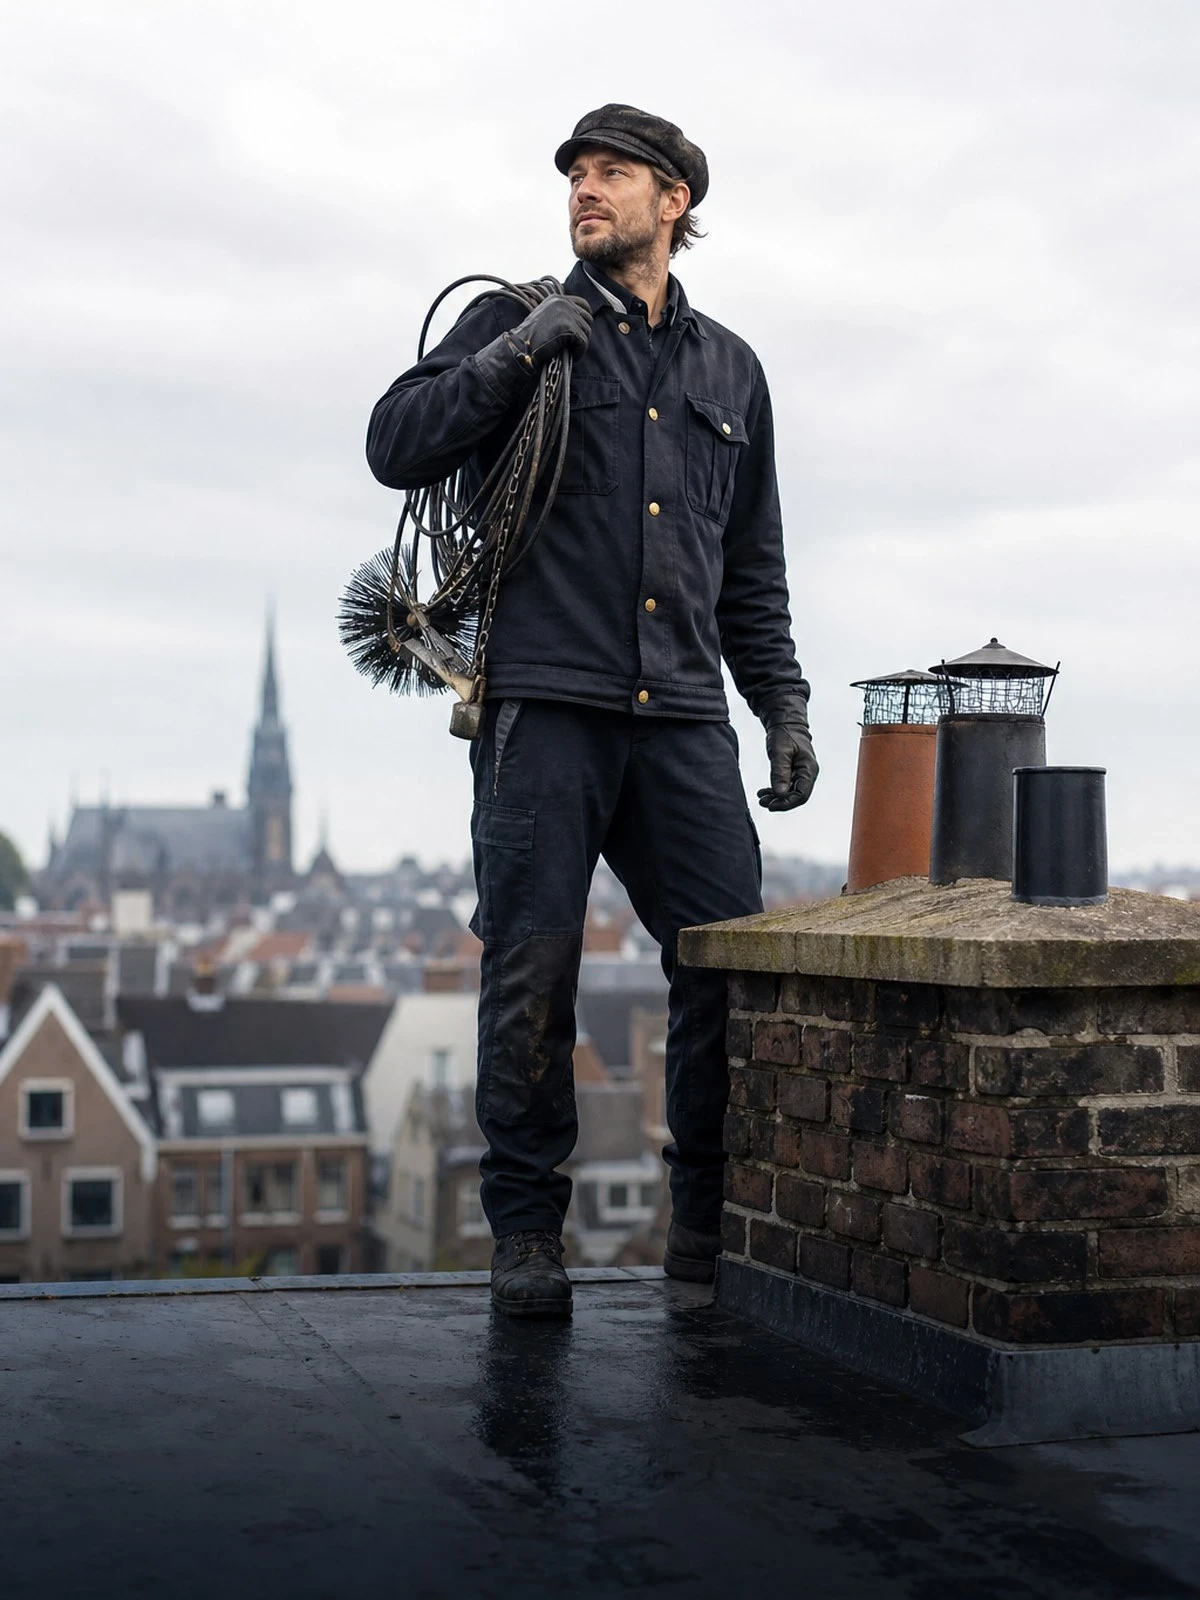
The flue and the cowl you are working on are on the right-hand side. The house around them on the left.
Frequently asked questions
This is what people ask us most.
There is soot on a client's sofa. Who pays for that?
If the soiling results from the way you worked, you are liable and the insurer pays for the cleaning or the reduction in value. The client often calls in his own contents insurer first, which then seeks recovery from you. Forward that correspondence and pay nothing out of your own pocket. An admission of your own can put your cover at risk.
My ladder slips and damages the gutter.
That is property damage to the client's building and covered in principle, because the gutter was not the object of your assignment. The position is different for the chimney itself: that is the item you are working on and it falls under the exclusion. Report even small losses at once, because a dented gutter often becomes part of a larger leak claim later.
I fall from the roof. Does this insurance cover my loss?
No. Liability insurance pays third parties to whom you cause damage, not you. As a self-employed professional you have no employer who is liable under Article 7:658 of the Dutch Civil Code and no right to continued pay. You cover your own injury and loss of income with personal accident insurance, disability insurance (AOV) or a broodfonds.
Do I need a certificate to be insured?
Insurers ask when you apply about your professional competence and about the certification that is usual in the trade, certainly if you also inspect or renovate flues. A valid certificate is often a condition for work from VvEs and housing associations. If your range of work changes, report it; Articles 7:928 and 7:930 of the Dutch Civil Code attach consequences to an undisclosed increase in risk.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a self-employed cleanerInside clients' homes, care, custody and control, recovery
- Liability insurance for a chimney sweeping companyFire, roofs, asbestos
- Liability insurance for a self-employed air conditioning fitterWorking in people's homes, facade fixings, care, custody and control
- Liability insurance for a self-employed solar panel fitterRoof penetrations, the DC side, yield
- Liability insurance for a self-employed window cleanerWorking at height, glass in your care, water damage
- Liability insurance for a self-employed rooferOpen roof, torch, care, custody and control
- Liability insurance for a roofing companyCare, custody and control, hot work, leaks
- Liability insurance for a self-employed chefRunning someone else's kitchen, allergens, recovery claims