

People at the workplace
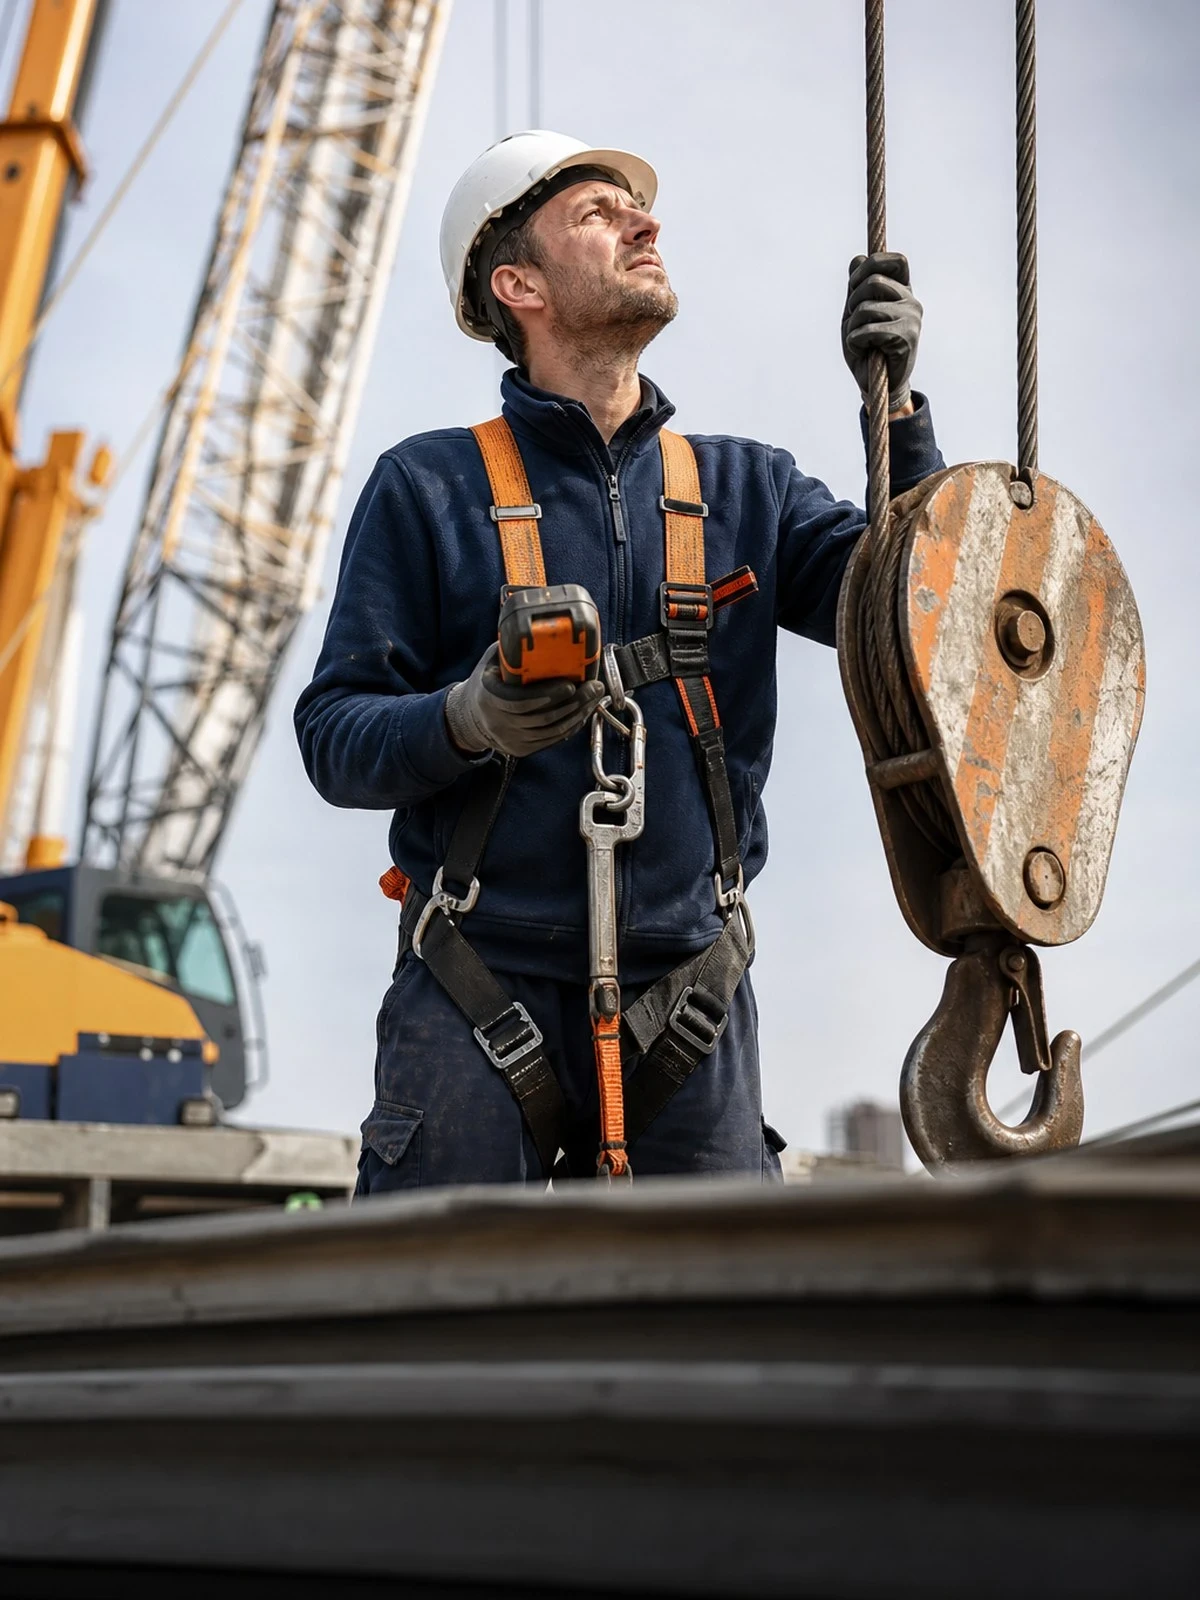
- A falling or swinging load
- Signals to the operator
- Cordoning off the lifting zone
- Also where staff are hired in
In lifting work the damage is rarely small and the question of fault rarely simple. As a rigger or lift supervisor you direct the load, and that makes you one of the first parties people look at.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A rigger's liability starts with Article 6:162 of the Dutch Civil Code: anyone who makes a mistake while carrying out their work and thereby causes loss to another has to make it good. A load slung incorrectly, a centre of gravity calculated wrongly, lifting gear that does not match the weight or a wrong signal to the crane operator: each of those can lead to injury or to damage to installations, buildings and the load itself.
If you are an employee, your employer is in principle liable for the mistakes of subordinates (Article 6:170 of the Dutch Civil Code). If you work as a self-employed professional or through an agency or contracting arrangement, the claim usually lands with you or with your client, depending on the contractual arrangements. public and employers' liability insurance (AVB) covers the property damage and injury that follow from it, provided your activities are stated on the policy.
What almost always causes discussion is damage to the load itself. You had it in your care during the lift, and that falls under the care, custody and control exclusion: excluded as standard, sometimes covered on a limited basis for an additional premium. Damage caused by the crane also runs not through the AVB but through the insurance for that plant. See also public and employers' liability insurance for riggers.
We compare your personal liability insurance (AVP) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Personal liability insurance (AVP)
 Compare
 Get covered
Three situations in which a rigger or lift supervisor is held liable.
Injury to colleagues, third parties' staff or bystanders.
Damage to buildings, pipework or third-party equipment.
The object being lifted that you had in your care during the work.
What is covered
| Situation | Basic AVB | With care, custody and control cover |
|---|---|---|
| Injury to an employee of the client | Yes | Yes |
| Damage to a building next to the lifting site | Yes | Yes |
| Damage to the load being lifted | No | Provided that |
| Damage caused by the mobile crane | No | No |
| Loss through delay without property damage or injury | No | No |
| Putting right your own defective work | No | No |
What is actually covered, including exclusions, the sum insured and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that determine who ultimately bears the loss.
Property you had in your care — borrowed, hired, being worked on or being handled — is excluded on virtually every AVB. In lifting work that is not a marginal case but the heart of the matter: the load hangs on your lifting gear and you give the signals. Insurers sometimes offer a care, custody and control cover with its own sum insured and excess. Without that extension you pay for damage to the load itself out of your own pocket.
A mobile crane, telehandler or forklift counts as a motor vehicle or item of plant with its own insurance requirement. For use on the road that follows from Article 2 of the Dutch Motor Insurance Liability Act (WAM). Damage caused by the crane therefore falls outside the AVB. There is sometimes additional cover for the use of plant as a tool. If you work with a crane hire company, record in writing who carries which part of the risk.
If a project stands still because a lift fails without anything being broken, the loss is purely financial. Such pure financial loss falls outside the AVB, which insures property damage and injury and the consequential loss from them. If you want to cover this risk, professional indemnity insurance is needed. fines and contractual penalty clauses are not paid either. You cannot insure them.
Damage caused by intent or wilful recklessness is excluded under Article 7:952 of the Dutch Civil Code. In practice the insurer looks at the procedure followed: was there a lifting plan, had the lifting gear been inspected, was the load calculated, was the zone cordoned off? Departing from recognised rules makes the discussion about recklessness a real one. Report an incident as soon as reasonably possible (Article 7:941 of the Dutch Civil Code) and record the situation in photographs.
This is what people ask us most.
That depends on the division of roles and on the contracts. The rigger is responsible for the slinging, the calculation and the signals. The operator for the operation and the set-up of the crane. When it comes to it injured parties hold everyone involved liable and the apportionment is fought out later between the insurers. A recorded lifting plan is the most important piece of evidence in that.
Not as standard. The load is property you had in your care during the work and therefore falls under the care, custody and control clause. Some insurers offer care, custody and control cover with its own sum insured and a higher excess. If very valuable objects are involved, it is wise to discuss that in advance for each project, because the standard limit can quickly be inadequate.
If you are a subordinate, your employer is in principle liable for the loss you cause during your work on the basis of Article 6:170 of the Dutch Civil Code. You yourself can only be held liable in cases of intent or wilful recklessness. If you also work as a self-employed professional or take on jobs in your own name, you do need your own public and employers' liability insurance.
A valid AVB with a minimum sum insured per event, demonstrably valid certificates and inspected lifting and hoisting equipment. In petrochemicals and on rail and industrial sites, additional requirements are added, such as co-insurance of the client or an indemnity in the contract. Have those contract requirements set against your policy before you sign.
Only if the standstill results from covered property damage or injury. If you damage an installation and production stops as a result, that business interruption loss is consequential loss and it is usually covered. If delay arises without anything being damaged, it is pure financial loss and it falls outside the AVB.
Every situation is different. For these situations we have a separate page.
Request a quotation without obligation. We check the care, custody and control cover, the sum insured and the requirements set by your clients.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.