

Liability
- Covered while coupled
- Under the car's third-party liability cover
- Uncoupled: no longer covered
A chalet on a park is neither a house nor a caravan. That in-between character determines which policy fits, and it also determines where things go wrong when you claim.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
If the unit stands fixed on foundations, it is treated as a building and insured on rebuild value. If it is a movable static caravan, it usually runs through a caravan-type policy on list price. That classification is the first thing that has to be right. It determines the whole policy.
The park sets its own conditions. Virtually every park requires liability cover for the pitch, and many parks arrange the letting centrally. Ask for the park conditions before you take anything out. Sometimes part of it is already arranged collectively.
The winter period is when the damage happens. Frost damage from failing to drain the system or from too low a temperature is covered nowhere, and with holiday units that is the most common refusal.
We compare your holiday home insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
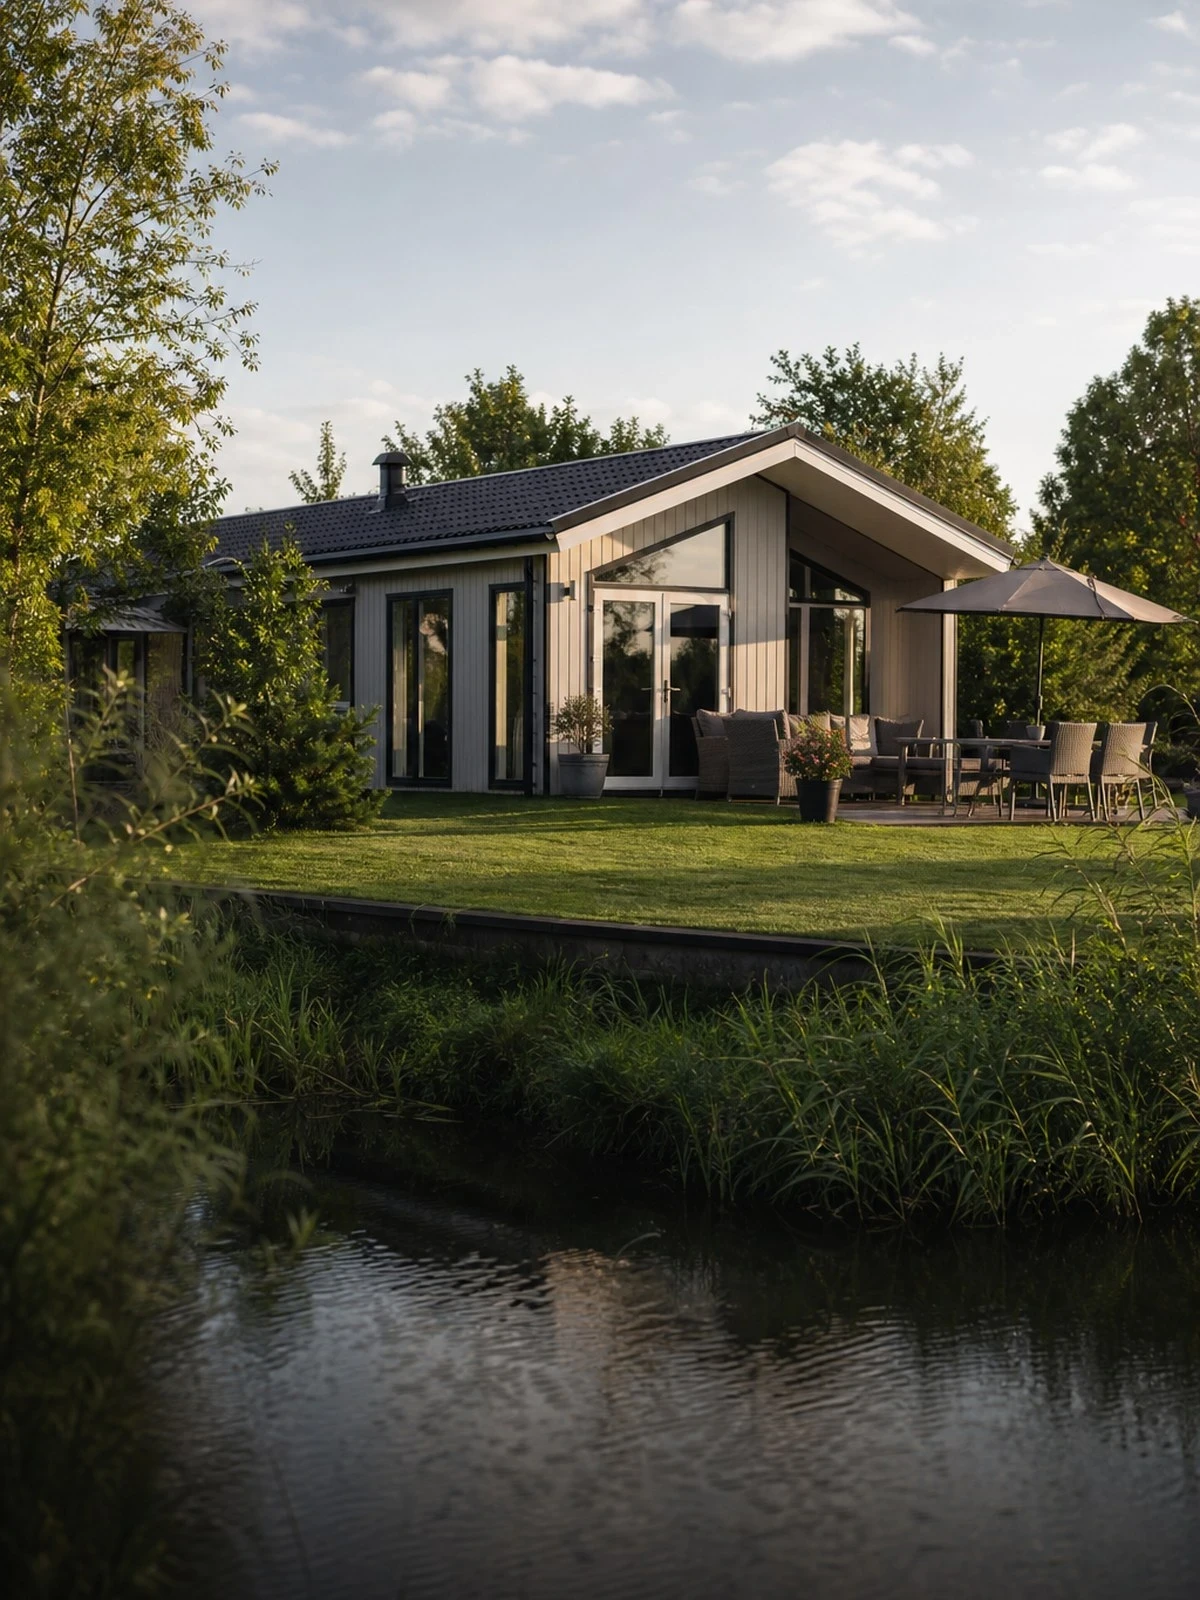 Holiday home insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the trailer.
External causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party, fire and theft | Comprehensive |
|---|---|---|
| Theft after forced entry, with the prescribed lock | Yes | Yes |
| Fire and storm damage on the pitch | Yes | Yes |
| Hail damage to roof and walls | Provided that | Yes |
| Collision damage while manoeuvring | No | Yes |
| Contents in the caravan or trailer | Provided that | Provided that |
| Damp, wear and deferred maintenance | No | No |
A trailer or caravan is not an independent motor vehicle and therefore has no insurance requirement of its own. Damage you cause to others with it falls under the third-party liability cover of the towing vehicle, as long as the combination is coupled (Article 2 WAM). Once the trailer is uncoupled and has come to a standstill, that cover no longer applies.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A chalet that stands fixed on foundations and cannot be moved without being dismantled is treated as a building. A static caravan standing on wheels or adjustable props falls under caravan-type cover on list price. If that classification does not match reality, the valuation does not either, and you only notice when the unit is a total loss.
Holiday units are intended for recreational use. If you live there permanently, even where the local authority tolerates it, the use differs from what you declared and the cover can fall away. If this applies to you, declare it; some insurers have a separate solution.
Draining the water, leaving taps open, maintaining a minimum temperature and shutting off the system: those requirements appear as a clause on virtually every policy. Frost damage caused by failing to act is not a sudden external event but the result of an omission, and is therefore paid for nowhere.
If the park arranges the letting for you, it is still commercial use. Declare it. Without a declaration, damage during the letting period falls outside the cover. Also ask what the park itself insures — sometimes liability for the pitch is already arranged collectively.
This is what people ask us most.
No. A chalet usually stands fixed on foundations and falls under a buildings-type policy. A movable static caravan is often insured as a caravan on list price. That classification determines the whole policy.
Almost always liability cover for the pitch. Ask for the park conditions. Sometimes part of it is already arranged collectively and you would otherwise be insuring twice.
Draining the water, leaving taps open and maintaining a minimum temperature. Those requirements appear as a clause on the policy; frost damage caused by failing to act is not paid for.
Only if you declare it, including where the park arranges the letting. Without a declaration, damage during the letting period is not covered.
Usually not under a holiday policy. If your use differs from what you declared, the cover can fall away; declare it if this applies to you.
With its own sum insured, often with a lower sub-limit than at home. Do not leave valuable equipment there permanently without declaring it.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.