

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
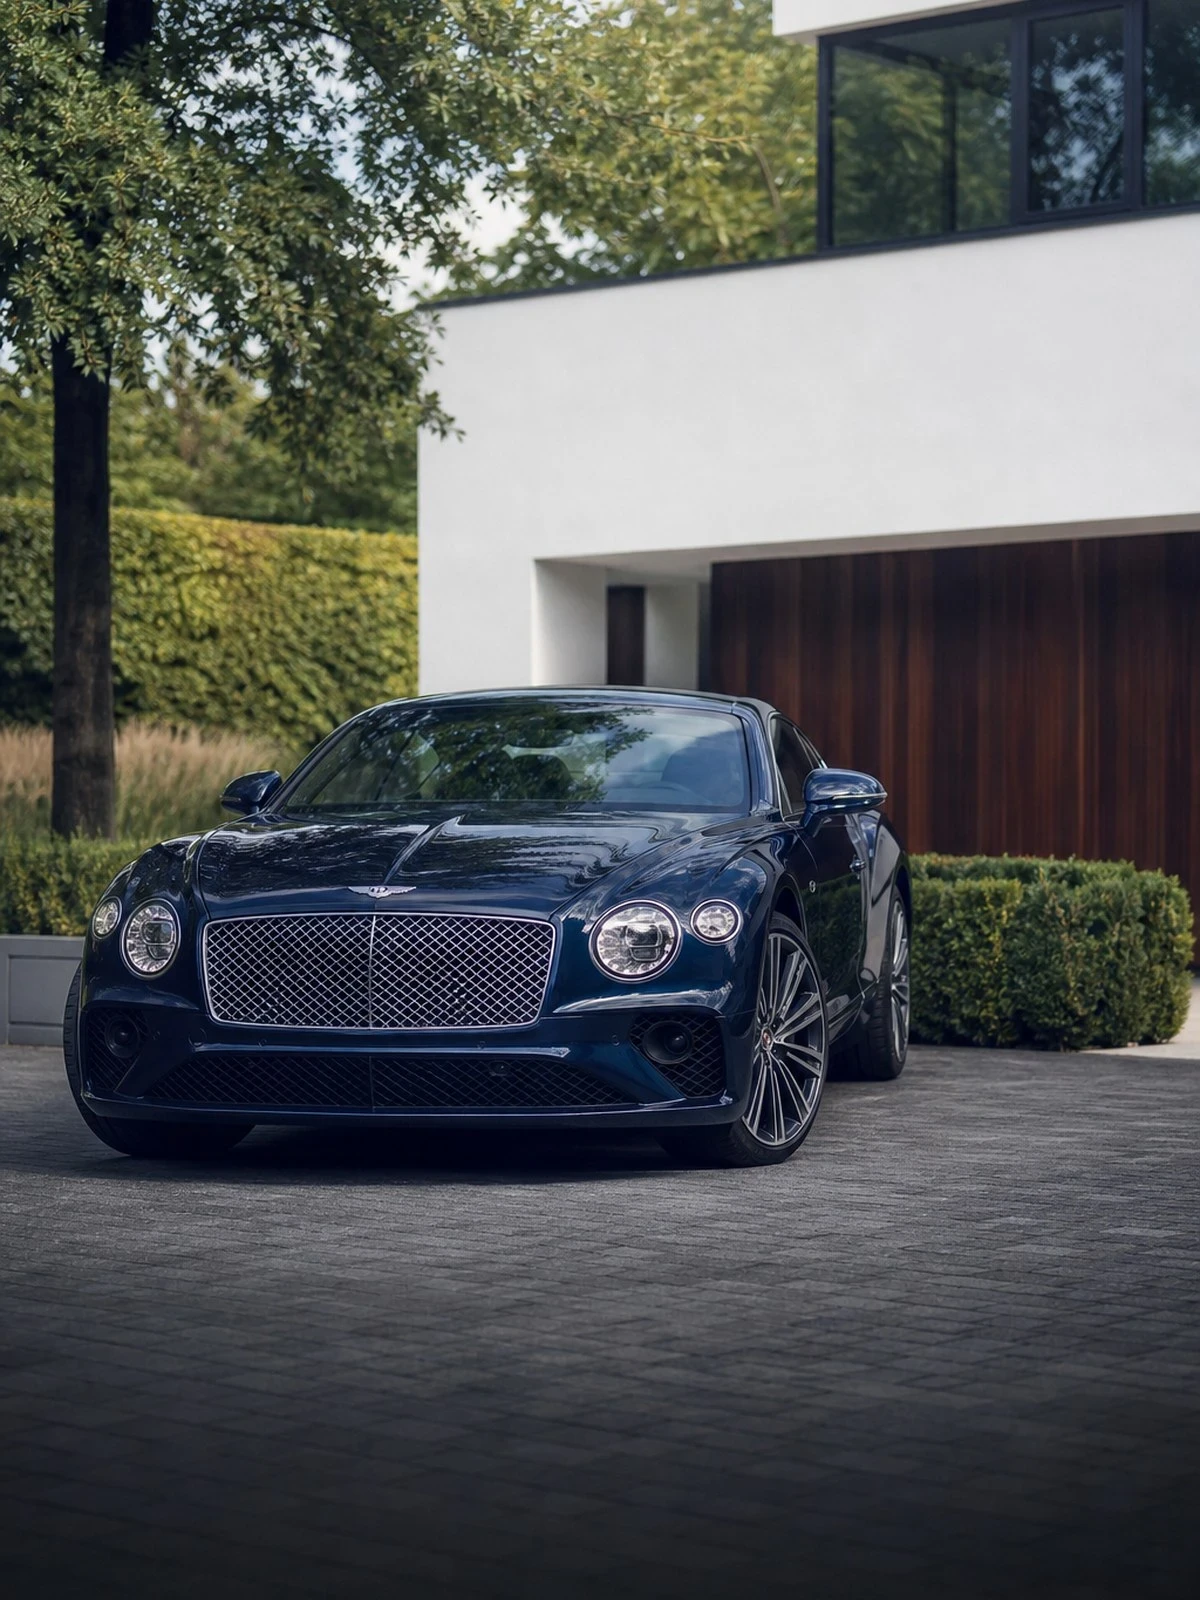
A Bentley easily weighs two and a half tonnes, and that weight shows up in the brakes, the air suspension, the tyre size and in the damage you do to someone else.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
With this make, mass is the common thread. A Continental GT, a Flying Spur and a Bentayga all carry a heavy body on air-sprung suspension with large wheels and heavy brakes. Parts that on an ordinary car are called wearing parts are structural components here: a damaged air spring, a failed air compressor or a buckled wheel is no small matter and almost always drags the rest of the suspension into the estimate.
That same weight feeds through into the liability side. The compulsory third-party liability cover under Article 2 of the Dutch Motor Insurance Liability Act (WAM) is arranged the same way on every car, but the impact energy of a heavy car is not: at this weight a rear-end collision more readily causes injury and more damage to the other party's vehicle. We therefore check whether the cover chosen really matches a car of this class.
When it comes to it the Bentayga is often used as a full family car and tow car, while a Continental or Flying Spur covers far fewer kilometres. That difference in use should be reflected in the application, as should any towbar and the trailer you tow. For establishing the value on older examples, the same consideration applies as with other car insurance in this segment: have it valued.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The air suspension system carries the full weight and is sensitive to contact with kerbs, damaged road surfaces and long periods standing still. What matters is the distinction the policy makes: an air spring that splits with age or wear is excluded, while the same air spring failing because of an external event does fall under own-damage cover. So after a loss always have the cause recorded by an assessor, because the whole assessment turns on that single point.
Large diameters with low-profile tyres are vulnerable when parking and in potholes. Damage to wheels and tyres on its own without a collision is not paid for under many policies. It is then treated not as an external mishap but as damage from use. If you run a non-standard wheel size, it should have been declared when you applied, otherwise that specification is not insured in the event of theft or damage.
Wood veneer, hand-stitched leather and inlaid panels are made to measure for each car. With water damage, a broken window with fragments of glass or fire damage in the interior, the cost item is not the part but the finish, because the colour and grain have to match the rest. Check whether the policy allows repair to factory quality and whether there is a limit on interior repair which with this kind of finish is quickly reached.
If the Bentayga is used with a trailer or caravan, declare the towbar. Damage you cause to others with the trailer falls under the third-party cover of the car for as long as it is coupled, but damage to the trailer itself does not. Damage caused by loading in the interior and damage from an incorrectly secured load are not own-damage claims either. The trailer needs cover of its own.
This is what people ask us most.
That depends entirely on the cause. Failure through wear, age or a technical fault is a mechanical defect and therefore excluded. If the system fails because of a collision, a kerb or falling material, it is an own-damage claim. So have the cause recorded by an assessor before anything is dismantled, because without that finding the exclusion wins in practice.
The insurance requirement in Article 2 of the Dutch Motor Insurance Liability Act (WAM) applies to every motor vehicle, but the extent of the damage you can do is related to mass and speed. At this weight the damage to the other party, including injury and consequential loss, mounts up more quickly. We therefore check that the sums insured for injury and property damage with the company chosen are generous enough.
Usually not. Damage to wheels and tyres on its own without further collision damage is treated by many policies as damage from use and not as an external mishap. Where there is collision damage to the bodywork, the wheel is often included in the same estimate. Ask about this point in advance, because the wording varies between insurers here.
Only for the damage you cause to others with it while the trailer is coupled to the car. That falls under the third-party cover of the towing vehicle. The trailer or caravan itself is not covered, and neither is the load. Separate insurance is needed for that. Declare the towbar when you apply, even if you only tow a few times a year.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.