

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
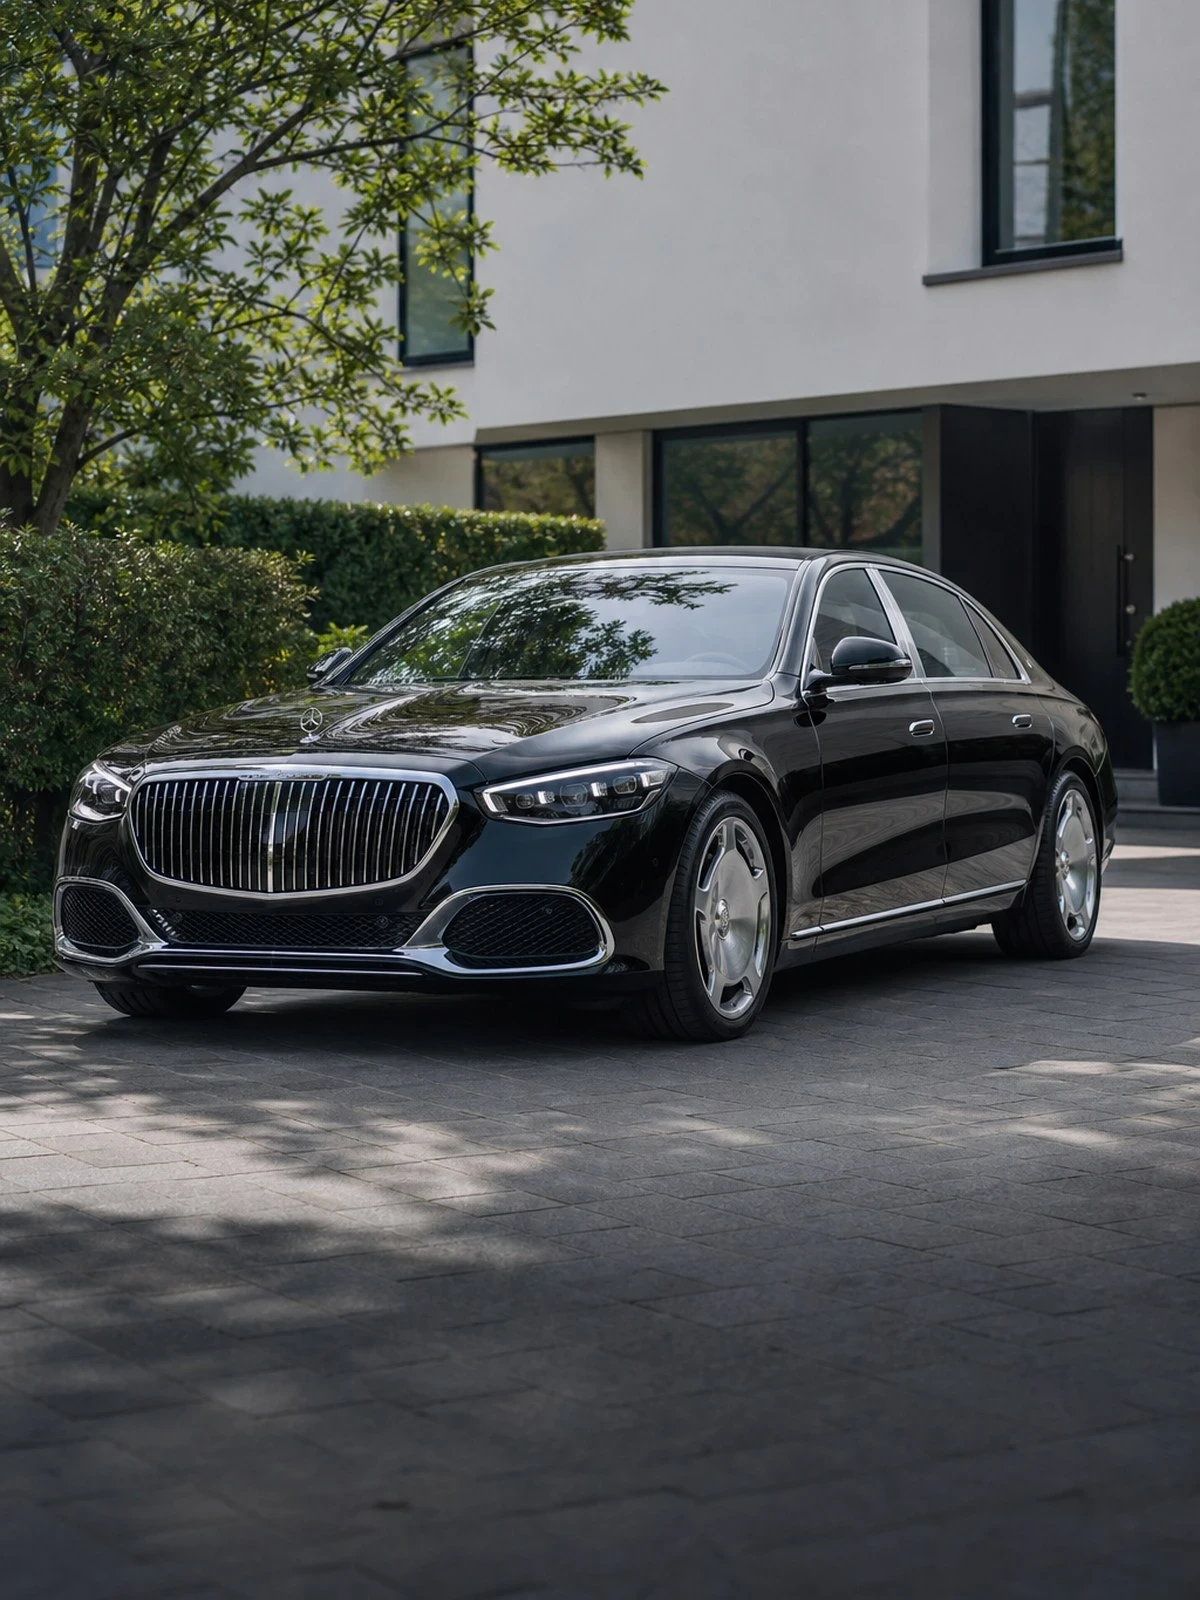
A Maybach is often driven not by the owner but by a chauffeur, and that shifts the policy questions from the car to the people in it.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
These cars are usually registered to a business and used for representation: collecting clients and guests, carrying directors, being present at events. The most important passengers sit in the back. That shifts the emphasis of the insurance to three points: who counts as the regular driver, how the occupants are covered, and whether the use still falls within the definition of private or business transport.
The compulsory third-party liability cover under Article 2 of the Dutch Motor Insurance Liability Act (WAM) pays for other people's losses, including those of your own passengers. What it does not pay for is injury to the driver themselves where they are at fault. If your chauffeur is an employee, that also affects your employer's liability: under Article 7:611 of the Dutch Civil Code you have to make proper provision for employees who take part in traffic in the course of their work.
If the car with a chauffeur is made available for payment, that is no longer private use but the carriage of passengers. That is excluded under an ordinary car policy and calls for a separate form of cover. When you apply, we check which of these situations applies to you before we place the car insurance.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Insurers rate on whoever drives the vehicle most, not on the registered keeper. If your chauffeur covers the great majority of the mileage, they belong on the policy as the main driver. If someone else is named, the declaration is incorrect and the insurer can rely on Article 7:928 of the Dutch Civil Codewhen you claim. If the chauffeur changes, report it. It is not an administrative formality but the basis of the premium.
Passengers are protected through the third-party cover where your driver is at fault. If something happens without any identifiable fault on your side, or your own chauffeur is at fault and is injured, third-party cover offers no answer. An occupants' accident insurance pays regardless of fault and covers the driver as well. On a car used primarily for carrying people within the business, that is not a luxury but the heart of the risk.
As soon as there is a payment for the journey, the nature of the use changes. Hire with a chauffeur, ceremonial transport and carrying guests for payment are excluded under an ordinary car policy, even where you do it occasionally and the payment is small. That really is investigated after a claim. If you do this regularly, cover for the professional carriage of passengers is needed, with the licensing requirements that go with it.
With valet parking you hand the car and the key over voluntarily to a third party. If the car then disappears, in law that is not theft but misappropriation or fraud, and that is separately excluded under many policies. Ask whether your insurer covers this situation. If not, park the car yourself or place liability in writing with the party accepting the key.
This is what people ask us most.
The chauffeur, because the insurer rates on whoever drives the vehicle most. If you name someone else, the declaration is incorrect and the insurer can rely on Article 7:928 of the Dutch Civil Code when you claim and reduce the payout. If you change chauffeur, report it straight away. With several chauffeurs we ask for a group of drivers rather than a fixed name.
For injury for which your driver is liable, the third-party cover pays. Where that liability is absent, for example in a single-vehicle accident with no fault, nothing is left without additional cover. Occupants' indemnity insurance pays regardless of fault and covers your chauffeur as well. On a car used to carry guests, that is the part that really matters.
Not on an ordinary policy. As soon as there is a payment, it is the carriage of passengers for payment and that is excluded, including for occasional use and a modest amount. After a claim this is investigated through diaries, invoices and statements. If you do this more often, have cover for the professional carriage of passengers arranged and bear the licensing requirements in mind.
In law usually not. You handed the car and the key over voluntarily, so it is misappropriation or fraud, and those are separately excluded from theft cover under many policies. Check before you take out the policy whether your insurer includes this situation. If it does not, park the car yourself or have the party accepting the key accept liability in writing.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.