

Liability insurance for a coffee bar
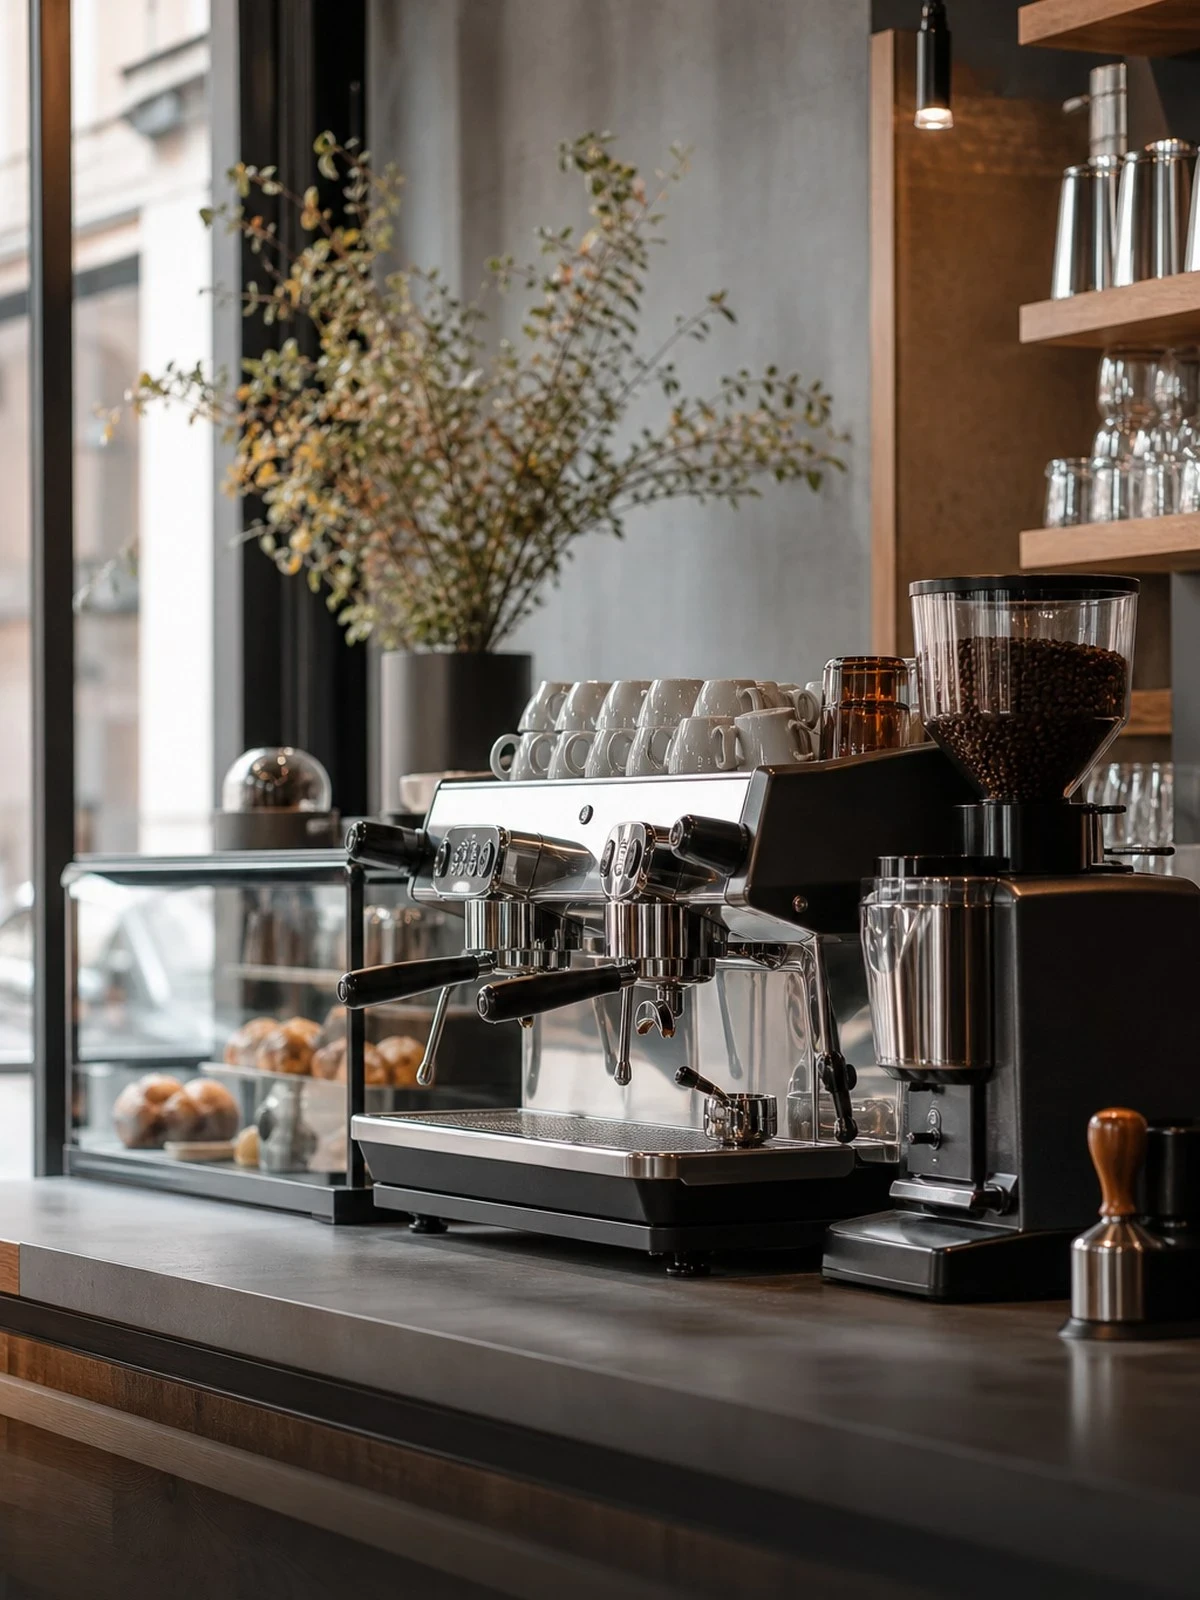
In a coffee bar the most dangerous appliance stands at eye level on the counter, with water and steam above a hundred degrees an arm's length from guests and staff.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
The most common injury in a coffee shop is a burn: a steam wand that slips, a jug of milk above sixty degrees, a portafilter coming loose under pressure because the gasket is worn. If a guest is injured, it turns on the standard of care under Article 6:162 of the Dutch Civil Code. If your barista is injured, Article 7:658 of the Dutch Civil Code applies and you must show that there was instruction, maintenance and supervision. The boiler of an espresso machine is under pressure and is subject to maintenance and inspection requirements; its log is the first thing requested when a claim comes in.
The second risk is outside. Terrace furniture blowing away, a parasol overturning, a patio heater, an A-board on the pavement and the canopy on the facade. For a defect in the building or in what is fixed to it, Article 6:174 of the Dutch Civil Codeapplies: the possessor is liable without needing to be at fault. If you rent the premises, have the tenant's liability section included, because fire and water damage to the premises rented is not covered as standard.
What stays outside this policy: your own machine, furniture and stock, which belong on business contents insurance; the loss of turnover if you have to close, for which there is business interruption insurance; the cost of recalling a batch of beans or cakes you sold under your own name; and fines from a regulator. For disputes with a landlord or supplier, look at legal expenses.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four subjects that lead to claims in a coffee shop more often than you would think.
The machine as an appliance under pressure
An espresso machine works with a heated boiler and pressure lines. If a gasket or a safety valve wears out, a portafilter shooting free or a blast of steam is not a theoretical risk. Keep a maintenance log with dates, engineer and parts replaced, and have descaling and the periodic check done by a professional. Without those records your defence to an injury claim is thin.
Milk, plant-based alternatives and allergens
With oat, soya, almond and coconut side by side on the bar, a mix-up is easily made, and with a nut or soya allergy that is an injury straight away. Work with separate jugs, a fixed colour coding and a written allergen list for everything you serve, including syrups and biscuits. That is also what the insurer asks about when a claim comes in.
Terrace, displays and facade
Furniture blowing away and parasols falling over produce both injury and damage to parked cars. Set out a wind protocol: at what wind strength parasols are closed and loose furniture is brought in. Check canopies, planters and lighting on the facade periodically, because you carry strict liability for them as the possessor.
Coffee carts, delivery and catering
If you also work a mobile bar at a trade fair or festival, or deliver by cargo bike, that is an extension of your activities. Work away from your fixed address must be in the description of business activity; otherwise damage on location falls outside cover. Report that extension, because Article 7:928 of the Dutch Civil Code requires you to declare relevant circumstances.
What does your premium depend on?
- Annual turnover: the usual basis for the premium
- Payroll and number of employees: determines the weight of the employers' liability section
- Terrace or not: and the number of seats outside
- Own kitchen or serving only: preparing food yourself increases the food safety risk
- Activities away from the premises: coffee cart, catering or delivery
- Sales under your own brand: your own beans or cakes engage product liability
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | Basic | Extended |
|---|---|---|
| A guest is scalded by hot coffee when a tray tips while being served | Yes | Yes |
| A visitor slips on the wet floor by the toilets and breaks a wrist | Yes | Yes |
| A barista cuts himself on the blades of the ice machine while cleaning it | Yes | Yes |
| You knock over a jug of milk onto the laptop a customer had put on the bar | Provided that | Yes |
| Your own espresso machine is damaged beyond repair by a power surge | No | No |
| A company demands the cost of a meeting back because the lunch ordered was not delivered | No | No |
Extended means a policy on which care, custody and control and tenants' liability are included. Your own equipment and loss of turnover belong on other policies.
Frequently asked questions
This is what people ask us most.
An employee suffers a burn while frothing milk.
That falls under the employers' liability section, provided it is included. The insurer assesses your duty of care under Article 7:658 of the Dutch Civil Code: was this employee instructed about the steam wand, was the machine properly maintained, was there supervision during the induction period? Record induction sessions for each person and report the loss in good time, as Article 7:941 DCC requires.
A guest has an allergic reaction to the wrong milk.
Injury from a mix-up is covered in principle, because a mistake was made in preparation. The question is whether you could reasonably have known that an allergy was involved and whether your working method prevents mix-ups. If you provide information about allergens, do so in writing and keep it up to date; verbal assurances at the bar cannot be proved afterwards.
Our machine fails and we are closed for a week.
That is not liability but your own loss. Repairing or replacing the appliance belongs on business contents insurance and the lost profit on business interruption insurance. Only if a third party caused the breakdown, an engineer for instance, can you hold that party liable. Your own liability policy plays no part in this case.
Our parasol blows onto a parked car.
That is property damage to a third party and insured in principle. The insurer does look at your precautions: was a strong wind forecast, was the parasol properly anchored, was there a protocol for bringing it in at a certain wind strength? Without demonstrable measures an insurer can rely on the prevention conditions in the policy.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a caféInjury to guests, terrace, alcohol
- Liability insurance for a baristaHot water, someone else's counter, allergens
- Liability insurance for a hospitality businessKitchen staff, injury to guests, premises
- Liability insurance for a restaurantAllergens, extraction, guests' belongings
- Liability insurance for a café ownerCellar and bar, casual workers, excess
- Liability insurance for a self-employed restaurant ownerSmall business, stand-in staff, tenant's interest
- Liability insurance for a shopThe public in the shop, shopfront, goods sold
- Liability insurance for a travel agencyPublic area, staff, package travel