

Third-party liability
- Damage to other cars and injury
- No cover for your own S1
- Compulsory under Article 2 of the Dutch Motor Insurance Liability Act (WAM)
- Suitable where the market value is low
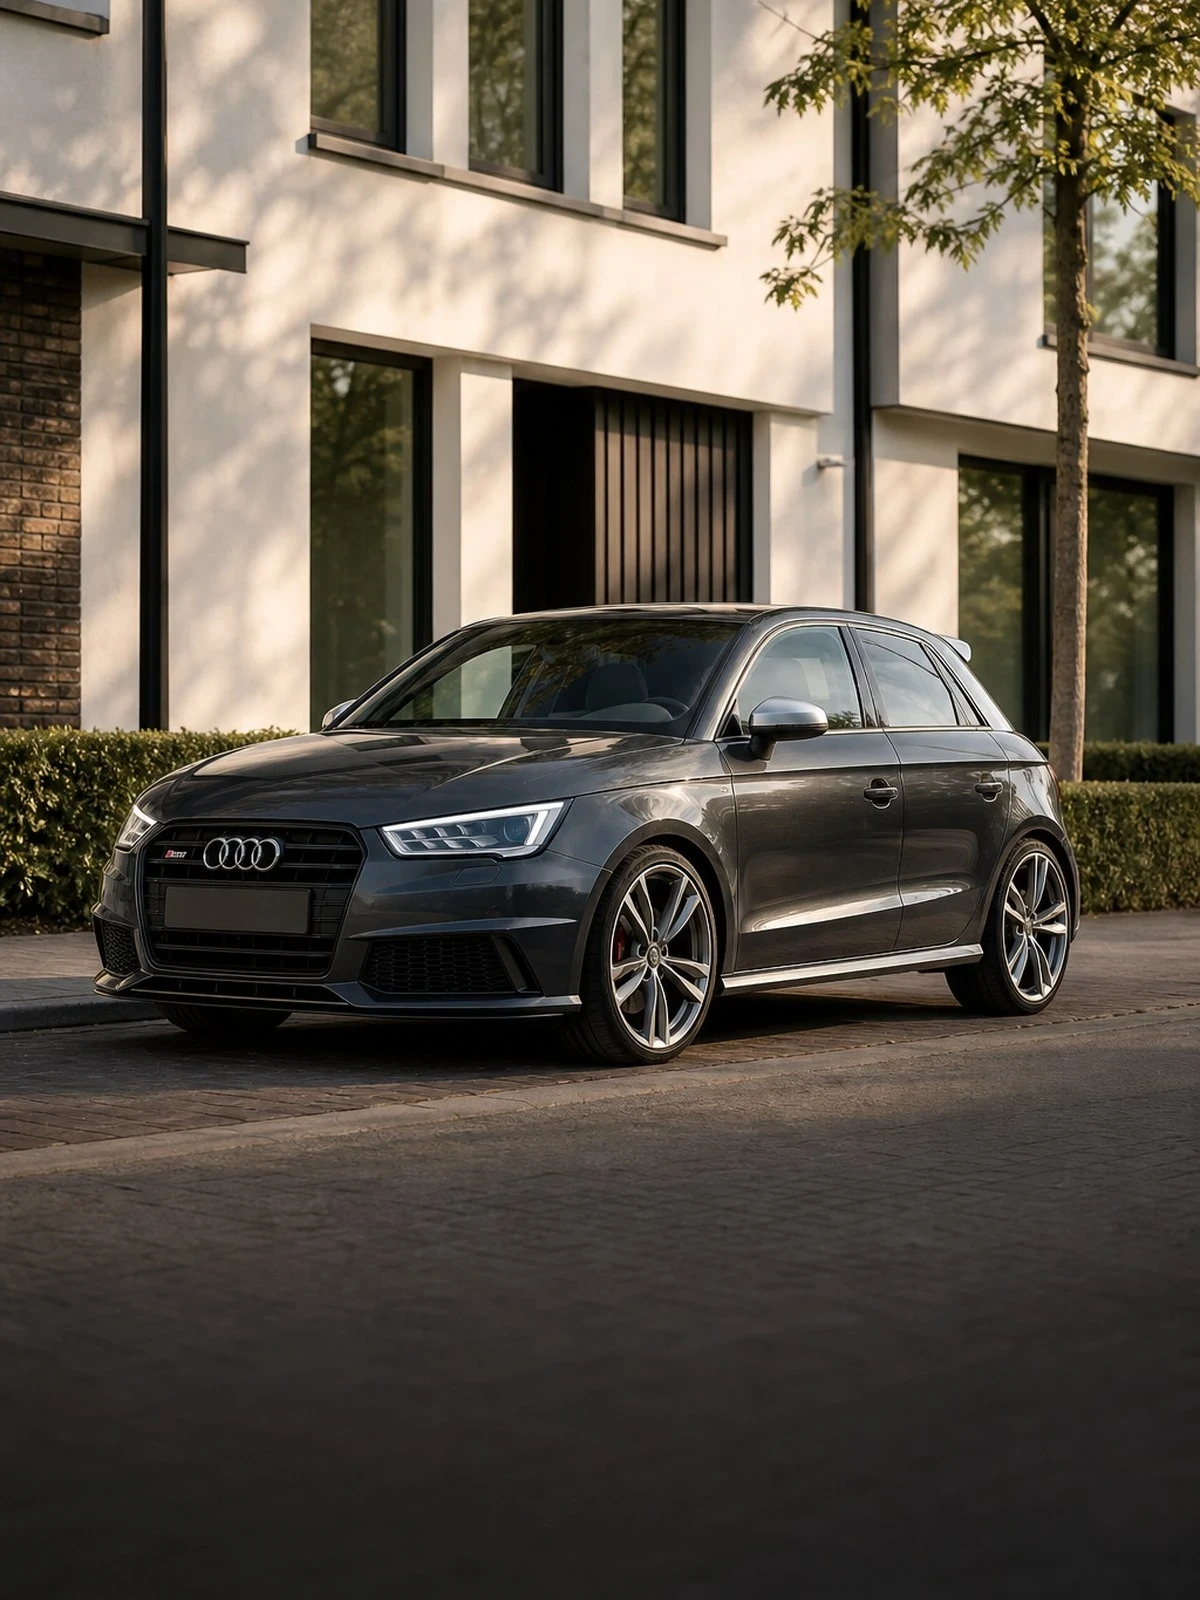
The S1 is the fastest version of the A1: a 2.0 TFSI with quattro in a small body. That ratio between power and weight determines the rating group.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
To an insurer the S1 is not a small car but a compact car with a lot of power. Rating groups are based on list price, weight and power. The last two work out unfavourably on this model compared with the standard A1 versions. On top of that comes the model's claims record: small, fast cars have on average more and heavier claims than their size suggests.
Third-party liability cover is required by law under Article 2 of the Dutch Motor Insurance Liability Act (WAM) and pays only for damage you cause to someone else. Damage to the S1 itself falls under own-damage cover. Because most examples are now several years old, the choice between third-party, fire and theft and comprehensive cover is a real one here: what decides it is the market value and whether you could bear a single-vehicle loss yourself, not the age of the car.
Two points count for extra on this model. First, the regular driver: with a young driver the premium rises steeply and some insurers set a minimum age. Second, departures from the factory specification. This is a model that is often modified, and that is precisely where things go wrong when you claim. Report every modification in advance and have acceptance confirmed in writing.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
Three types of cover, with below them the situations that come up most often with this car.
The legally required cover for damage you cause to others.
As well as third-party liability, a fixed list of events: theft, glass, fire, storm and collision with animals.
Also damage to your own car caused by you or without a third party involved.
What is covered
| Situation | Third-party liability | Comprehensive |
|---|---|---|
| Damage you cause to someone else with the S1 | Yes | Yes |
| Theft of the car or of parts | No | Yes |
| Windscreen, storm and hail damage | No | Yes |
| Damage to your own car after a single-vehicle accident | No | Yes |
| Damage to a declared increase in power | No | Provided that |
| Damage during a track day or speed run | No | No |
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that arise more often on this model than on a standard A1.
Insurers look not at the size but at the ratio between power and weight. A short car with a 2.0 TFSI and quattro therefore falls into a different class from the standard A1 versions, even where it barely differs from them on the outside. So always ask for the premium registration number and exact version; an application made for an 'A1' produces a premium that will not hold up when you claim.
With fast compact cars, insurers look closely at who drives them. A young or inexperienced main driver leads to a considerably higher premium, a higher excess or a refusal. So put the actual driver on the policy. If the car is registered to a parent while a child drives it regularly, that is an incorrect declaration which the insurer can hold against you when you claim, under Article 7:928 of the Dutch Civil Code.
The following, among others, are outside the cover: taking part in speed or skill trials and driving on a track, even on a touring run; wear and tear and mechanical or electronic defects without a collision, such as a failed clutch, turbo or transmission; damage while driving without a valid driving licence or under the influence; and damage to undeclared modifications. Damage to wheels and tyres on its own is only paid for where it follows from a covered event, and damage caused by intent or recklessness is excluded under Article 7:952 of the Dutch Civil Code.
Chip tuning, a sports exhaust, a different intercooler, lowering springs or non-factory wheels alter the risk and sometimes acceptance. Report them before the modification: a breach of the duty of disclosure can reduce the payout or cause it to lapse (Article 7:930 of the Dutch Civil Code), and where an increase in power is found that is a real outcome. Insurers that accept tuning do so for an additional premium and record the modified specification on the policy schedule. You report a claim as soon as reasonably possible (Article 7:941 of the Dutch Civil Code).
This is what people ask us most.
Usually clearly more expensive. The list price is higher and the power in relation to the weight is considerably greater, which puts the car in a higher rating group. With a young driver the difference grows further. How much it comes to varies a great deal between insurers, because not everyone rates this segment as sharply.
Declare that person as the main driver. The premium goes up as a result, but the cover is correct. If it turns out after a claim that the actual driver was consistently someone other than the person declared, the insurer can reduce or refuse the payout and cancel the policy. Some insurers only accept a young driver with a higher excess.
That depends on the market value and your reserves, not on the age. As long as you would not want to bear a single-vehicle loss or a total loss yourself, own-damage cover remains worthwhile. Where the market value is low and the difference in premium high, third-party, fire and theft may make more sense. Review this each year against the current value.
Report it even so, late though it is. Some insurers accept the modification for an additional premium; others cancel the policy, after which you have to apply again elsewhere. Waiting is the worst option: when you claim, an increase in power that can be read out can lead to the whole payout being refused.
No. Driving on a circuit falls outside practically every car policy, even where it is a leisure session and no times are taken. If you do want to take the car onto a circuit, separate temporary cover is needed. Do not assume it is included without written confirmation from the insurer.
Declare that when you apply. On an imported example the specification and the original list price sometimes differ from the Dutch reference, which has consequences for the premium and for how the value is established when you claim. Make sure the details on the registration document and the policy schedule match.
Every situation is different. For these situations we have a separate page.
Request a quote by registration number without obligation. We compare premium and conditions, including any modifications.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.