

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
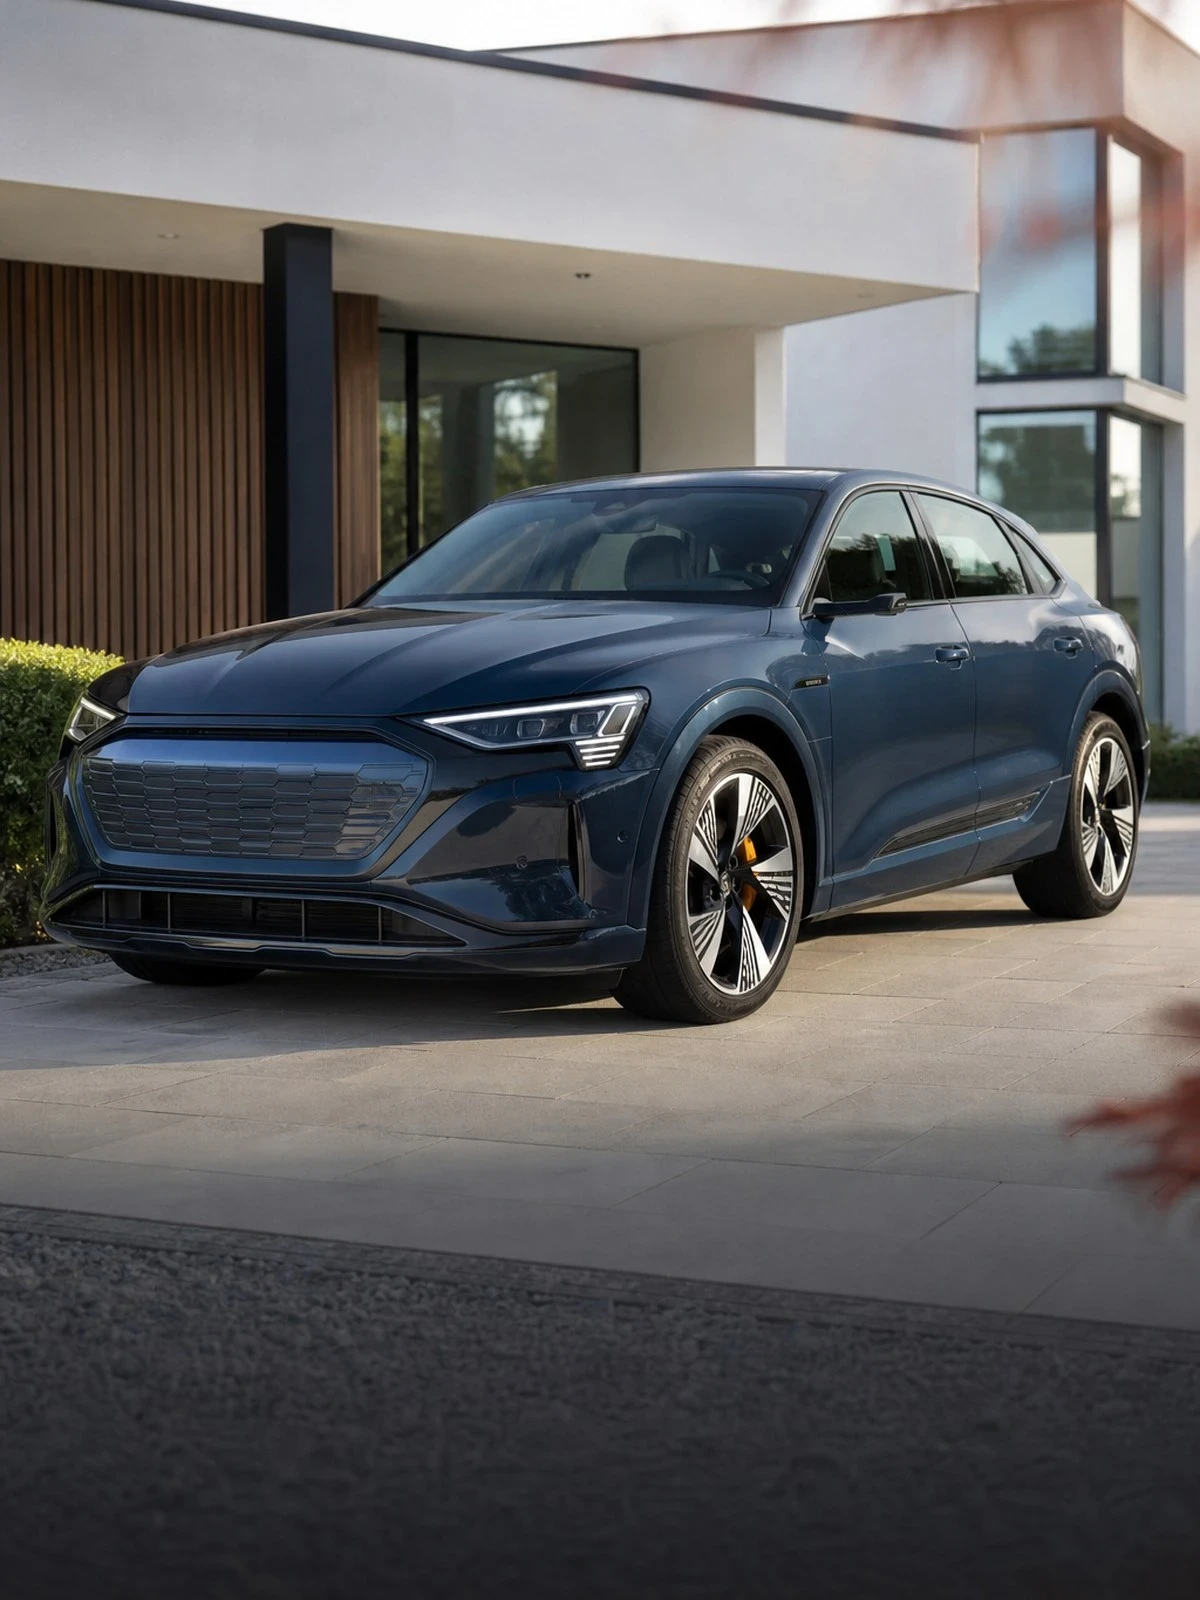
The Audi e-tron is a heavy SUV with aluminium body panels and air suspension, and that is precisely what determines who may repair it and how quickly a claim mounts up.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The e-tron sits in the large SUV class: a high kerb weight, drive on both axles and a battery pack that lies in the floor across virtually the whole wheelbase. That weight feeds through into the damage you cause to someone else in a collision, and that part always runs through the compulsory third-party cover (Article 2 WAM). For the car itself the risk sits low down: under the floor.
Repair on this model is not run-of-the-mill bodywork. Aluminium panels, air suspension and a high-voltage system call for a firm with the right equipment and authorisation. So check in the conditions whether you keep free choice of repairer or whether the insurer steers you to its own network, and what excess applies if you have the repair done outside it.
Do you drive the more compact version on the same platform as the mainstream family models? Then read Audi Q4 e-tron car insurance; there it is more about where you charge and the charging cable than about weight and the repair chain.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A loaded e-tron weighs considerably more than a comparable petrol SUV. In a shunt that translates into heavier damage to the other party, and that side runs through your compulsory third-party cover (Article 2 WAM). Your braking distance is longer on a wet road and with a trailer behind. Accelerated tyre and brake wear resulting from that weight is never insured: wear and mechanical defects fall outside every own-damage cover.
The battery pack lies in the floor, behind a protective plate you cannot assess from the driver's seat. A bollard, a high kerb or a loose object can dent that plate without leaving a single scratch on the bodywork. Because the safety of the pack cannot then be confirmed without investigation, a thorough inspection often follows. Always report such an incident: Article 7:941 of the Dutch Civil Code requires you to report the loss as soon as you become aware of it.
Not every bodyshop may weld aluminium and de-energise the high-voltage system. That limits your choice and lengthens the time it takes, certainly where a part has to come from abroad. A replacement vehicle is not an automatic part of own-damage cover; where it is included, a maximum period almost always applies. Loss of use or business interruption during the repair is not paid for, even if you need the car for work.
Many e-trons are driven for business or under a lease contract. Declare that use when you apply: an incorrect declaration touches on the duty of disclosure under Article 7:928 of the Dutch Civil Code and can lead to a reduced or refused payout when you claim (Article 7:930 DCC). If you tow a trailer, it is covered for third-party liability while coupled, but damage to the trailer itself and to the load is not. Tools and goods in the car are likewise not covered by car insurance.
This is what people ask us most.
That depends on the policy. Some insurers work with their own repair network and increase the excess if you have the repair done outside it; others leave you entirely free. Because aluminium and the high-voltage system call for specialist authorisation, the number of suitable firms is limited in any case. Ask in advance which arrangement applies and what then happens with a replacement vehicle.
Under comprehensive cover, sudden damage from an external cause to the underbody protection is covered, including the investigation needed to clear the battery pack. Corrosion, the gradual effect of road salt and loss of battery capacity are not: that is wear. Third-party, fire and theft does not cover this damage at all, because there is no fire, theft, storm or glass involved.
On a covered claim where repair costs more than the value, the insurer pays the value. A purchase price or replacement value as new rule applies only for a limited period and differs widely from insurer to insurer. After that the market value applies. If finance or a lease contract is still running, a residual debt may remain that the car insurance does not cover.
Yes. How the car is used is one of the details you are asked about when you apply, and the duty of disclosure under Article 7:928 of the Dutch Civil Code applies to it. If it turns out after a claim that the car was regularly driven for business or by others than declared, the insurer may adjust or refuse the payout under Article 7:930 DCC. So report changes as they happen.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.