

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
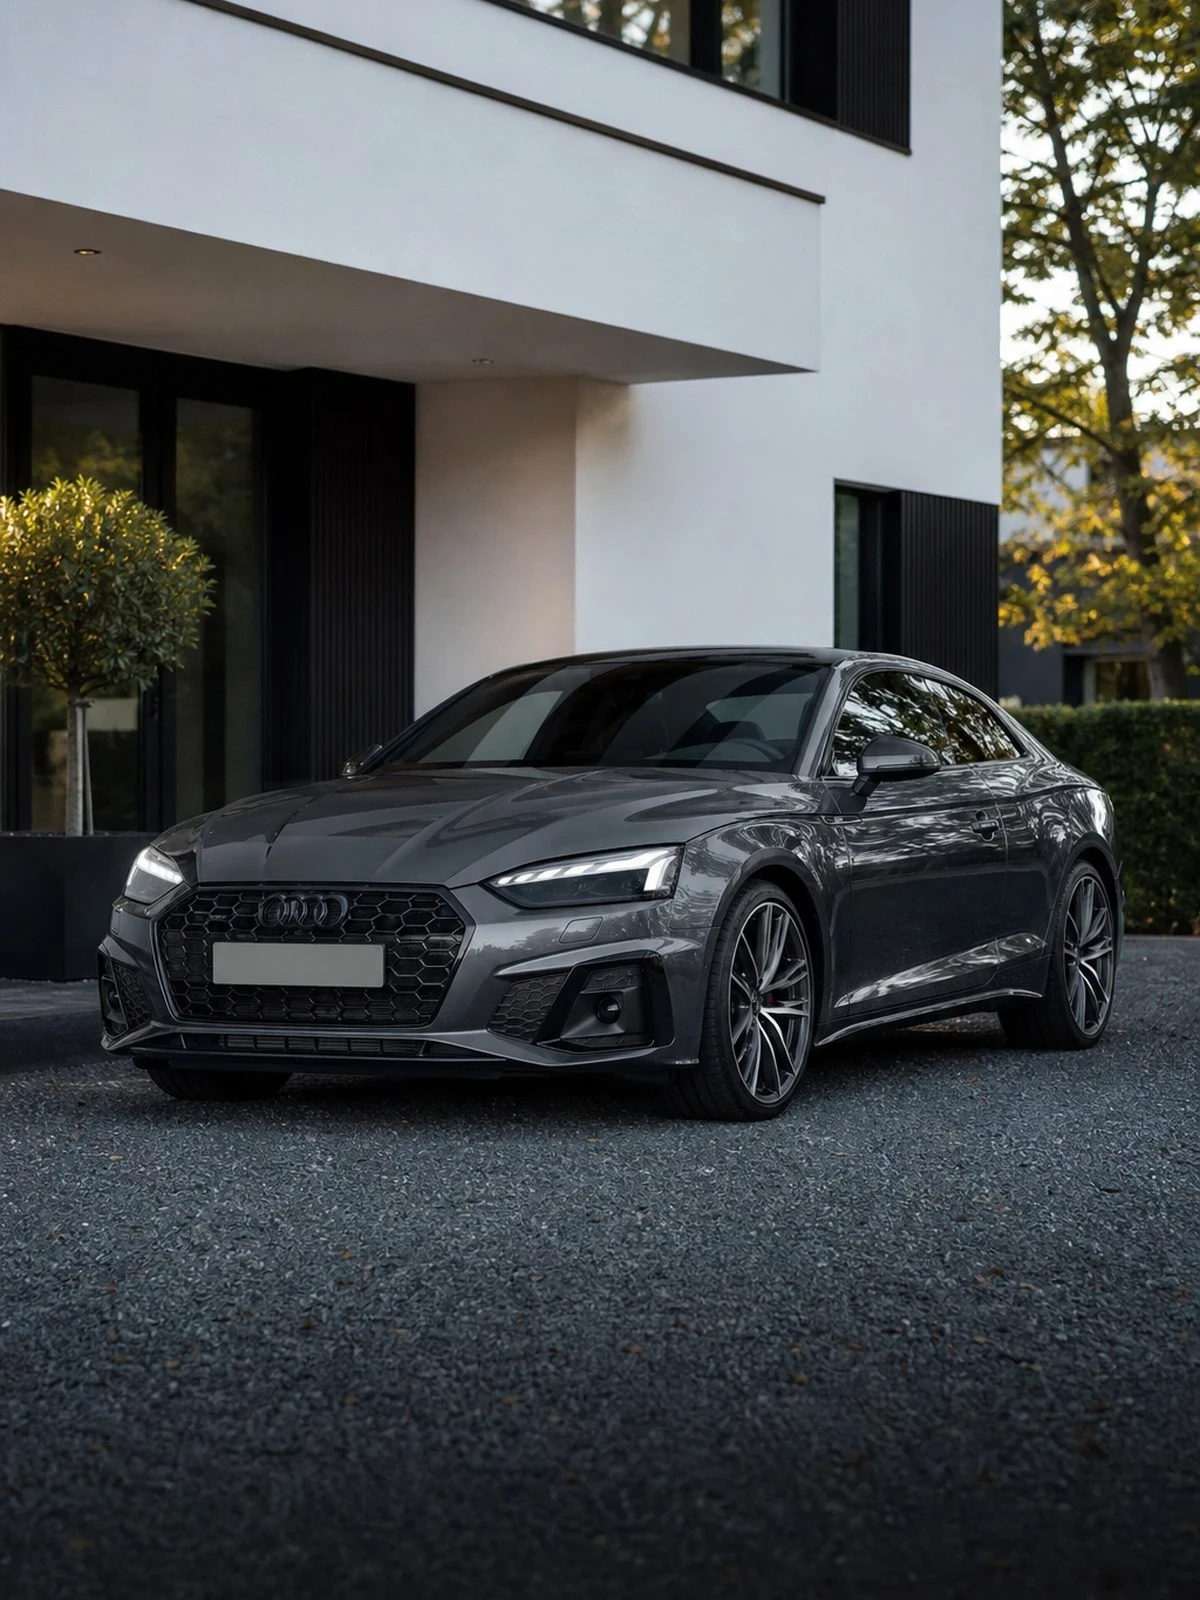
The A5 is the body-style variant of the range: coupé, Sportback and above all Cabriolet, and it is that fabric roof that places demands on the cover and on where the car is kept.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
What sets the A5 apart from the saloons in the same class is not the engineering but the body. On the cabriolet, between the occupants and the street sits a fabric hood with an electric or hydraulic operating mechanism. That has two consequences for the insurance: the car is more vulnerable to vandalism and break-ins, and the roof mechanism is an expensive component that, if it fails, is rarely covered by the policy.
On top of that, many examples are kept as a second car and used mainly in the summer half of the year. A low annual mileage works in your favour on the premium, but only if it matches reality and the storage you declare. If you want to leave the car unused for part of the year, suspending the registration is an option: provided the car is off the public road.
The larger body panels and the big wheel sizes make bodywork repairs more involved than on a compact car. Whether that weighs heavily for you depends on the type of cover you choose. On our page about comprehensive cover you can read what the difference means in practice.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A slashed hood is common in attempted break-ins and vandalism. Replacing the fabric is expensive and there is only cover under comprehensive; under third-party, fire and theft, vandalism is usually outside the cover. Note the break-in situation too: if there is no forced entry to the locks but there is a cut in the fabric, that must be recorded as damage. Always report it to the police and photograph the cut before you have the car closed up.
If the hood sticks halfway because of a failed pump, a broken hinge or a worn seal, that is a mechanical defect. Every car policy excludes wear and defects. This belongs with maintenance or the warranty, not with the insurance. If an insured event damages the mechanism, for example in a collision, the repair is covered by own-damage cover. That distinction determines who pays the bill.
Hail damage to the bodywork is usually covered under both third-party, fire and theft and comprehensive. Rainwater running in because the hood was open is not: there is then no external cause but a lack of care. Leaks through an aged or split seal likewise count as wear. If you park outside, take the weather forecast into account. That responsibility rests expressly with you.
Outside the cover are: wear to the hood, seals and mechanism, theft while the keys were in or near the car, taking part in speed or club runs on a circuit, and hire or use through a car-sharing platform. If the registration is suspended but the car is nevertheless parked on a public road, there is no third-party cover while it is in fact compulsory under Article 2 of the Dutch Motor Insurance Liability Act (WAM).
This is what people ask us most.
Damage from an external cause, such as vandalism, hail or a collision, is covered under comprehensive. Under third-party, fire and theft, vandalism is usually excluded. Wear to the fabric, discoloration, leaking seams and a faulty operating mechanism are never covered by the policy; that is maintenance. Have the hood checked periodically, because a demonstrably neglected hood leads to argument when you claim.
On a cabriolet that happens: the thief cuts the fabric rather than forcing a lock. Photograph the cut and mention it expressly in the police report, so that it is established that unlawful entry was gained. Without any trace of forced entry or damage, theft from the car is almost always refused. The damage to the hood itself is covered by own-damage cover.
Yes, if you do not use the car during those months and it is off the public road. Once the registration is suspended with the RDW, the duty to insure under Article 2 of the Dutch Motor Insurance Liability Act (WAM) falls away and you can let the third-party cover lapse. Do keep own-damage cover if the car is in a garage, because fire and theft remain possible. If you nevertheless park it in the street, you are committing an offence and are uninsured.
On theft of the complete wheels, usually yes under comprehensive cover, provided there are signs that they were removed. Rim damage from a kerb or a pothole, by contrast, falls outside the cover on many policies or under a separate provision, because it is regarded as ordinary use. Ask about this expressly if your car sits on large wheels with low-profile tyres.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.