

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to buildings and objects
- Damage caused by passengers
Insure your youngtimer — a car of 15 to 25 years old — at a good price and, if you wish, at an agreed valued amount. We compare more than 30 Dutch insurers to find the sharpest premium with the right cover. Independent advice from Finass Verzekert — AFM-registered and registered with Kifid.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Youngtimer insurance is car insurance for a car of roughly 15 to 25 years old — the bridge between a modern car and a classic. As with any car, third-party liability cover is compulsory by law. What makes a youngtimer attractive is that you can often insure it at an agreed valued amount, so that you avoid the rapid write-down to market value that affects older cars.
At Finass Verzekert we compare more than 30 Dutch insurers to find the best-priced premium with the right cover for your youngtimer. Because a youngtimer is often used carefully and has a limited market value, the premium generally works out favourably — although it is usually just a little higher than for a genuine classic car.
A youngtimer is 15 to 25 years old, a classic car 25 years or older. You may generally drive a youngtimer daily, whereas stricter conditions of use often apply to a classic car. You still pay ordinary road tax on a youngtimer. The exemption only applies from 40 years. For business drivers, the favourable benefit-in-kind arrangement for youngtimers is also a well-known reason to drive one.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
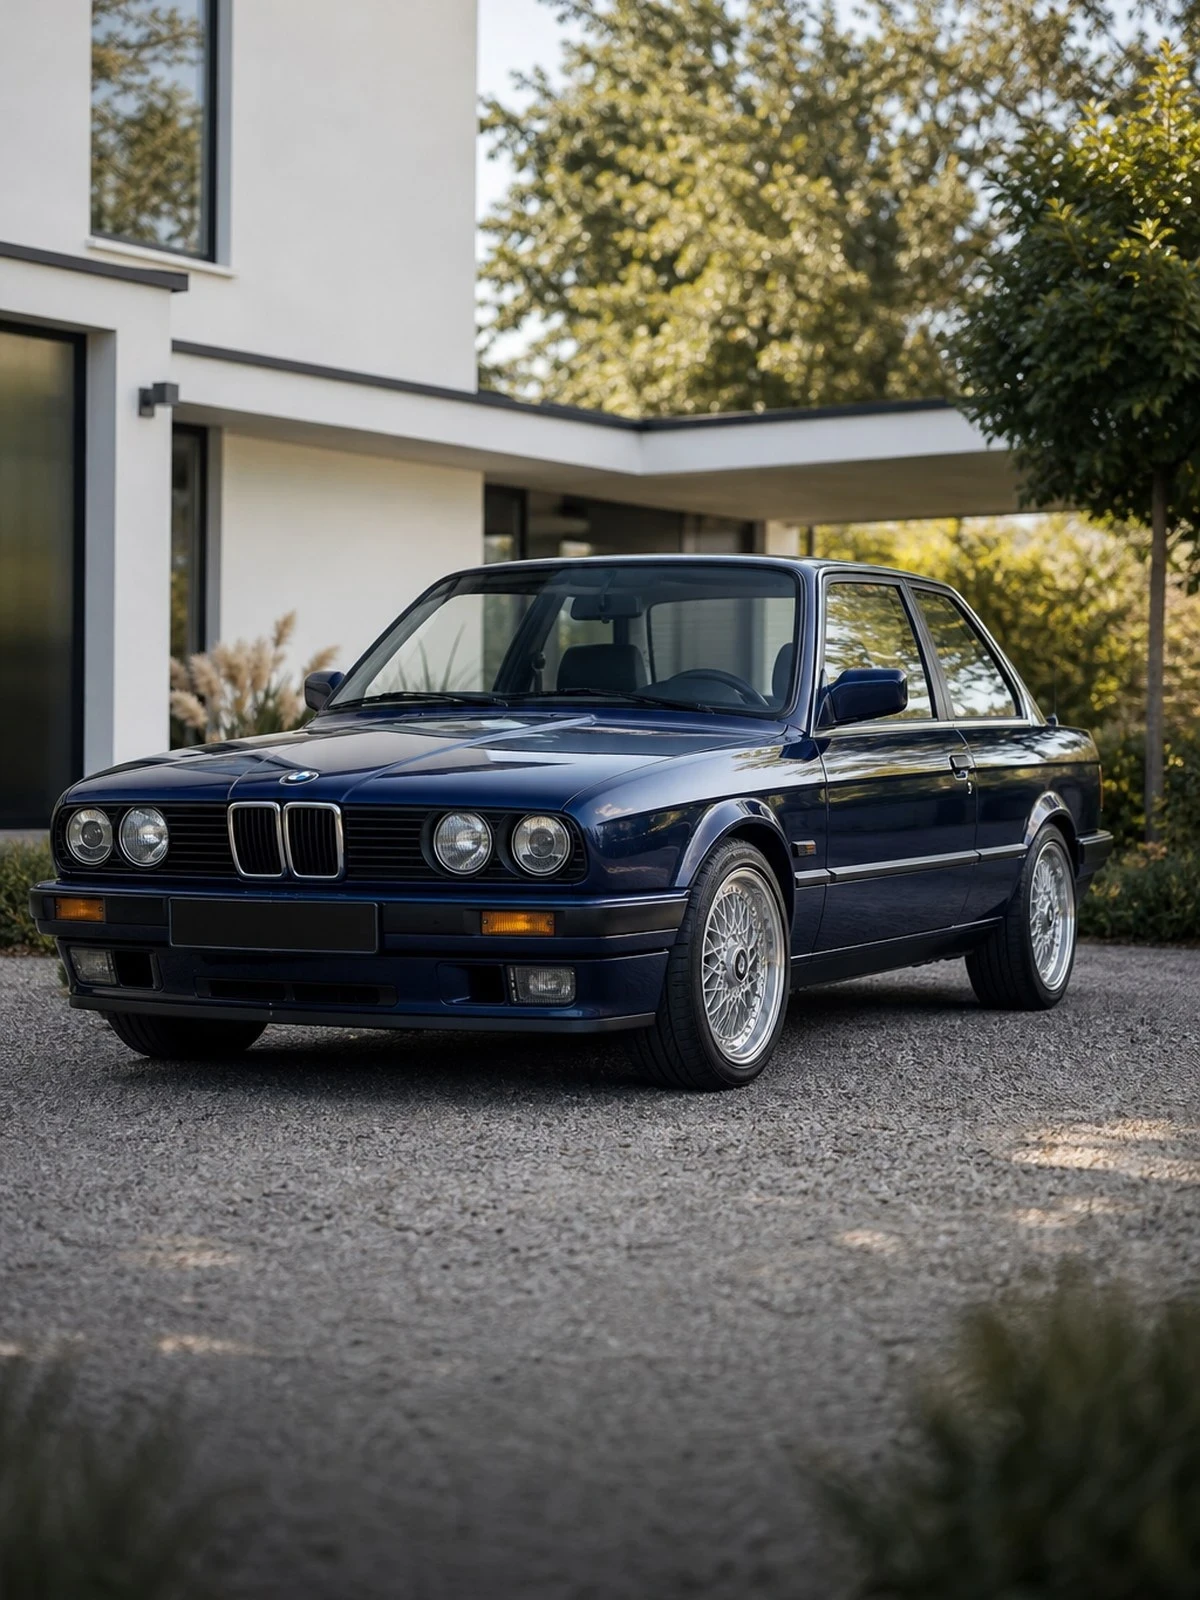 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The legally required basic cover and the cheapest option. Suitable for a youngtimer with a limited market value, where you carry own damage yourself.
As well as third-party liability cover, protection against theft, fire, storm and glass damage — at an agreed valued amount if you wish. For many youngtimers the happy medium.
The most complete cover, including where you are at fault. Recommended for a valuable, well-maintained youngtimer, preferably at an agreed valued amount.
What is covered
| What we do | At Finass | Direct with Ansvar |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Provided it is declared |
| One point of contact for claims | Yes | Provided it is declared |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether Ansvar is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
What we do
| What we do | At Finass | Direct with Youngtimerverzekering |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Sometimes |
| One point of contact for claims | Yes | Sometimes |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether Youngtimerverzekering is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
This overview concerns our service, not the cover. What is actually covered is set out in the policy conditions and on the insurer's insurance card (verzekeringskaart); you receive both before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Valuation amount (optional) Insure your youngtimer at the value assessed in advance instead of the market value, so that you do not face a rapid write-down after a loss.
Breakdown assistance in the Netherlands & Europe 24/7 help with a breakdown on the road, with towing, roadside repair and a replacement vehicle throughout Europe — useful if you also drive your youngtimer daily.
Passenger accident insurance (SVI) Pays for injury and material damage to the driver and passengers, regardless of who was at fault in an accident with your youngtimer.
Agency workers, interns & volunteers, traffic Legal assistance after a collision or in a dispute about damage or the purchase of your youngtimer, so that you are not on your own.
This is what people ask us most.
A youngtimer is broadly a car of 15 to 25 years old. Younger than 15 years counts as an ordinary car; from 25 years we speak of a classic car. The exact limit an insurer applies can differ slightly. We look at which policy suits the age of your car.
A youngtimer is 15 to 25 years old, a classic car 25 years or older. You may generally drive a youngtimer daily and you still pay ordinary road tax on it. Stricter conditions of use often apply to classic cars, and from 40 years an exemption from road tax.
Yes, with many insurers you can insure a youngtimer at an agreed valued amount by means of a valuation report. That prevents the car being written down quickly to market value. For a readily saleable youngtimer of limited value, insuring at market value can actually be cheaper.
Often it is. Because of the limited market value and the generally careful use, the premium works out more favourably than for a new car. It is usually just a little higher than for a genuine classic car, because a youngtimer is driven daily more often. Comparing pays off.
The conditions are milder than for a classic car. Sometimes a minimum age for the driver or a mileage limit applies, but daily use is usually permitted. The exact requirements differ from insurer to insurer. We compare them for you.
For cars of 15 years and older used for business a separate benefit-in-kind addition applies: a percentage of the market value instead of the list price. That makes a youngtimer attractive for business drivers. The insurance is separate from this. We only arrange the car insurance and advise you independently.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.