

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
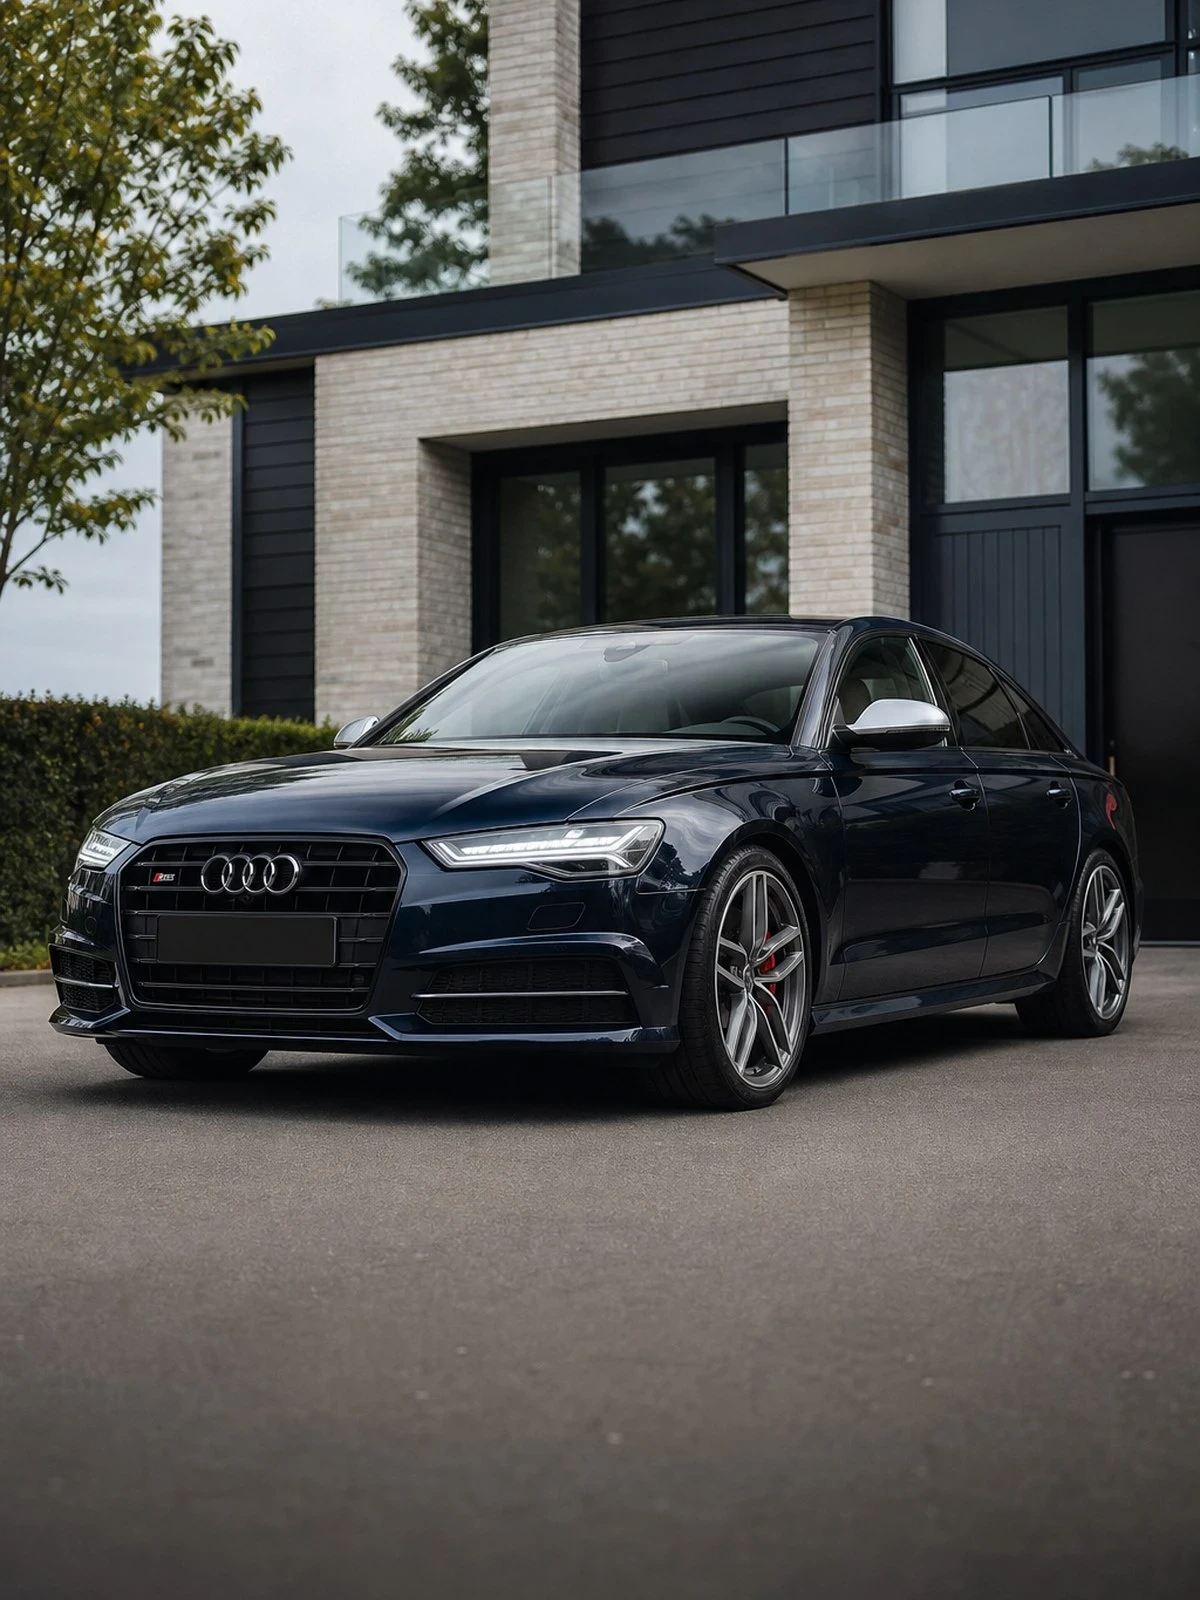
The S6 is a long-distance car: the premium here is determined less by the power than by the number of kilometres you cover in it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
An S6 is rarely kept as a weekend car. The saloon and above all the Avant are driven by people who cover a lot of motorway miles, who tow a trailer or run a roof rack and who regularly cross the border. That pattern of use determines your claims profile: relatively little parking damage, but an above-average amount of stone chip damage, collisions with animals and damage abroad. When you apply, the declared annual mileage is therefore the item that is tested most closely.
If you tow a trailer, bear in mind that liability follows the towing vehicle for as long as the combination is coupled; Article 2 of the Dutch Motor Insurance Liability Act (WAM) relates to the motor vehicle. Damage to the trailer itself is another matter and is not automatically covered by your own-damage cover. If you want the trailer or caravan itself protected, separate cover is needed for that.
For travel abroad, the area of cover shown on the green card is decisive. Countries that are crossed out are not covered, not even where you are only driving through. Report a loss as soon as reasonably possible, because Article 7:941 of the Dutch Civil Code links late notification to loss of the right to payment where the insurer's interests have been harmed as a result. See also the S7 if you are considering a fastback.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
On an S6 a mileage band is often agreed: up to a certain number of kilometres a year the agreed rate applies. If you regularly exceed it, that is a change in the risk which you have to report. Insurers check this when you claim, against the odometer reading and the MOT record. Anyone using an S6 for high mileage would do better to choose the higher band straight away than to argue afterwards about a declaration that was too low.
The losses that arise on long journeys nearly all sit in the third-party, fire and theft part: collisions with animals on the loose, glass damage from stone chips, damage from storms and falling branches. That means that even an S6 with a good many years behind it often benefits from third-party, fire and theft, even where comprehensive cover can no longer be justified. Note the condition that a collision with an animal must be demonstrable, for example with a police or wildlife management report.
An S6 Avant is often driven with a towbar or a roof box. Damage you cause to others with a trailer coupled falls under your liability cover. Damage to the trailer, the towed unit, the cycle carrier or the load itself does not. That calls for cover of its own. If the trailer comes loose and then causes damage, liability can still rest with you under Article 6:162 of the Dutch Civil Code.
The following remain outside the cover: damage in countries that are not on the green card or that are crossed out; damage to the load, the trailer or the roof box itself; wear and mechanical defects, such as damage to the transmission or air suspension without a collision; driving on a circuit or during a speed event; and damage arising while the car is hired out for payment or used to carry passengers for payment.
This is what people ask us most.
Report it as soon as you see it coming. If a much higher odometer reading only comes to light when you claim, the insurer can recalculate the rate retrospectively or adjust the payout to the premium ratio that would have applied. With a small overrun that usually does not happen. With a structural difference it almost always does.
Yes, a collision with an animal on the loose falls under third-party, fire and theft with practically every insurer, and therefore under comprehensive cover as well. You do have to make the collision plausible. Take photographs of the spot and the damage and report it to the police or the wildlife manager. Swerving without making contact with the animal is often treated as your own fault and then only falls under comprehensive cover.
Only within the area marked on the green card. Countries crossed out there fall outside the cover, even in transit. For some destinations you take out compulsory insurance at the border. Report a longer journey in advance, so that a temporary extension can be arranged if necessary.
No. Your car policy covers the damage you cause to others with the coupled combination, not the damage to the caravan or trailer itself. Separate caravan or trailer insurance is needed for that. The contents of the caravan and the load on a trailer also fall outside the cover of the car insurance.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.