

Third party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
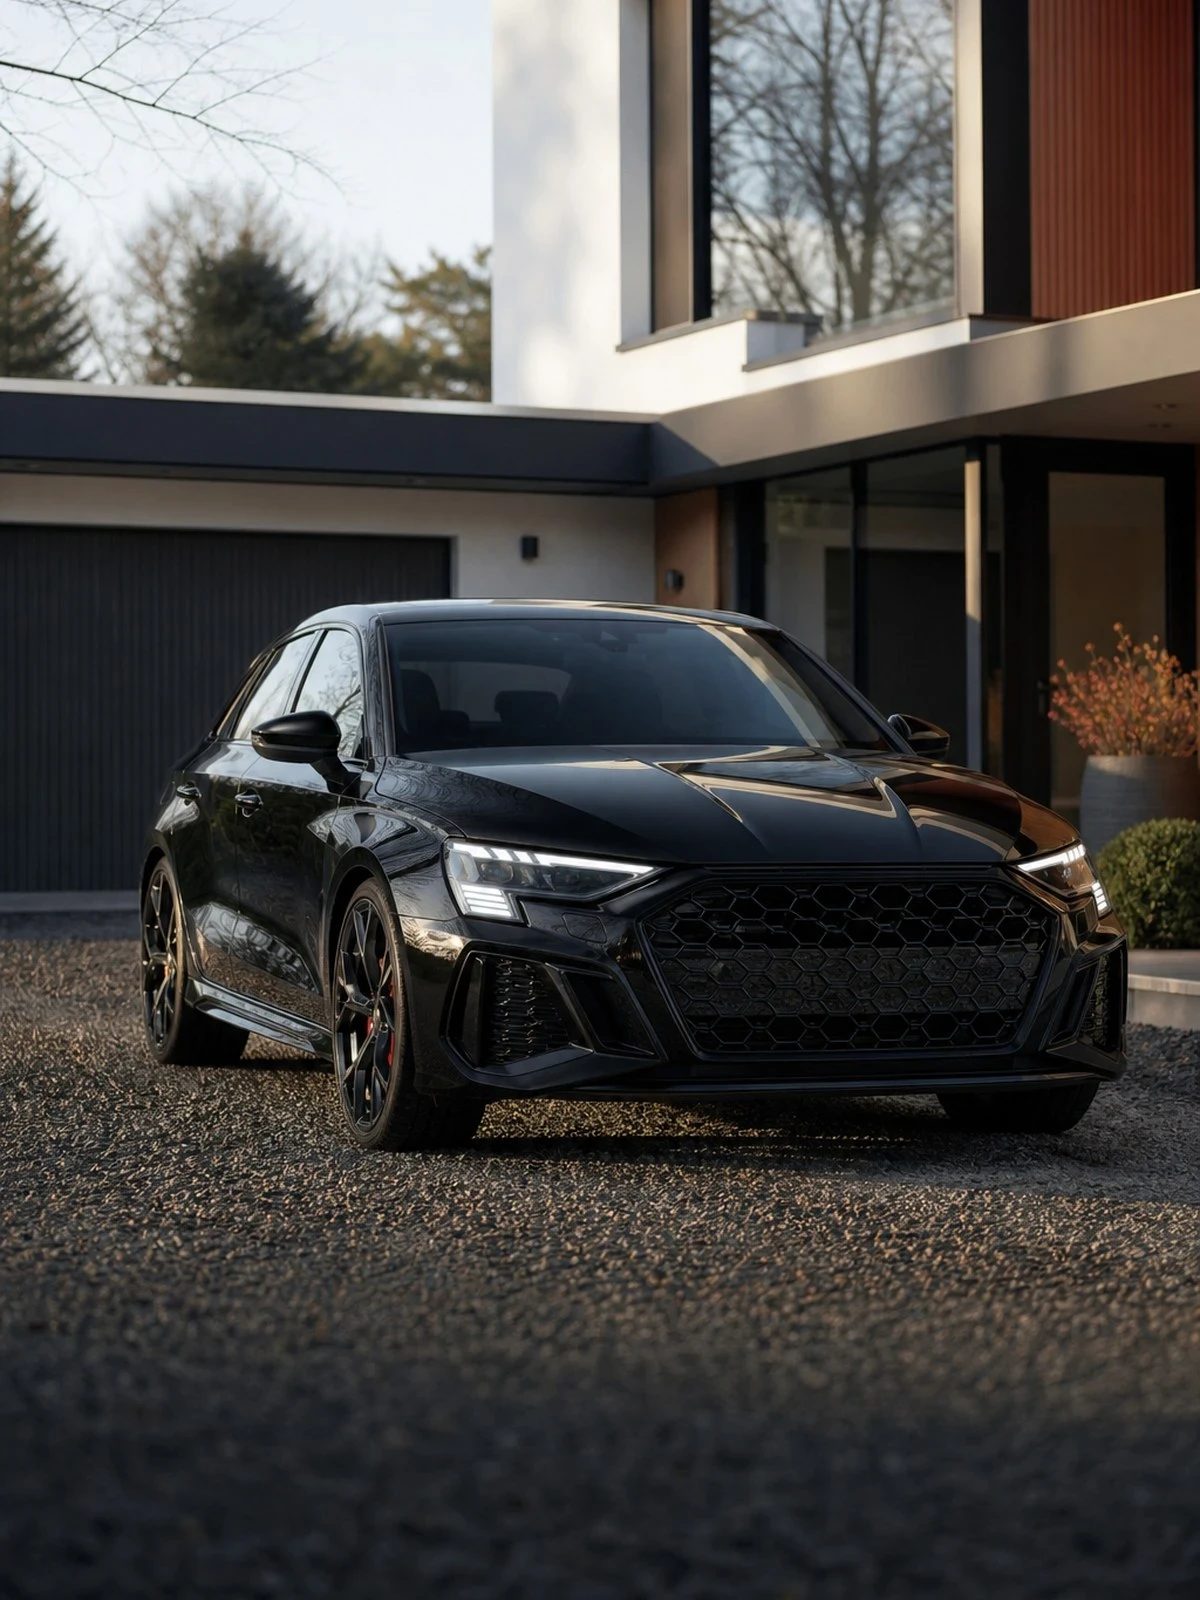
The RS3 puts a five-cylinder engine in a compact body. On this model it is less about cover and more about whether an insurer will Accept you at all.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A Premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The RS3 is the smallest car in the RS range and for that very reason the hardest to place. It is a compact hatchback or saloon with a five-cylinder turbo engine and four-wheel drive, in a segment where insurers see a lot of young drivers. Acceptance is the first hurdle here: many companies apply a minimum age, a minimum number of no-claims years or a requirement as to how long you have held your license in this power class.
A refusal is not without consequences either. On your next application you will be asked whether an insurer has previously refused you or cancelled a policy, and that answer falls under the duty of disclosure in Article 7:928 DCC. So it pays to know in advance where you can go rather than to gamble. If you are young or newly qualified, also read our page on Car insurance for young drivers.
The second point is power. The RS3 is a popular candidate for engine software that increases power. You must declare such a change and, under the vehicle registration rules, have it recorded. Without a declaration you are driving on a policy calculated on different details. You can Read more about the types of cover themselves under Comprehensive cover.
We compare your Car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car Insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per Situation below.
Damage you cause to others.
Causes beyond your control.
Including Damage you cause yourself.
What is covered
| Situation | Third party liability | Third party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid license | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the Insurance card (insurance card) of the insurer; you receive both before you take out Cover. Taking out Cover without advice? Then read what Execution only means for you.
Insurers weigh these details differently. That's where your saving is.
We look at the terms as well as the Premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and Compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing Call centers.
We cancel your old policy and align the start date, so you are never a day without Cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our Service on four aspects: personal Service, Service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
In this power class, insurers first assess whether they want to take the risk. Common requirements are a minimum age, a number of years' license held and a demonstrable number of no-claims years built up. If you do not meet them, the result is a refusal rather than a higher premium. We therefore ask in advance on what terms a company accepts this car, so that you do not end up with a string of refused applications against your name.
Software that adjusts the boost pressure or the limiter changes the car's power. That is a detail on which the rating group is based and it therefore belongs on the policy. The change must also be recorded in the vehicle register. If you drive with an undeclared power increase, the insurer may reduce the payout under Article 7:930 DCC, whether or not the extra power played a part in the claim.
The policy shows who the main driver is. The rate is based on that. If the car is registered to a parent while a son or daughter drives it every day, that detail is wrong. Insurers test this after a claim against driving patterns, refueling locations and statements. Many policies also apply an increased excess for drivers under a certain age. That is separate from the question of who pays for the policy.
Excluded are: driving on a circuit or during a track day, taking part in speed and maneuvering events, and driving under the influence or without a valid license. Wear-prone parts that go sooner because of your driving style, such as brakes, tires and the clutch, are not covered by own-damage cover either. Damage you cause with intent or recklessness is excluded under Article 7:952 DCC; on serious speeding offenses the insurer can rely on that.
This is what people ask us most.
With part of the market, no. For this power class a minimum age and a requirement as to no-claims years or years of license held often apply. There are companies that will accept with an increased excess. We test that in advance, so that you do not pick up a refusal that you have to declare on your next application.
Yes, always. Power determines the rating group and is therefore a detail on which the insurer bases its acceptance. The change should also be recorded in the vehicle register. Without a declaration the insurer can reduce or refuse the payout, even on a claim that has nothing to do with the extra power.
The registration may be in another name, but the main driver must be right. If you drive it every day, you are that driver and you belong on the policy. If it is established after a claim that the declaration was incorrect, the insurer can adjust the payout and cancel the policy. It is better to build up No-claims years of your own.
An ordinary fine does not affect the policy. On very serious offenses or on driving under the influence, the insurer can rely on recklessness and on the exclusions in the conditions. The third-party section will then usually still pay the other party, because the law requires it, but the insurer can recover the amount paid from you.
Every Situation is different. For these situations we have a separate page.
Request a Quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life Insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our license, Chamber of Commerce and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our Website.