

Third-party liability
- Damage you cause to others with the A1
- No cover for theft or damage to your own car
- Lower premium for young drivers
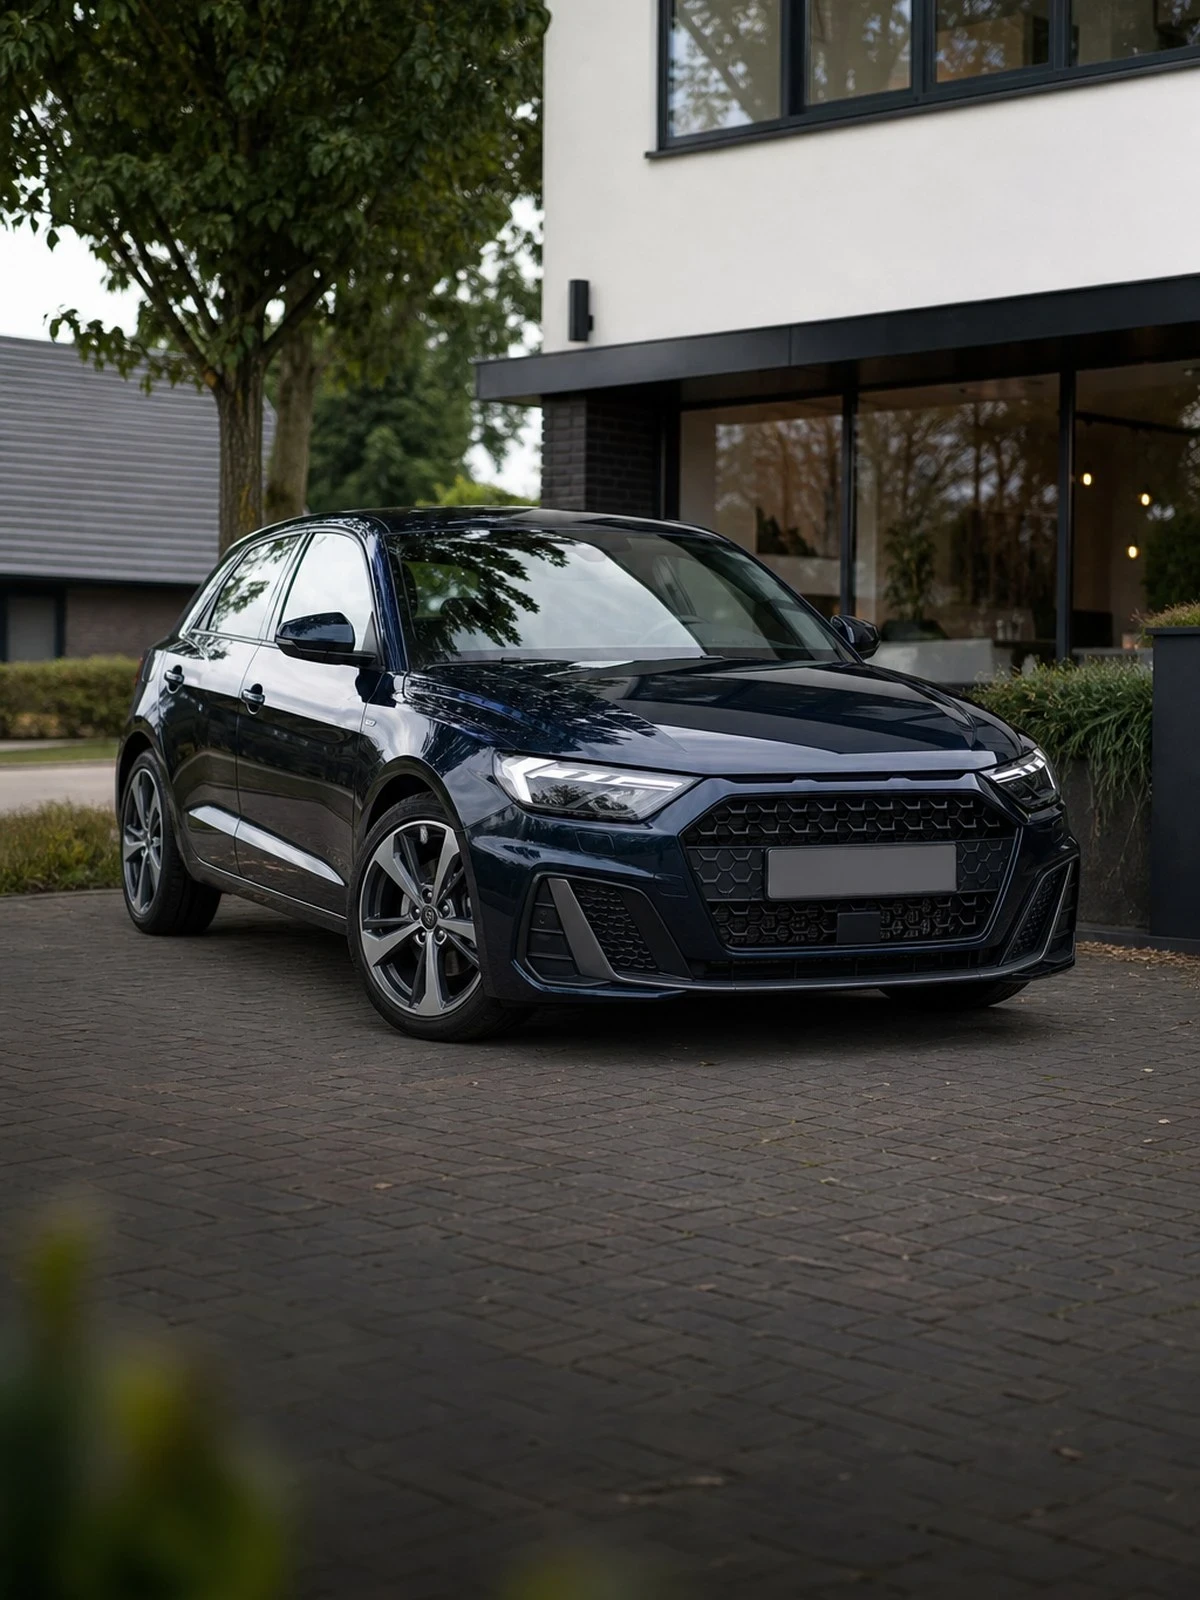
The A1 is a small car with premium technology: a low entry price, but headlights, sensors and a keyless key that make damage and theft more expensive than with an ordinary compact car.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
The Audi A1 came onto the market in 2010 as a three-door and five-door (Sportback). Since the second generation of 2018 it has only been available as a Sportback, with petrol engines from 25 to 40 TFSI and the raised citycarver variant. There is no electric or hybrid A1. Audi has indicated that the model will not get a direct successor, so the supply in the coming years will mainly consist of used cars.
For insurance, the A1 sits in an intermediate position. The list price of a new A1 is generally around € 30,000 to € 38,000, so most insurers do not require any security beyond the factory immobiliser. Repair costs are, however, higher than for a Polo or Ibiza on the same platform, due to Audi parts, LED lighting and, on newer examples, cameras and radar for driver assistance systems.
Many A1 drivers are young or are driving their first car of their own. Few no-claims years (schadevrije jaren) make comprehensive cover (allrisk) relatively expensive, while a first-generation A1 now has a market value at which limited comprehensive (beperkt casco) or third-party only (WA) is often sufficient. The choice therefore depends heavily on the year of manufacture, the version and the driver.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
With an A1, it is mainly the generation, the market value and the driver's no-claims years that determine which cover fits.
Often sufficient for a first-generation A1 with a low market value.
Suits an A1 that is five to ten years old and whose value is still worth protecting.
The usual choice for a new or recent A1 Sportback, especially with financing or private lease.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
What A1 drivers run into in practice.
The A1 is popular as a first car, including when parents buy it for a child. If you put the car in the parent's name while the child is the main driver, the information is incorrect and after a claim the insurer may limit or recover the payout. Always register the youngest regular driver. This raises the premium, especially with comprehensive cover, but a correct policy avoids disputes. Some insurers charge a fixed excess for drivers under 24.
An A1 from 2010 to 2018 now has a market value that is often between € 5,000 and € 12,000, depending on version and mileage. At those amounts, the comprehensive premium does not always outweigh the payout in the event of a total loss. The second generation has a higher value and more electronics, such as a digital cockpit and, on many examples, a front camera behind the windscreen. There, comprehensive cover remains worthwhile for longer. Base the decision on the current market value, not on the original price.
Many second-generation A1s have a keyless entry key that opens the car without touching the key. That makes the car vulnerable to theft with a signal amplifier. The A1 is not in the top ten of most stolen cars, but even with lower numbers the insurer will ask about the keys and the circumstances after a theft. Keep the key in a shielding pouch and always hand in all keys after a theft. Without limited comprehensive or comprehensive cover, theft is not covered.
The A1 shares its base with the Volkswagen Polo and Seat Ibiza, but the parts are not interchangeable at the same price. Bumpers, LED headlights and grille are Audi-specific. After a rear-end collision, the bill is therefore often higher than you would expect for a small car, especially if parking sensors or radar also have to be replaced and calibrated. If you are at fault, that is only covered by comprehensive cover; a higher excess can lower the premium without excluding the large claims.
Questions we often get about insuring an A1.
Usually not. For most versions, the list price of an A1 stays below the threshold above which insurers require a class 3 alarm or a tracking system. The factory immobiliser is then generally sufficient. With a more expensive version, such as the 40 TFSI with lots of options, this may be different. Check the conditions of the chosen insurer; that threshold differs per insurer.
With the same driver and a comparable engine, the premium for an A1 is often slightly higher. That is due to the higher list price and more expensive parts. With third-party cover the difference is small, with comprehensive cover noticeably larger. If you are torn between the two, you can have a comparison made in advance based on the registration number or version; we will gladly calculate it for you.
Little changes for the cover. Parts will remain available for years through Audi and the Volkswagen Group. However, the market value may develop differently than for a model with a successor. After a total loss, the insurer pays the market value based on comparable used cars, or for a young car the new value according to the policy arrangement.
Yes, no-claims years are linked to you as the policyholder and not to the car. The new insurer retrieves them via Roy-data. If you previously only drove as a regular driver on a parent's policy, you usually did not build up those years yourself. Some insurers offer a more favourable starting discount in that case; this differs per insurer.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.