

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
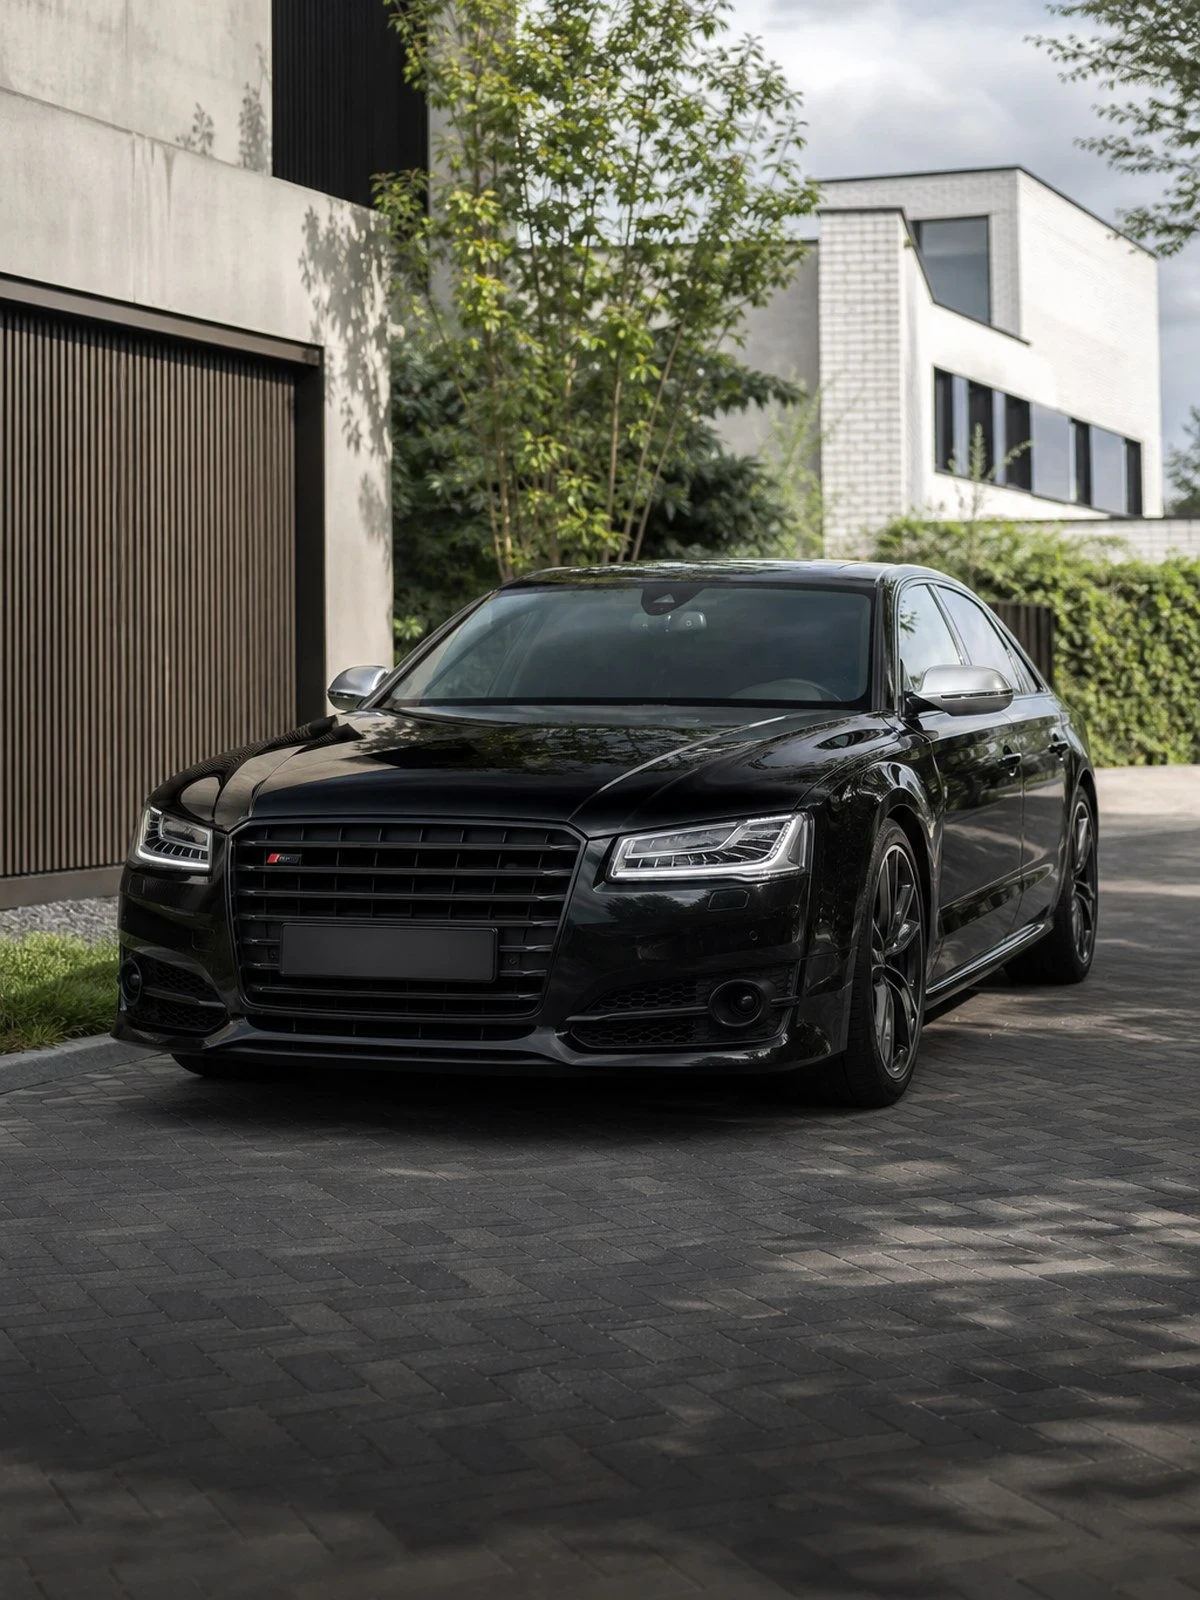
The S8 is a top-end limousine with air suspension, rear-axle steering and keyless entry: here it is theft prevention and electronics that determine acceptance.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
With an S8 the conversation moves from power to technology and theft. The car runs on air suspension, has a steered rear axle, active suspension and a large number of sensors around the body. That makes repair after apparently limited damage laborious: parts have to be not only replaced but also programmed in and aligned. Insurers take that into account in the own-damage rate, even on an example that is already a few years old.
The second point is the key. Cars with keyless entry and start are stolen by amplifying the signal from the key from wherever it is lying indoors. Insurers therefore often make requirements as to security: an approved vehicle tracking system, an additional immobiliser or the use of a shielded key pouch. If such a requirement appears as a condition on your policy and has not been met, the insurer can refuse a theft claim.
Finally, note that the S8 is a version built in small numbers. After a loss the assessor looks for comparable cars for sale, and here there are hardly any. The calculation is then quickly based on the value of an A8 with a similar mileage, while the S8 has a market of its own. If you want to avoid that, have the car valued. An agreed value is binding under Article 7:960 of the Dutch Civil Code. See also the S7.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
For cars in this class insurers tie theft cover to a demonstrable system: a tracking system with a subscription, an approved alarm class or an additional immobiliser. That subscription must actually be running. A contract cancelled or not renewed is one of the most common reasons a theft claim fails. Keep the installation certificate and the payment receipts with your policy, so that you can produce them straight away when you report a claim.
A collision on an S8 rarely affects bodywork alone. The ride height sensors, the air suspension compressor, the wiring to the steered rear axle and the camera systems all have to be programmed in and recalibrated after the repair. Those hours count in the estimate and mean that the repair costs work out high in relation to the market value. On an older example that more often leads to a total loss than to a repair.
The S8 is an exceptional version within an already limited model range. Several comparable examples are rarely for sale at the same time, so on a total loss an assessor falls back on the nearest reference: an A8 of the same age. That does not do justice to the version. A valuation report from a recognised assessor fixes the value in advance and removes that argument, even on a car that is already several years old.
The following remain outside the cover: theft while the security requirement set in the policy has not been met or while the key has been left in or on the car; carrying passengers for payment and hire; mechanical failures of the air suspension, compressor or electronics without a collision; damage sustained on a circuit or in a speed event; and damage caused intentionally or by recklessness, on which the insurer can rely through Article 7:952 of the Dutch Civil Code.
This is what people ask us most.
On a car in this class many insurers make that a condition, sometimes combined with an approved alarm class. If it appears as a requirement on your policy schedule, it is not advice but a condition of cover: without a working system and a current subscription, a theft claim can be refused. Ask in advance which systems are accepted, because not every make qualifies.
In principle yes, because this is theft and not carelessness. The argument usually turns on the keys: can you produce all the keys and have the security requirements been met. So keep the key in a shielded pouch or tin and make sure you can hand in both keys when you report the theft.
Often it is. Because there are few comparable cars for sale, the market value after a loss is derived from an ordinary A8 of the same age and mileage. A valuation report fixes the value of the version in advance, including the options that set the car apart. Do note that such a report has a period of validity and must be renewed in good time.
Only where it results from a covered event, such as a collision or a hard knock in a pothole. Wear, a leaking air spring or a compressor that has failed with age is a mechanical defect and falls outside every own-damage cover. That distinction matters on this car, because the system is expensive to replace.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.