

Third-party liability
- Required by law
- As long as the registration is in your name
- Suspend the registration when not in use
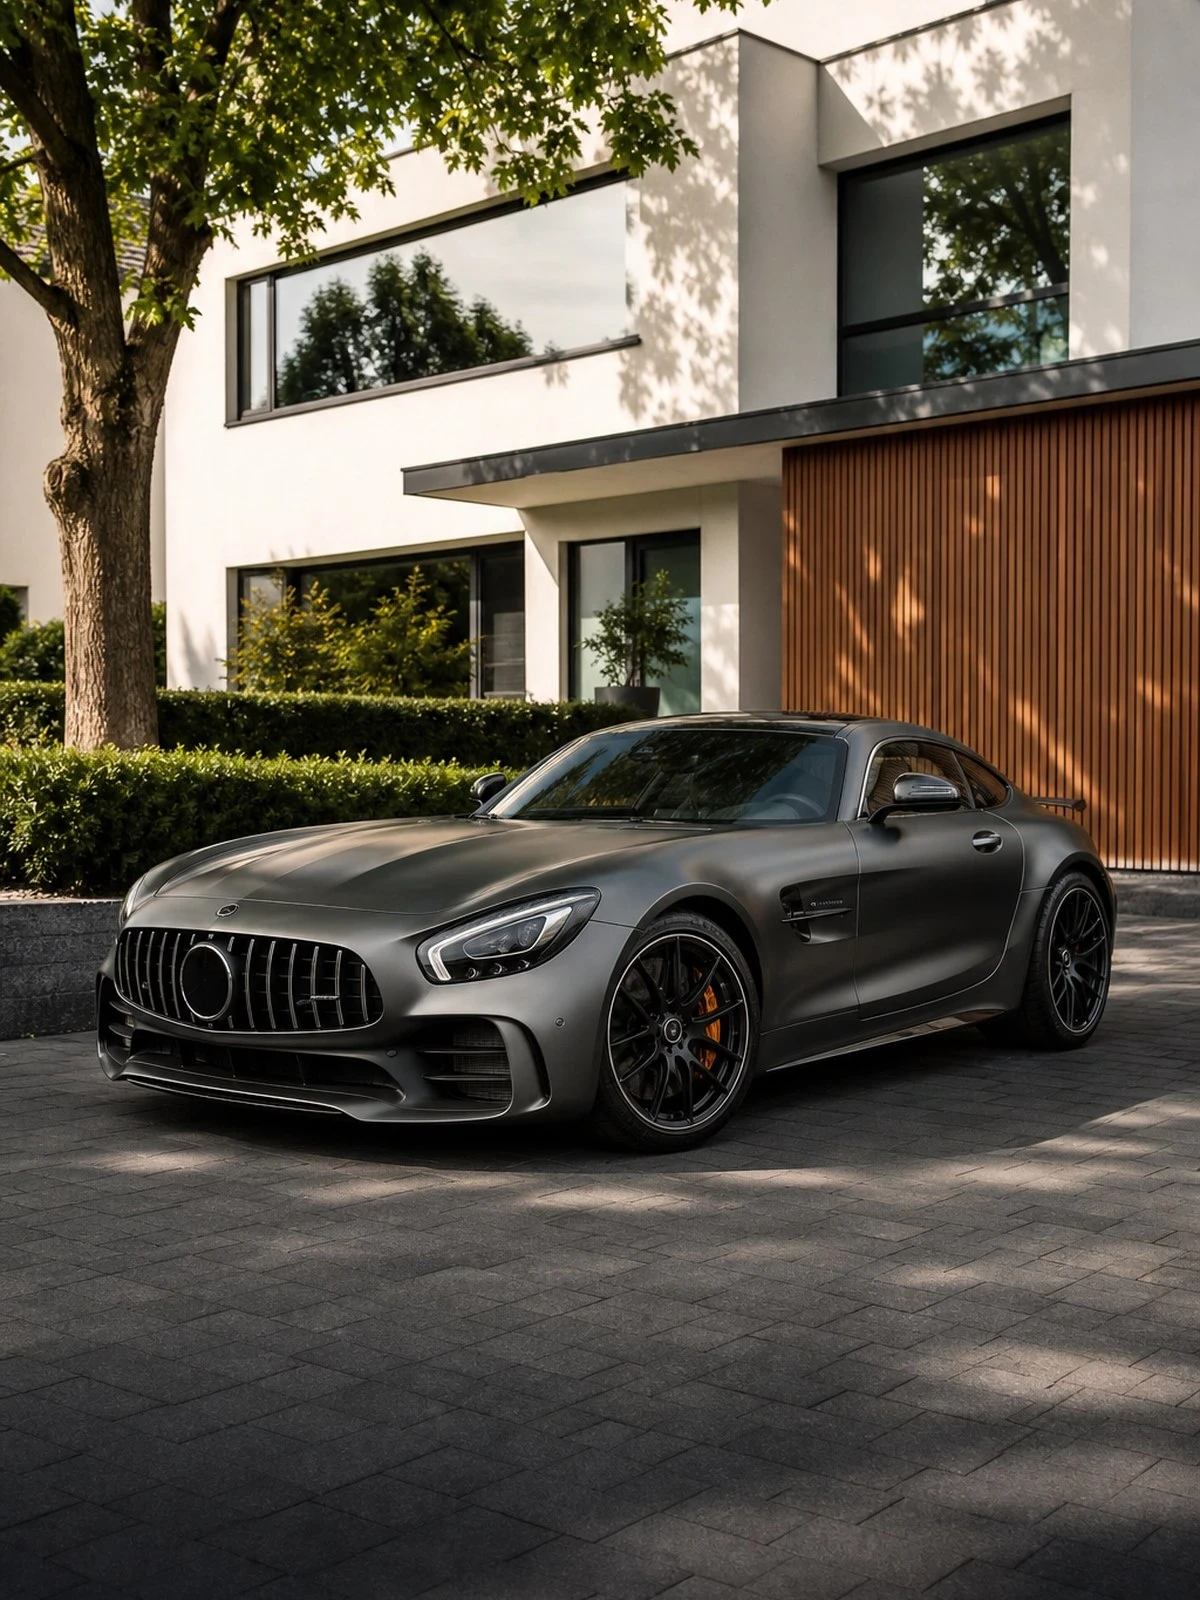
The AMG GT is a sports car with a long nose, wide rear tyres and a very low floorpan. That is also where most of the damage occurs.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The AMG GT can be used every day, and for insurance purposes that makes it different from a car that only comes out on fine days. It goes into car parks, over speed humps and up driveways, with a long front end and a splitter that sits close to the ground. Scraping damage to the spoiler, the floorpan and the sills is the most frequently reported damage on this model and is covered only under comprehensive cover, because it is damage of your own doing.
The second point to note is the specification. Large alloy wheels with low-profile tyres, optional ceramic brake discs and aerodynamic parts are each of them expensive and vulnerable. Note the distinction that every policy draws here: damage to a wheel or tyre resulting from a collision or another insured event is paid for, but a tyre destroyed by a kerb or a pothole without a collision falls outside it. The same applies to wear on brake components.
If you drive the open version or attend driver training and track programmes, arrange that separately. Track use is excluded, even on a tuition day with an instructor beside you. For your choice of cover, compare comprehensive or third-party, fire and theft. If you fail to declare a modification or the way the car is actually used, you are up against the duty of disclosure in Article 7:928 of the Dutch Civil Code and the sanction in Article 7:930 of the Dutch Civil Code.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others.
Causes beyond your control.
Including damage you cause yourself.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Damage to the other party | Yes | Yes | Yes |
| Theft | No | Yes | Yes |
| Fire and storm | No | Yes | Yes |
| Damage you cause yourself | No | No | Yes |
| Wear and mechanical defects | No | No | No |
| Driving without a valid licence | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Ground clearance is minimal and the front overhang is long. A speed hump taken at an angle or a car park with a steep ramp is enough to damage the splitter, the floorpan or the sill trim. Such damage is not a collision with a third party and therefore falls under comprehensive cover only. Report it even where it looks cosmetic: under the trim sit fixings and aerodynamic parts that have to be replaced with it, and they raise the estimate considerably.
A damaged wheel or a split tyre after a collision is covered, but the same damage caused by a kerb or a hole in the road surface without an impact falls outside the cover on virtually every policy. Ceramic brake discs are wearing parts and are therefore excluded too, unless they are damaged by an insured event. On this model, that distinction between wear and event is the most common reason for a claim being refused.
Manufacturer driver training programmes, tuition days on a circuit and handling courses fall outside the standard cover, even where the purpose is training and no timed runs take place. For own damage on the track there are separate day covers that you arrange in advance. Also check the participants' rules to see who is liable for damage to the circuit's equipment. That item almost always sits with the participant and is not covered by a motor policy.
Outside the cover are: use on a circuit, on a speed run or during a driver training programme on a track; tyre and wheel damage without a collision, as well as wear to brakes and clutch; mechanical defects without an insured event; damage to the hood fabric of the open version through ageing or incorrect folding; and damage during hire or paid carriage of passengers, for example for wedding or experience drives.
This is what people ask us most.
Only under comprehensive cover. It is damage you cause yourself with no other party involved, and that falls outside third-party liability and outside third-party, fire and theft. On a low sports car it happens often, so weigh it up when choosing your cover and your excess. Bear in mind too that several small at-fault claims affect your no-claims years.
As a rule, no. Tyre and wheel damage is usually covered only where it results from a collision or another insured event. A blow-out, damage from a hole in the road surface or from a kerb falls outside that. Some insurers offer separate tyre cover for this; ask about it if you drive a lot in town.
To training on a closed site with no speed or timing element, usually yes, but as soon as it takes place on a circuit it is excluded. That also applies to manufacturer programmes with an instructor. Ask the organiser in writing what the nature of the day is and, if necessary, arrange separate day cover for own damage in advance.
Damage from vandalism, slashing or an attempted break-in falls under third-party, fire and theft. Wear, discolouration, leaking seams and a sticking mechanism are not sudden events and remain outside the cover. Have the mechanism checked periodically and never stow the hood wet; that prevents most of the damage that would not be paid for anyway.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.