

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
The 1 Series is often registered to a parent while a young driver covers most of the mileage, and that is precisely where this policy most often comes unstuck.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
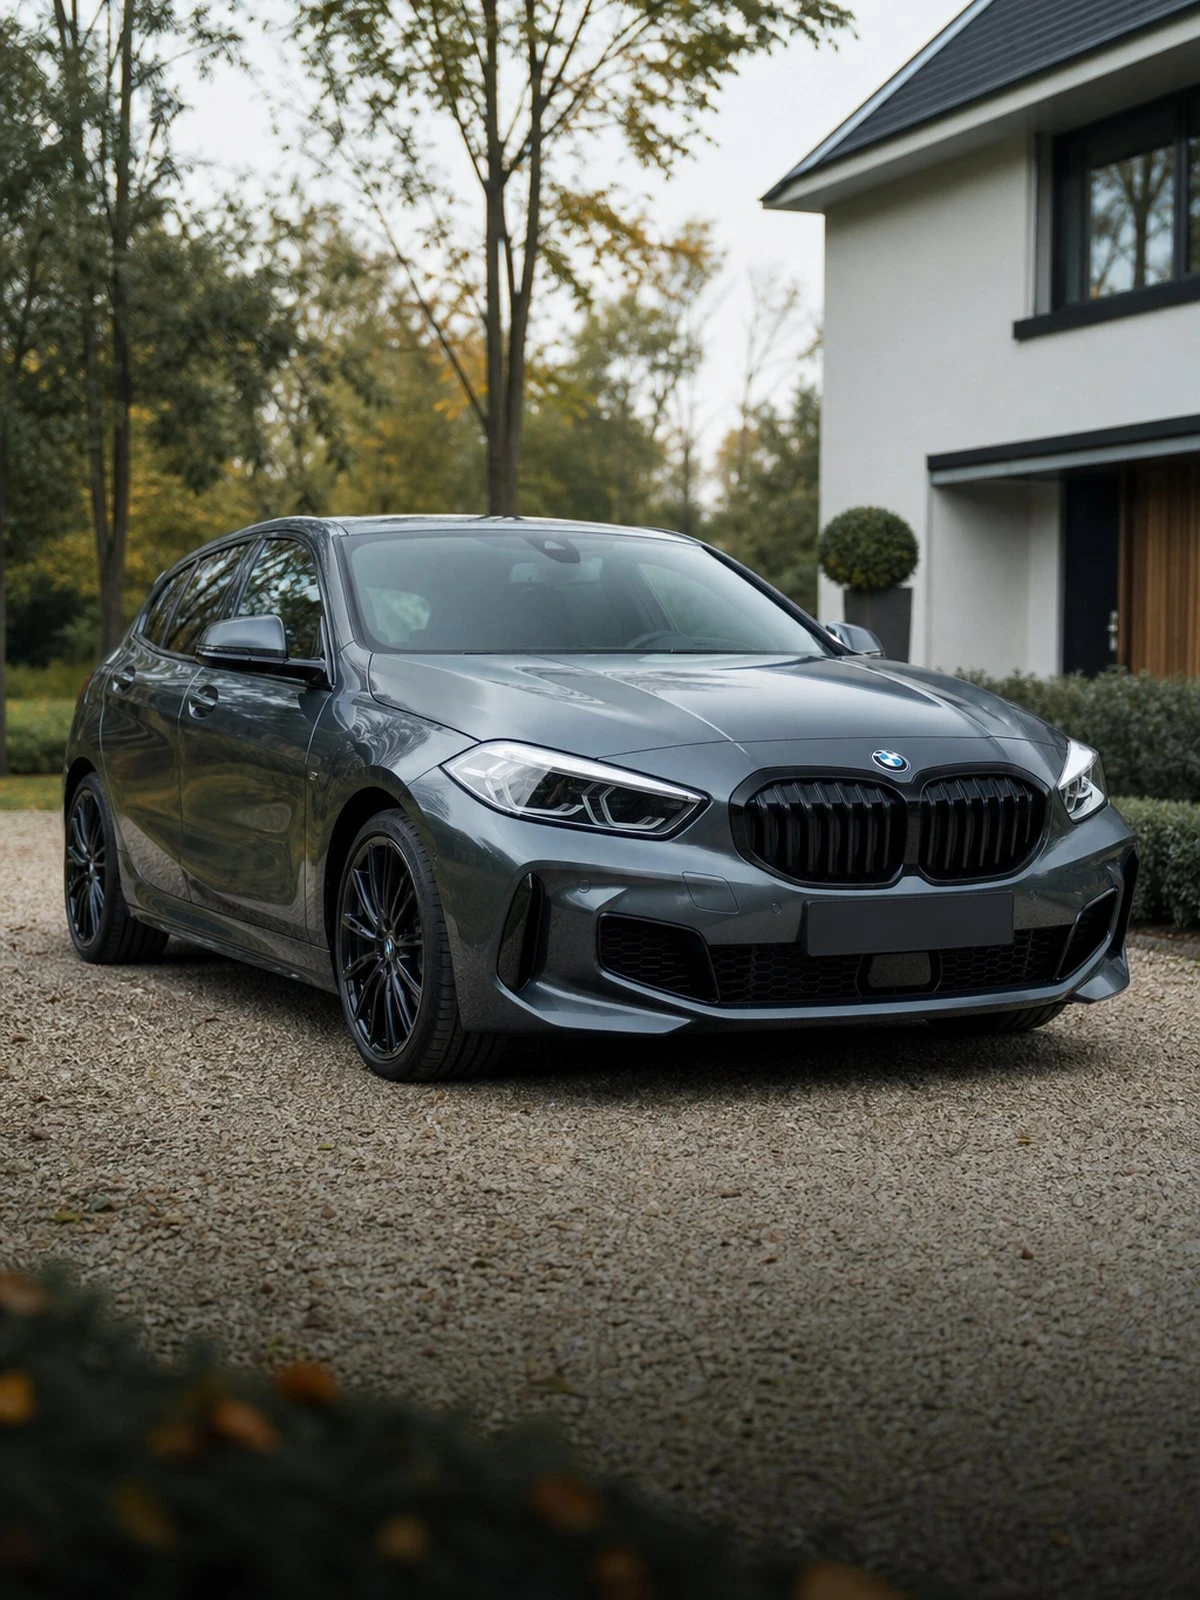
The 1 Series is the smallest BMW passenger car and is driven in the Netherlands mainly as a used car. That makes the insurance question different from the larger models: the market value is modest, but the car is still technically a BMW. A collision that destroys a headlamp unit, a bumper beam with sensors and a door quickly costs more than the car is worth at that moment.
The second point is who drives it. Insurers ask not only about the registered keeper but about the regular driver: the person who uses the car most. If the policy is in a parent's name while an eighteen-year-old drives it every day, that is incorrect information at the time the insurance is taken out. Article 7:928 of the Dutch Civil Code sets out that duty of disclosure and Article 7:930 of the Dutch Civil Code determines what the insurer may do after a claim where the declaration was incorrect: reduce or refuse the payment.
If you drive a more powerful version or are considering a larger model, also look at Insuring a BMW 3 Series; the underwriting questions there are different.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your BMW 1 Series | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The premium for a young driver is higher, and that is precisely why the car is so often registered to a parent. Insurers check this after a claim: who was on the accident statement form, who filled up, where was the car at night. If the regular driver declared turns out to be wrong, Article 7:930 of the Dutch Civil Code works through into the payment. It is better to declare the real situation in advance.
The older 1 Series is rear-wheel drive, unusual in this segment. In the wet and on slippery roads that asks more of the driver, and single-vehicle damage does occur on this model: a verge, a bollard, a parked car. That is exactly what third-party liability plus third-party, fire and theft does not cover. Anyone who wants their own fault covered needs comprehensive cover, and at a low market value that is not always defensible.
The relationship between those two determines everything here. A windscreen with a camera for the driver assistance systems has to be recalibrated after replacement. That belongs to the glass claims arrangement and not every glass repairer carries it out. LED headlamps, sensors in the bumper and painted parts quickly push the estimate above the market value. The insurer then pays out on the basis of a write-off instead of repair.
Not covered are: driving without a valid licence or under the influence of alcohol or drugs, damage caused intentionally or through recklessness (Article 7:952 of the Dutch Civil Code), and wear or mechanical failure such as a worn clutch or a broken timing chain. Use you have not declared also falls outside it: giving driving lessons, hire, shared use through a platform or paid passenger transport. Declare such use in advance; afterwards it becomes an argument about cover.
Repair costs are at BMW level while the market value is low. That brings a write-off closer.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
You may register it that way, but the application form has a separate question about the regular driver. You have to answer that truthfully. If you do not, the insurer can rely on Article 7:930 of the Dutch Civil Code after a claim and reduce or refuse the payment. Simply declare the young driver. That costs premium, but it produces a policy that pays.
That depends on the market value against the excess. If the value drops so far that a payout leaves little after the excess, comprehensive cover mainly produces premium and little certainty. Third-party, fire and theft then keeps in place the risks you cannot influence yourself: theft, fire, storm and glass damage. Have the tipping point reviewed each year.
You bear the damage to your own car yourself. Third-party, fire and theft covers external causes, such as theft, fire, storm, hail, broken glass and a collision with wild animals. If you drive into a bollard, a wall or the verge yourself, that is your own fault and is only covered under comprehensive. Damage to the other party does remain covered through the third-party liability cover.
Under most glass claims arrangements, resetting the camera belongs to the replacement and is included. The condition is that the repairer is allowed to carry it out. If you choose a firm outside the insurer's network, a higher excess or a lower payment often applies. Ask in advance whether the firm you choose carries out the calibration itself.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.