

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
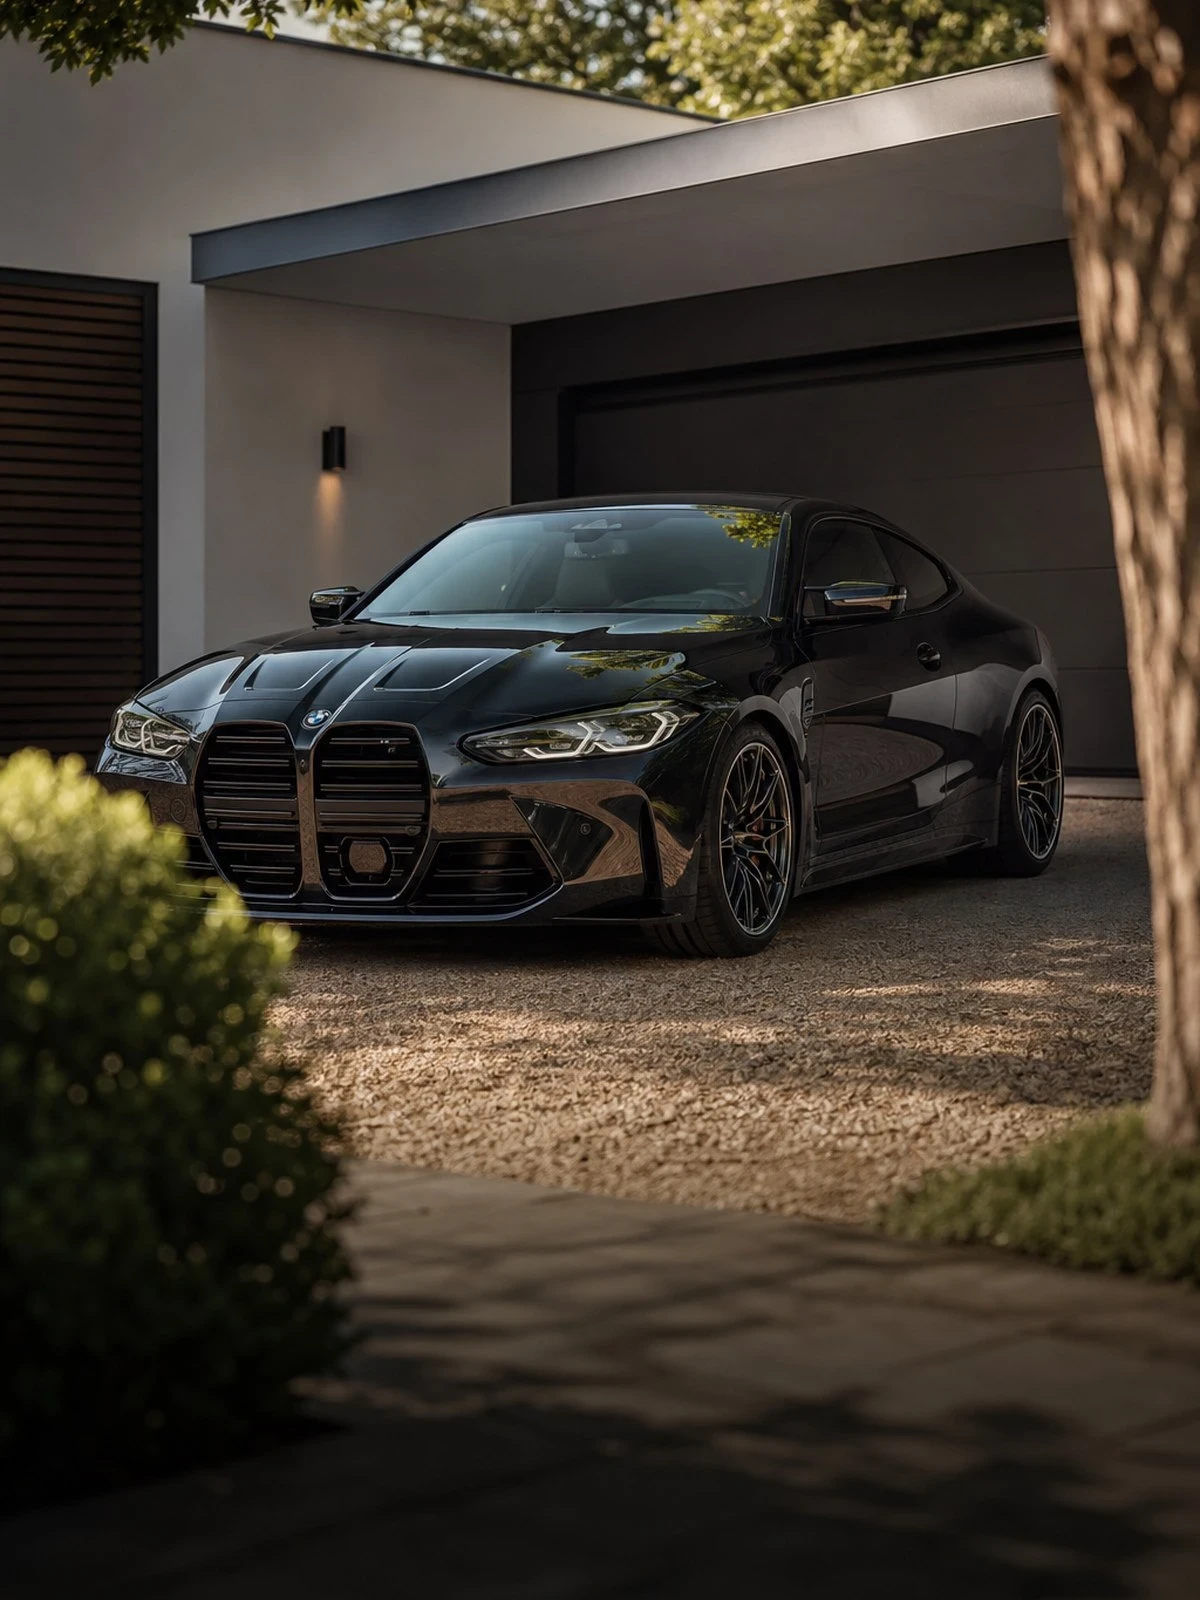
The M4 stands still for most of the year; that usage pattern, the storage and the security determine which type of policy suits it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Personal quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
Since 2014, the BMW M4 has been the two-door successor to the M3 Coupé: the F82 coupé and F83 convertible (2014-2020) with the 431 to 510 hp S55 engine, and since 2021 the G82 coupé and G83 convertible with the S58 and 480 to 530 hp, including the CSL and the M4 Competition xDrive. New, the list price is between € 110,000 and € 170,000; a 2016 F82 is worth roughly € 45,000 to € 60,000 as a used car.
In the Netherlands, the M4 is almost always a second car: weekends, fine weather, the occasional long drive, and an annual mileage of 5,000 to 10,000. Insurers that accept the car assess this more favourably, provided you declare the limited use, locked storage and another car for daily use, and actually stick to them.
The convertible with a fabric roof (G83) or hardtop (F83) needs extra attention for theft from the car and vandalism to the roof. And, as with the M3, driving on a circuit, even during a touring day, is excluded. If you buy the M4 to drive it at Zandvoort or on the Nordschleife, you need separate day cover for that.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
For an M4, the choice of cover depends on the generation and value, the annual mileage, the storage and whether an insurer accepts the combination of this power output and your profile.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your BMW M4 | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
These are the points that determine the policy and premium for a BMW M4.
An M4 that covers 6,000 kilometres a year and is kept in a locked garage is assessed differently by most insurers than the same car driven to the office every day. Some insurers offer a policy for this with a fixed maximum mileage and a storage requirement, similar to a youngtimer policy. The flip side is that you must comply with that agreement all year round: a summer in which the car nevertheless does 15,000 kilometres can lead to a reduced payout in the event of a claim. Declare the use realistically and report any change, for example if the M4 temporarily becomes your only car.
With 317 to 390 kW, the M4 is above the power limit many insurers apply for standard acceptance. Insurers that take the car usually require a driver of at least 25 to 30 with five or more no-claims years (schadevrije jaren), and want to know all regular drivers. An M4 that is also driven by a twenty-year-old son or daughter is accepted virtually nowhere. A previous cancellation by an insurer or several claims in recent years lead to rejection. We check acceptance in advance with several insurers, because a formal rejection must be disclosed in subsequent applications.
The M4 is a target for organised theft, often via the keyless signal or the OBD port, and parts of the S55 and S58 engines and the carbon brakes are in demand. Above a value of roughly € 75,000, insurers require an SCM-approved class 4 or 5 vehicle tracking system with a monitoring centre, in addition to the factory alarm. The subscription must be active at the time of theft; in practice, an expired subscription is the same as having no system. For an F82 with a current value below that threshold, a class 3 alarm is often sufficient. Keep the keyless key in a shielded pouch and use BMW's sleep mode.
The G83 has a fabric roof, the F83 a folding hardtop. A fabric roof is vulnerable to break-ins with a knife and to vandalism, and replacement costs an estimated € 3,000 to € 6,000. Break-in damage and theft from the car fall under limited comprehensive (beperkt casco); vandalism by an unknown person only under comprehensive (allrisk). The F83's hardtop mechanism is an expensive item in a rear-end collision. For a convertible, insurers sometimes ask explicitly about storage; a convertible parked on the street at night leads to a higher comprehensive premium or a restriction with some insurers.
Ordinary car insurance does not cover damage while driving on a circuit, not even on a touring day, a BMW Driving Experience or a Touristenfahrt on the Nürburgring. This applies both to damage to the M4 and to liability towards other participants. Separate track day insurance is available for such days from a few specialist providers, usually with an excess of ten to fifteen per cent of the insured value and without third-party cover. If you go to the circuit regularly, take this into account when buying, because the cost per day quickly runs to several hundred euros.
The M4 has a carbon roof, carbon seats and spoilers on the Competition and CSL, and an aluminium bonnet and wings. Repairs after a collision require a BMW-approved body shop authorised to work with those materials. Front-end damage involving laser headlights, radar, carbon splitter and cooling package quickly exceeds € 20,000 on a G82. After repair the car is worth less, and that loss of value is a real point of discussion with an exclusive car; if a third party is at fault you can recover it, if you are at fault you cannot. A three-year new-value arrangement limits the loss in the event of a total loss of a young M4.
Questions BMW M4 owners ask us.
Yes, with insurers that offer a limited-use policy. You then declare a maximum annual mileage, often 5,000 to 10,000 kilometres, locked storage and another car for daily use. As a result, the premium is often tens of per cent lower than with an ordinary policy. The downside is that you must continue to meet those conditions; exceeding them can lead to a reduced payout in the event of a claim.
Usually slightly, because a fabric roof is vulnerable to break-ins and vandalism and the F83's hardtop mechanism is expensive to repair. The list price of the convertible is also higher. With limited use and indoor storage, the difference usually remains small. If the convertible is parked on the street at night, an insurer may apply a higher premium or a restriction for theft from the car.
Not all of them. Some of the large insurers apply a power limit that the M4 exceeds; others accept the car with a driver of at least 25 to 30 with sufficient no-claims years. There are also specialist providers for exclusive and sports cars that accept the M4 as standard, often with an agreed-value or new-value arrangement. We know which insurers take the M4 and compare premiums and conditions among them.
No, not under ordinary car insurance. Driving on a circuit or closed site for speed or driver training is excluded, even without timing. Some organisers offer day cover or include it in the price; check what it covers and how high the excess is. Otherwise, take out track day insurance yourself with a specialist provider, well before the day and with the M4 named on it.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.