

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
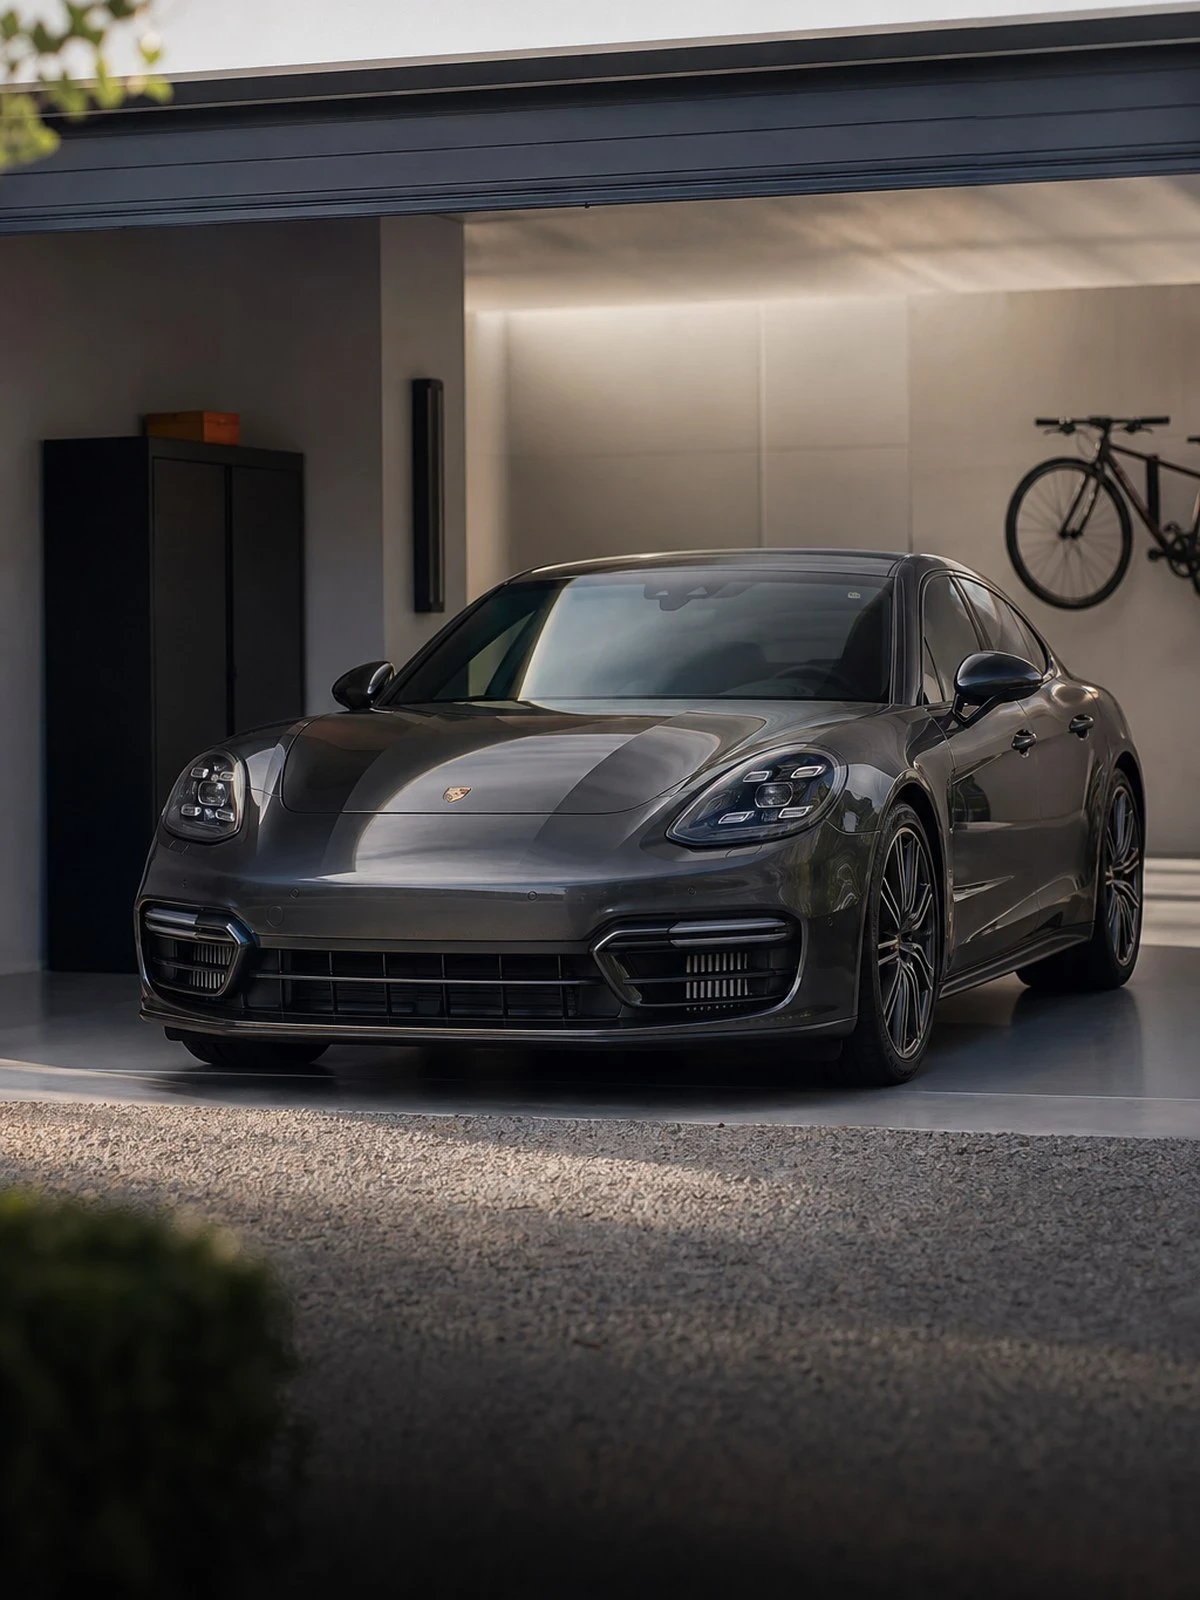
The Panamera is a long, heavy saloon full of electronics that is often driven for business, and it is precisely those two facts that determine what the policy has to look like.
This page in another language: Nederlands · Deutsch
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
With this model the insurance subject is not the top speed but the bill after a minor collision. Behind the bumpers sit radar sensors, cameras and ultrasonic modules. The headlights are adaptive and on many versions the suspension is pneumatic. A scrape in a car park therefore rarely affects paint alone. After repair there is also a compulsory calibration of the driver assistance systems, and those hours appear on the invoice too.
The second characteristic is who drives it. A Panamera is often registered to a business, is used by more than one person and regularly serves as executive transport. Insurers record this in a driver clause or in the declaration of the youngest regular driver. If that declaration is incorrect at the time of a claim, Article 7:930 of the Dutch Civil Code comes into play and the payment can be reduced.
With a car with a long options list, an argument about the value after a write-off is a real prospect. A valuation report from an expert fixes the value in advance, within the limits of Article 7:960 of the Dutch Civil Code. If you drive the E-Hybrid, also declare your charging situation. For the fully electric version within the brand we refer you to the Taycan.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your Porsche Panamera | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A dent in the front bumper of a Panamera usually also means a radar module, ultrasonic sensors and sometimes a camera. Those parts have to be aligned and calibrated after fitting, otherwise the driver assistance systems no longer work reliably. The same goes for a matrix headlight or ride-height control caught in the impact. So expect cosmetically minor damage to produce a substantial repair bill. That is an argument for not setting the excess too high.
If the Panamera is used by several people, that must be stated on the policy. Insurers work with a declaration of the regular driver and sometimes with a minimum age in a clause. Lending the car occasionally to a colleague or family member is usually covered. If that person is in fact the regular driver, it is not. With a business registration the insurer also checks whether the use is private or business.
With a car whose options make up a substantial part of the value, market value after a write-off is a conversation you would rather not have. A valuation report from a recognised valuer fixes the value and limits that discussion. The insurer determines how long the report remains valid. Without a valuation, the market value on the date of the loss applies. Payment of more than the loss suffered is not possible. That follows from Article 7:960 of the Dutch Civil Code.
Outside the cover: paid passenger transport and chauffeur services for a fee; driving on a circuit or at a timed event; faults in electronics, air suspension or software with no event from outside; wear to the compressor, air springs, tyres and brakes; damage after an undeclared power upgrade or suspension modification; and damage caused by intent or recklessness, as referred to in Article 7:952 of the Dutch Civil Code.
Air suspension, rear-axle steering and assistance systems make every claim expensive.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
It is not compulsory, but with a car with an extensive options list a valuation report saves you having to negotiate about market value after a write-off. A recognised valuer fixes the value and the insurer determines how long that report lasts. Payment above the loss actually suffered is not possible in any event, because Article 7:960 of the Dutch Civil Code prohibits it.
Occasional lending is covered under most policies. If someone else becomes the actual regular driver, that person must be declared as the regular driver. If there is an age clause on the policy, it applies to everyone behind the wheel. Paid passenger transport falls outside the cover in all cases, even if you only share the fuel costs.
Yes, the battery is part of the vehicle and falls under own-damage cover in the event of an insured occurrence. Loss of capacity through ageing is not damage but wear and is not paid for. That is a warranty matter. Do declare where and how you charge, because a charging facility at home can form part of the acceptance questions.
Because the bumpers and mirrors of this car house radar, cameras and ultrasonic sensors that have to be recalibrated after replacement. Then there is the ride-height control or air suspension. Damage that looks modest from the outside therefore costs considerably more than on a simpler car. Bear that in mind when choosing your excess.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.