

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
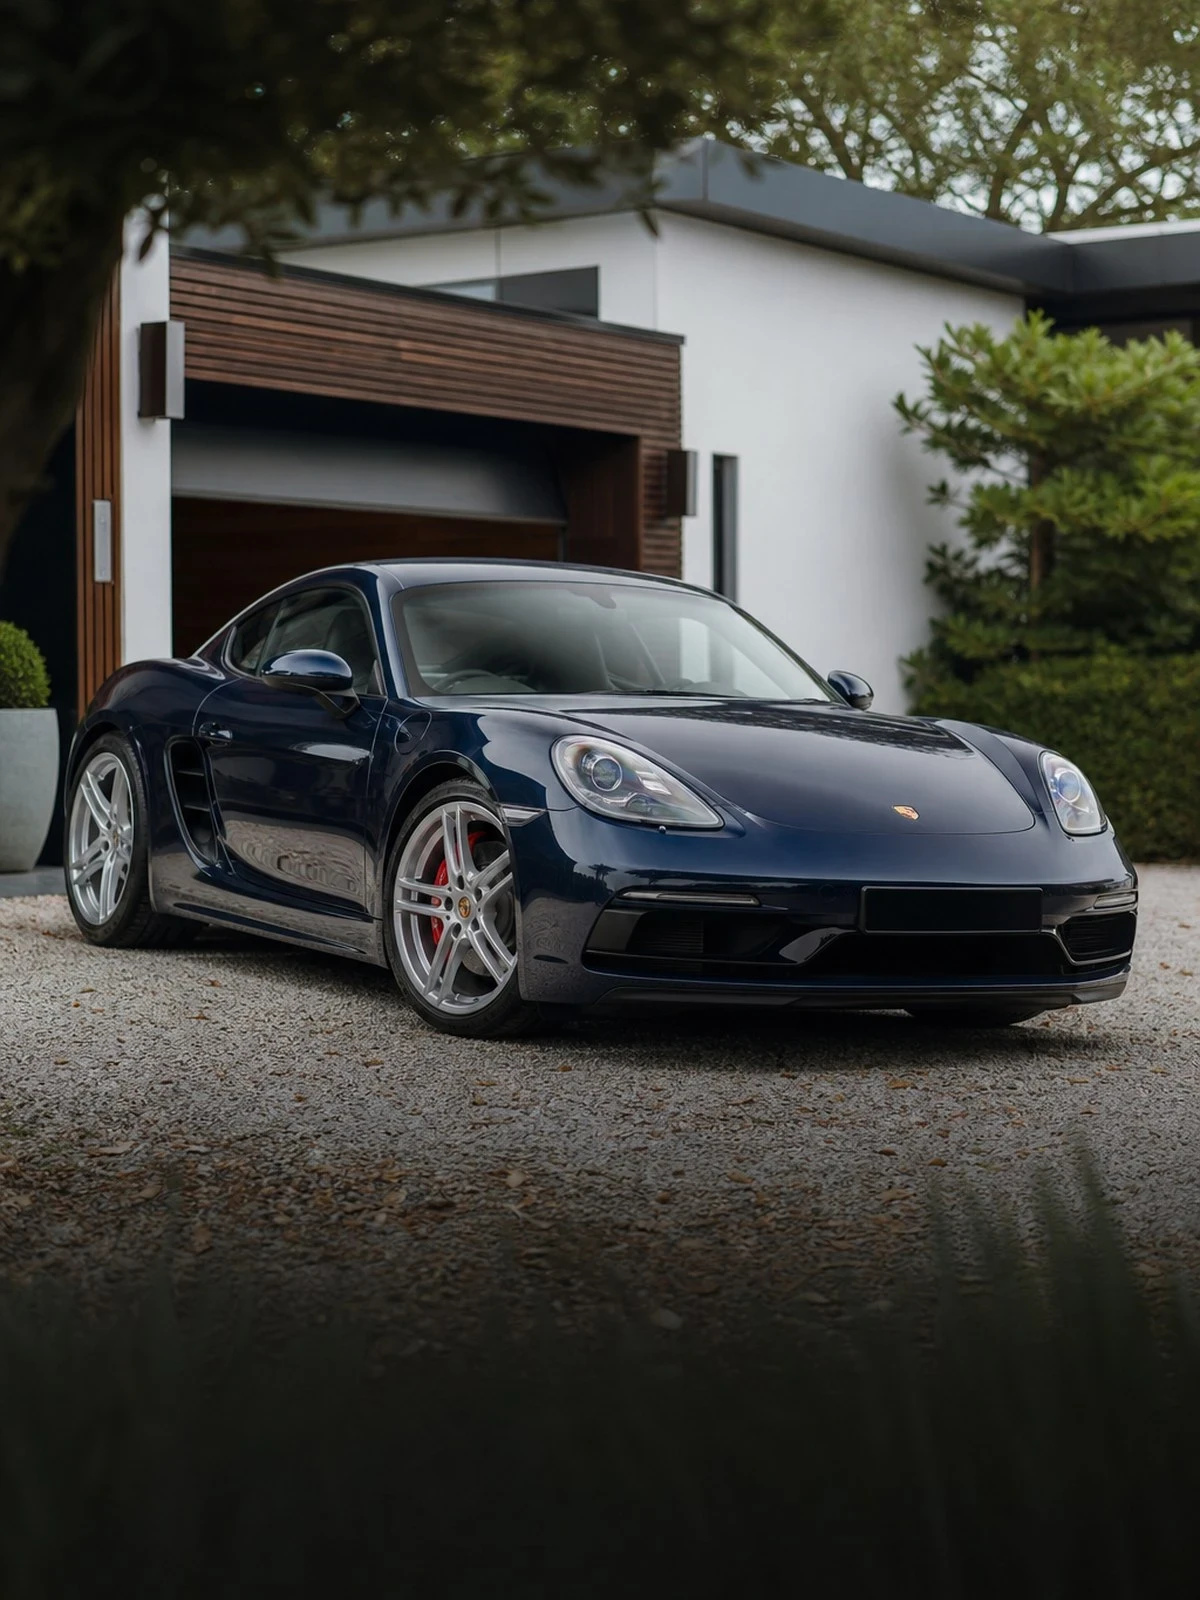
The Cayman actually reaches a circuit more often than the other models, and it is precisely that use that every ordinary motor policy excludes.
This page in another language: Nederlands · Deutsch
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Track days, tuition days and driver training on a closed circuit fall outside the cover, even where no clock is running and there is no competitive element. The exclusion applies to damage to your own car and to liability on the site. If you want to go on the track, take out single-day circuit cover beforehand. Reporting afterwards that it was in fact a tuition day changes nothing in the assessment.
The second point is how the value is made up. With this model the options account for a substantial part of it: ceramic brakes, sports seats, sports exhaust, alloy wheels and the transmission chosen. When settlement is on market value, those only count if they have been declared. For the GTS and GT versions, a valuation is the way to record that build-up; Article 7:960 of the Dutch Civil Code then gives the agreed value its effect.
The third point is standing idle. As a weekend car the Cayman spends much of the year in the garage. That makes a low mileage band achievable, but flat spots on the tyres, a flat battery and seized brakes are not insured damage. See also the open version and insuring sports cars.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your Porsche Cayman | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Every ordinary motor policy excludes use on a circuit, whether it is a track day, a tuition day or timed driver training. That means no cover for damage to your own car, no cover for damage to the track or to other participants, and no cover for recovery from the site. For those days there are separate single-day covers that you arrange beforehand, with their own conditions and their own excess.
Ceramic brakes, sports seats, a sports exhaust, a different wheel package and the transmission chosen lift the value of this model considerably. If they have not been declared, the insurer settles on a standard version if the car is written off or stolen. Declare the options when you take out the policy, with the original order confirmation or invoice. With a GTS or GT version, a valuation is the way to record the build-up watertight.
A weekend car qualifies for a favourable mileage band, but standing idle brings risks of its own. Flat spots on tyres, a discharged battery, brake discs seized by rust and damp in the interior are consequences of not using the car and do not count as a sudden event. Use a trickle charger and a dry, ventilated space. Also check that the storage address you declared is correct and that the security requirements in your policy continue to apply during the period of storage.
Outside the cover: any use on a circuit or closed track, including tuition days; damage while the car is being worked on, dismantled or test-driven after an unapproved modification; undeclared options and accessories; the consequences of standing idle such as flat spots, discharge and corroded brake discs; wear to tyres, clutch and brakes; and diminution in value after a properly executed repair, unless separately insured.
Mid-engine repairs call for specialist knowledge. Not every repairer is allowed to carry them out.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
No. Use on a circuit is excluded under every ordinary motor policy, including a tuition day without timing. The exclusion applies to damage to your own car, to damage to other participants and to the track, and to recovery from the site. For such days you take out single-day circuit cover in advance; you arrange that for the day itself, not afterwards.
Only if they have been declared. Ceramic brakes, sports seats, a sports exhaust and a different wheel package are factory options of considerable value, but the insurer settles on what is on the policy. Provide the order confirmation or invoice when you take out the policy, or have the car valued so that the build-up of the value is recorded.
For those versions, yes. The market value there does not follow the ordinary depreciation pattern and the options list counts heavily. A recognised valuer records the version, options, condition and mileage; under Article 7:960 of the Dutch Civil Code that value is then the starting point when you claim. Note the period for which the report is valid and have a fresh valuation done in good time.
In insurance terms nothing changes, as long as you keep the policy running and comply with the storage requirements. But damage that arises from standing still is not covered: flat spots on tyres, a discharged battery, seized brake discs and damp damage in the interior all count as consequences of not using the car. Use a trickle charger and make sure the storage space is dry and ventilated.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.