

Courier insurance
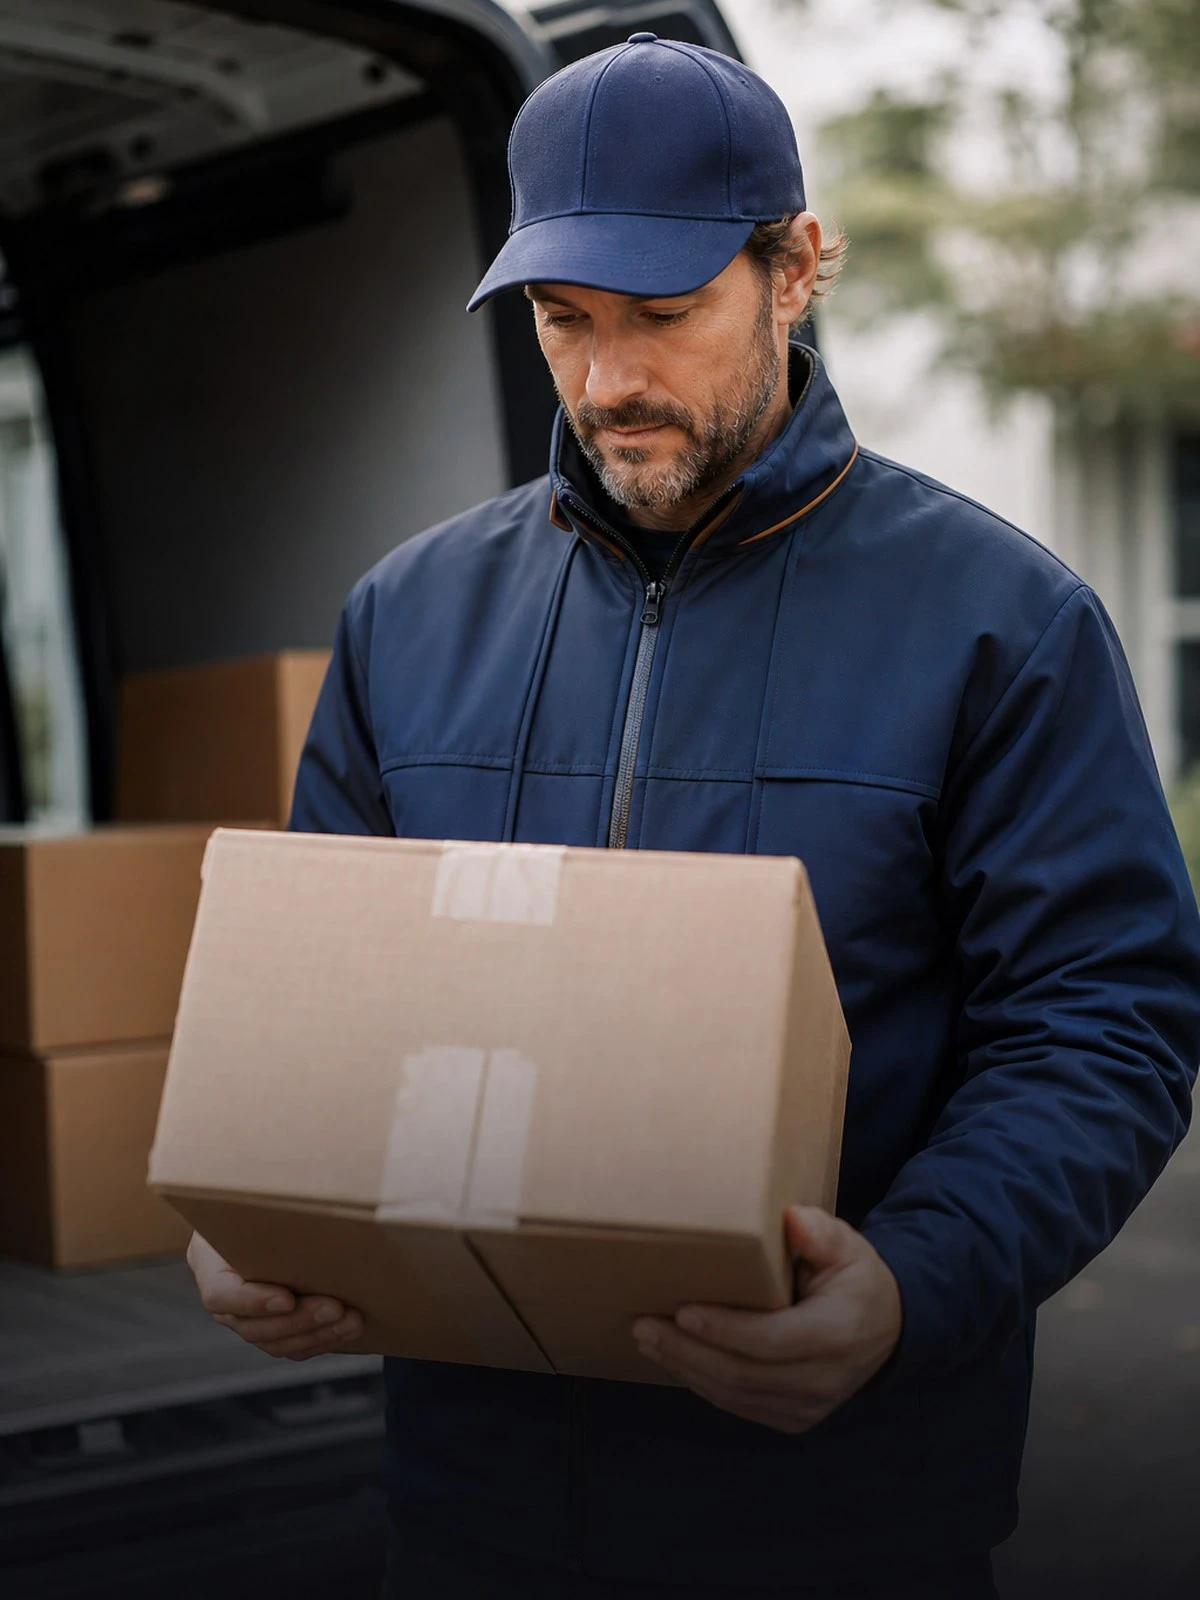
In terms of claims pattern, courier work is a category of its own: a hundred stops a day, brief stops, time pressure and a vehicle that is opened and closed all day long.
- several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands · Deutsch
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
Courier insurance is tailored to parcel transport and express delivery. An ordinary van policy usually excludes this use, because the claims pattern is fundamentally different.
Besides the vehicle, there is liability for the consignments: as a carrier you are liable for loss or damage, within the limits of the AVC or CMR.
This page deals with one part. The overview of all parts is on the main page on business insurance.
Independent, personal, sorted quickly
We compare your van insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Van insurance
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
What to look out for
Declare the use explicitly
Courier work that has not been declared is one of the most common reasons for a claim on a van policy being refused.
Theft from an open vehicle
With quick loading and unloading, the van is often left open. Insurers set requirements as to locking up and leaving consignments unattended.
Liability per consignment
Your liability is limited per kilogram. With small, expensive parcels that is far below the actual value.
Changing drivers
If you work with self-employed drivers or agency workers, check whether they fall under your policy and who is liable in the event of a loss.
What determines the premium
- Number of vehicles
- Number of stops or runs per day
- Area of transport
- Type of consignments
- Claims history and age of the drivers
This information is general in nature and is not personal advice. What is actually covered, including exclusions and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover.
Frequently asked questions
Can I insure courier work on an ordinary van policy?
Usually not. The use differs so much that insurers apply a separate rate and separate conditions to it.
Am I liable for a parcel that goes missing?
As a carrier you are, within the limits of the AVC or CMR. That is an amount per kilogram, not the value of the parcel.
What if I work with self-employed drivers?
Record who is liable for what and check whether they fall under your policy. This is a common gap in courier services.
Is theft during delivery covered?
Only if you comply with the conditions on locking up and leaving consignments unattended. An open van is an exclusion.
Every situation is different. For these situations we have a separate page.
- Compare van insuranceThe main page
- Business van insuranceIn the company name, fit-out, delivery
- Insuring a van for a courier serviceMany stops, changing drivers, load
- Compare courier insurance & save straight away
- Insurance for the Ford TransitVan, load, use
- Insuring a car without no-claims yearsStarting position, building up, alternatives
- Insuring a second carNo-claims years, second-car arrangement, regular driver
- Car insurance for young driversStarting position, regular driver, excess
- Insuring a SmartCompact, town use, low market value