

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to buildings and objects
- Damage caused by passengers
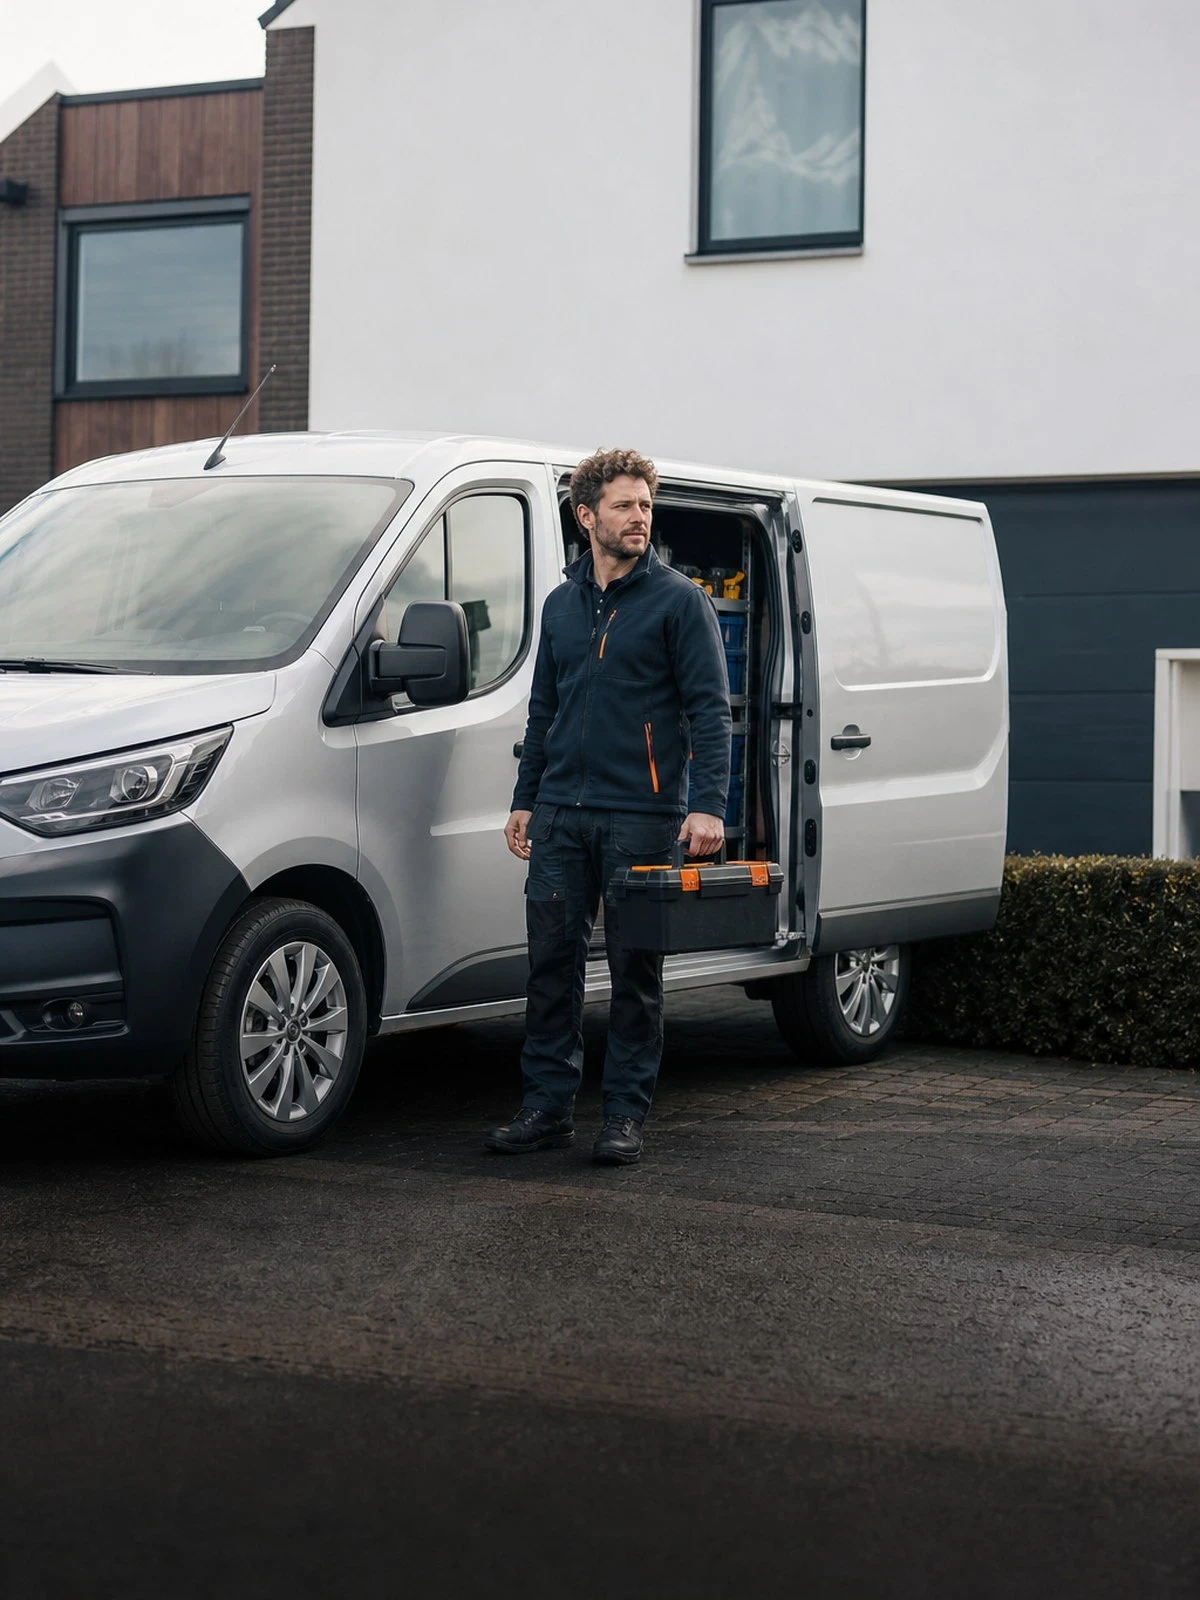
With a van, the difference from a car is not in the bodywork, but in what is in the back and in who all drives it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The ASR van insurance covers the vehicle, not the contents of the load space. If it is broken into overnight, own-damage cover pays for the forced lock and the damaged sliding door, but not for the tools that disappeared. That calls for tools or business contents insurance, often with an overnight clause requiring you to empty the van or park it on an enclosed site.
Anything fitted after delivery only counts if it has been declared: the lining and racking in the load space, a roof rack or ladder carrier, signwriting with your company name, a towbar, a refrigeration unit or an inverter. Otherwise, in the event of an own-damage claim only the bare van is paid for and you pay for the refitting yourself.
If employees drive it, a second layer is added. For damage they cause to third parties during their work you are liable as the employer under Article 6:170 of the Dutch Civil Code, and recovery from the employee himself is only possible in the case of intent or wilful recklessness (Article 7:661 of the Dutch Civil Code). If you tow a trailer behind the van, see trailer insurance.
We compare your van insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Van insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Third-party liability insurance is required by law and covers damage you cause to others with your van, not damage to your own van.
Alongside third-party liability cover, protection against damage to your own car from external causes you cannot prevent.
The most complete cover, including for damage you cause yourself, theft and total loss. We compare ASR's comprehensive version with the market.
What is covered
| What we do | At Finass | Direct with Ansvar |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Provided it is declared |
| One point of contact for claims | Yes | Provided it is declared |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether Ansvar is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
What we do
| What we do | At Finass | Direct with a.s.r. |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Sometimes |
| One point of contact for claims | Yes | Sometimes |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether a.s.r. is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
This overview concerns our service, not the cover. What is actually covered is set out in the policy conditions and on the insurer's insurance card (verzekeringskaart); you receive both before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The most valuable items in a van are usually in the back. Those contents do not fall under the motor policy: own-damage cover pays for the break-in damage to the door, lock and sliding door rail, and that is where it stops. Arrange separate cover for tools and stock and read the overnight clause carefully. If it requires you to empty the van or park it indoors, a theft from a place on the street is not an insured event.
A fitted-out load space represents considerable value that is not included in the list price. Declare racking, floor and wall lining, a towbar, ladder carrier, refrigeration or an inverter at the outset and have this recorded on the policy. Otherwise, in the event of a total loss you are only paid for the vehicle. Lettering with your company details also counts as a modification and is a real cost item when a side panel is repaired.
If a member of staff causes damage to someone else with the van, you are liable for it under Article 6:170 of the Dutch Civil Code. Recovery from the member of staff himself is only possible in the case of intent or wilful recklessness; beyond that, Article 7:661 DCC blocks it, including for the excess. If the member of staff is injured himself in traffic, the duty of care under Article 7:611 DCC also comes into play, along with the question of whether you have arranged proper insurance.
Falling outside the cover are: the load, the tools and the stock in the load space; courier and delivery work where that use has not been declared; hire or subleasing to third parties; damage to the goods themselves arising during loading and unloading; damage caused intentionally, excluded under Article 7:952 of the Dutch Civil Code; and driving without a valid licence or under the influence, in which case the insurer recovers from you the amounts paid to third parties.
Replacement transport after a claim Stay mobile with replacement transport.
This is what people ask us most.
No. Van insurance covers the vehicle. The contents of the load space fall outside it. Break-in damage to the lock and door is paid for, but the tools that have gone are not. For those you take out separate tools or business contents cover. Pay attention to the overnight clause, which often requires the van to be empty or parked indoors.
As the employer, you are liable for damage your member of staff causes to third parties during work. That follows from Article 6:170 DCC. Recovering the loss from him is only possible in the case of intent or wilful recklessness, because Article 7:661 DCC protects the employee. As a rule, you therefore cannot pass on the excess either.
Yes. Racking, lining, a refrigeration unit, towbar or ladder carrier are not included in the list price. Without a declaration, the insurer pays for the bare van in the event of a total loss and you pay for the refitting yourself. Have the added value recorded on the policy and update it when you have the van fitted out again.
Only if this has been declared. Delivery and courier work involve many short trips, many stops and a higher claims pattern than service journeys, and insurers rate that separately. If your use changes over time, report it; otherwise the insured risk differs from reality and the payout may be reduced.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.