

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
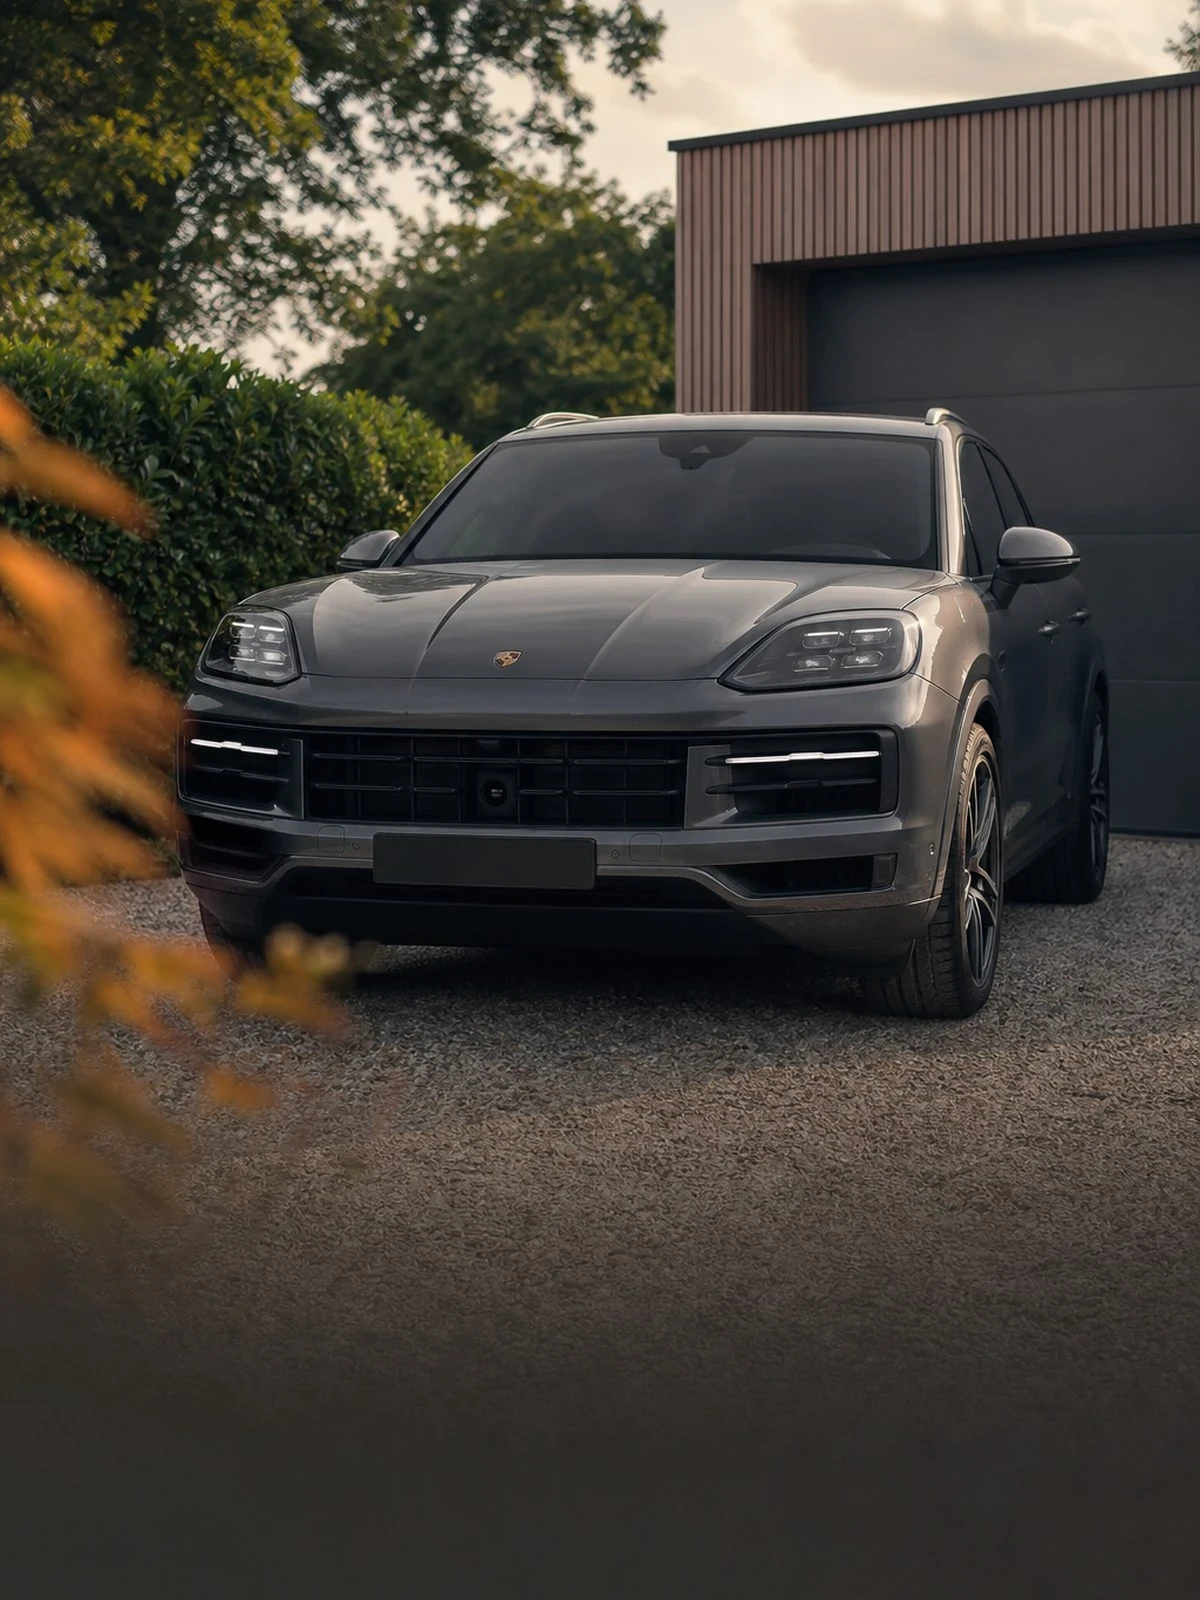
The Cayenne is used as an everyday car and often tows a trailer. In risk terms that makes it more like a heavy SUV than a sports car.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
High annual mileage, family use and a trailer on the back: that is the pattern of use that shapes this policy. Weight and size work through into the cost of claims. Wide tyres on large wheels are damaged by a kerb, air suspension and ride-height control are expensive to replace, and the sensors and cameras all round require calibration after every body repair. Damage that looks modest therefore comes out high on the estimate.
If you tow a trailer, boat or horsebox, liability is dealt with through the third-party liability cover of the towing vehicle, for as long as the trailer is coupled. The insurance requirement under Article 2 of the Dutch Motor Insurance Liability Act (WAM) relates to the motor vehicle. Damage to the trailer itself is not included. If you want the trailer or its contents insured, you need separate trailer cover.
The third point is theft. Cars in this class with keyless entry are vulnerable to relay attacks, in which the signal from your key is extended. Insurers therefore set requirements: a tracking system with a live subscription, and the surrender of all keys when you claim. If a key is missing, an investigation follows and the payment can come under pressure.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your Porsche Cayenne | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A heavy SUV on low-profile tyres with large wheels is damaged by a kerb or a deep pothole more easily than its size suggests. A buckled wheel, a damaged air spring or a bent stub axle are each expensive items. Under comprehensive cover that damage is covered, but tyre damage on its own, without further damage to the car, is excluded under many policies. Wear to tyres and brakes is always outside the cover.
Damage you cause to third parties with a coupled trailer falls under the third-party liability cover of the car. The trailer itself and the load in it are not insured by that. For those you take out separate cover. Also mind the permitted towing weight and the requirements for securing the load: damage resulting from overloading or from an incorrectly secured load is rejected, even if the driving was otherwise correct.
This class almost always comes with a clause setting security requirements: an approved alarm and a tracking system whose subscription must remain live. Keep the keys away from the outside wall, preferably in a shielded pouch. When theft is reported, the insurer asks for all the keys. If you cannot produce one, further investigation follows and payment can be refused because there are no signs of forced entry.
Outside the cover: use on unmade ground away from the public road, such as off-road drives and off-road training; damage caused by overloading or an incorrectly secured load; damage to the trailer itself and to the load; tyre damage on its own without other damage to the vehicle; wear to tyres, brakes and suspension; and theft where not all keys can be handed in or the tracking system was not in operation.
Air suspension and ceramic brakes push the repair bill up considerably.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
For liability, yes, as long as the trailer is coupled to the car: that damage runs through the third-party liability cover of the towing vehicle. The trailer itself and the load are not insured under the motor policy. If you want to cover a horsebox, boat trailer or caravan against theft and damage, you take out separate trailer insurance for it.
Usually an approved alarm system combined with a tracking system whose subscription remains live. That requirement appears as a clause on the policy. Keep keys in a shielded pouch and not near the front door, because in a relay attack the signal from the key is extended. If the subscription to the tracking system lapses, the theft cover attached to it falls away.
A buckled wheel or damaged suspension falls under comprehensive cover, subject to the excess. For the tyre itself the position is different: many policies exclude tyre damage on its own where there is no other damage to the vehicle. Wear to tyres is always excluded. So have a knock against a kerb assessed, because the consequential damage to the chassis and air suspension is the biggest item.
Away from the public road, usually not. Off-road drives, off-road training and use on a closed site fall outside the cover under most motor policies, even without a competitive element. If you drive along an unmade access road or a yard used as a road, the position is different. If you are in doubt, put the situation to us in advance; reporting it afterwards does not help.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.