

Third-party liability insurance
- Damage to other vehicles
- Injury to third parties
- Damage to objects
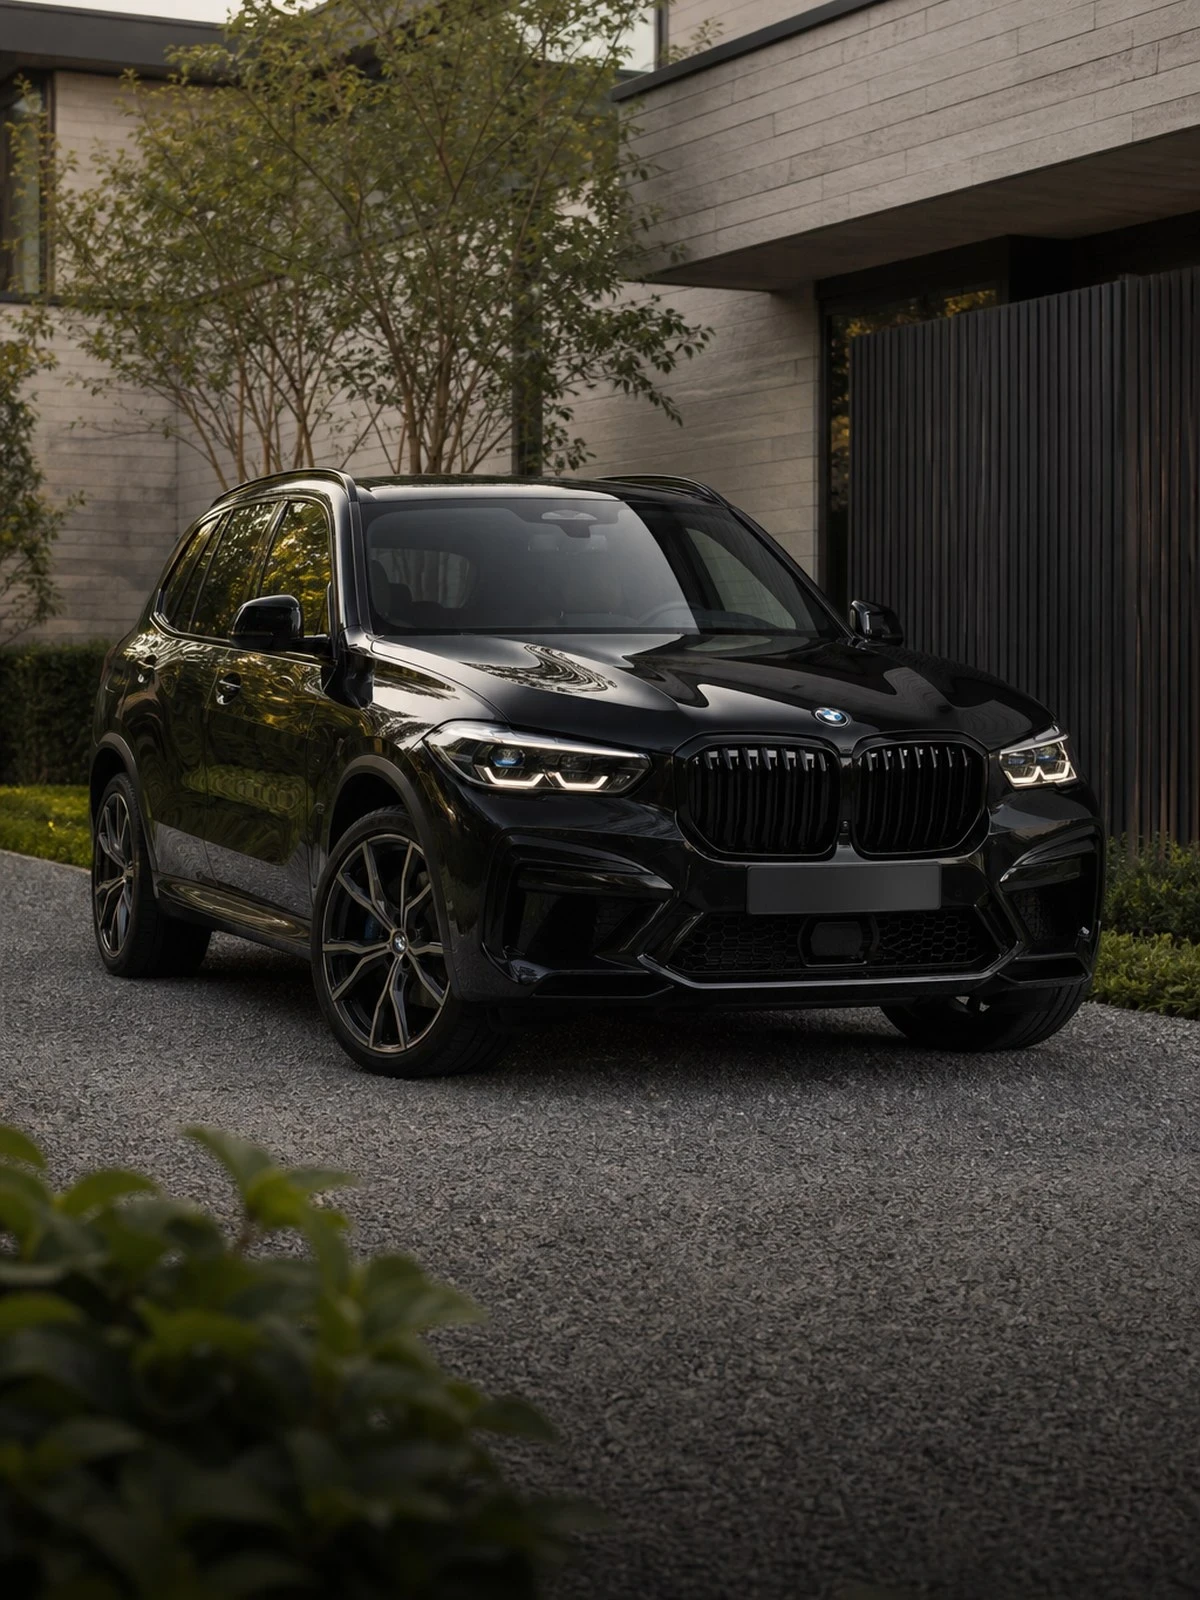
The X5 rarely drives alone: a caravan, a trailer, a bike rack and a full family change what this policy has to cover.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The X5 is a heavy SUV used in the Netherlands mainly as a family car and a towing vehicle. That towing weight is the main reason to read the policy more carefully than for an ordinary passenger car. For liability purposes, a coupled trailer or caravan falls under the towing vehicle: if the caravan causes damage to someone else, the X5's third-party liability cover pays for it. Damage to your own caravan does not fall under it.
The second point is the repair. Air suspension, four-wheel drive, matrix headlamps and a series of cameras and radar sensors make an apparently limited collision expensive. After a windscreen is replaced the driver assistance systems have to be recalibrated. That belongs to the glass claims arrangement but not every repairer may carry it out.
Third, the value in the first years. On this model the difference between the purchase price and the market value is large in absolute terms, which is why the replacement value as new or purchase price arrangement is more relevant here than on a cheaper car. If you drive the car for business, also look at Insuring a BMW 3 Series.
We compare your youngtimer insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Youngtimer insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vehicle. Not your own vehicle.
Also, damage to your own vehicle from external causes.
Including damage to your own vehicle through your own fault.
What is covered
| Situation | Third-party liability | Third-party liability + fire and theft | Comprehensive |
|---|---|---|---|
| Damage to another vehicle | Yes | Yes | Yes |
| Theft of your BMW X5 | No | Yes | Yes |
| Windscreen damage or stone chips | No | Yes | Yes |
| Storm, hail and fire damage | No | Yes | Yes |
| Driving into a bollard yourself | No | No | Yes |
| Track use, wear and intent | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
As long as the trailer is coupled, the X5's third-party liability insurance covers the damage the combination causes to third parties. That follows from the scheme of Article 2 of the Dutch Motor Insurance Liability Act (WAM). If the trailer comes loose and then causes damage, it becomes more complicated and liability is considered under Article 6:162 of the Dutch Civil Code. Damage to the caravan itself, and to its contents, calls for separate caravan or trailer insurance.
Behind the windscreen sit cameras for lane assist, traffic sign recognition and emergency braking systems. After the glass is replaced they have to be reset on an aligned rig. If a firm does not do that, or does it incompletely, the systems work unreliably without your noticing. Choose a repairer that carries out the calibration itself and falls within your insurer's network; outside that network a higher excess often applies.
On a young car the insurer sometimes pays out in a total loss on the basis of the new price or the purchase price instead of the market value. Such an arrangement applies for a limited period after first registration, often only for the first owner, and sometimes only where the damage exceeds a certain share of the value. Read which variant appears on your policy schedule. The differences between companies are large here.
Outside the cover remain: luggage, tools and personal belongings in the car, because those belong on a home contents or travel insurance. Also excluded are damage from driving off the surfaced road or across open ground, damage from loading above the permitted weight or the permitted towing weight, wear to parts such as air suspension bellows, and damage caused intentionally or through wilful recklessness (Article 7:952 of the Dutch Civil Code).
Air suspension and four-wheel drive make repairs more expensive than on a saloon in the same price bracket.
Not every company applies the same policy for this make. With unusual versions, the question is not what it costs but who will accept it.
This is what people ask us most.
For liability it is: as long as the caravan is coupled, the car's third-party liability insurance covers the damage the combination causes to others. Damage to the caravan itself, to its contents and to the awning does not fall under it. For that you take out separate caravan insurance with own-damage cover. Also check whether your policy applies in the countries you take the caravan to.
In most glass claims arrangements, setting up the driver assistance systems belongs to the replacement and is included. The condition is that the repairer may and can carry out the calibration. If you choose a firm outside your insurer's network, a higher excess usually applies and sometimes payment up to a maximum. Ask in advance whether the calibration is included in the quotation.
That differs per insurer and is set out on your policy schedule. Usually it is a limited period counted from first registration, after which depreciation applies and then market value. Often the arrangement applies only to the first owner and only where the repair costs exceed a certain share of the value. If you buy the car second-hand, do not assume the arrangement moves with it.
Usually not. Many conditions exclude damage arising from use off the public surfaced road, or from off-road driving. If you stay within normal use, for instance an unsurfaced access track, there is usually no problem. If you drive onto a beach, a forest track or an off-road site, read your conditions first. Damage from getting stuck and the cost of recovery often also falls outside the cover.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.