

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
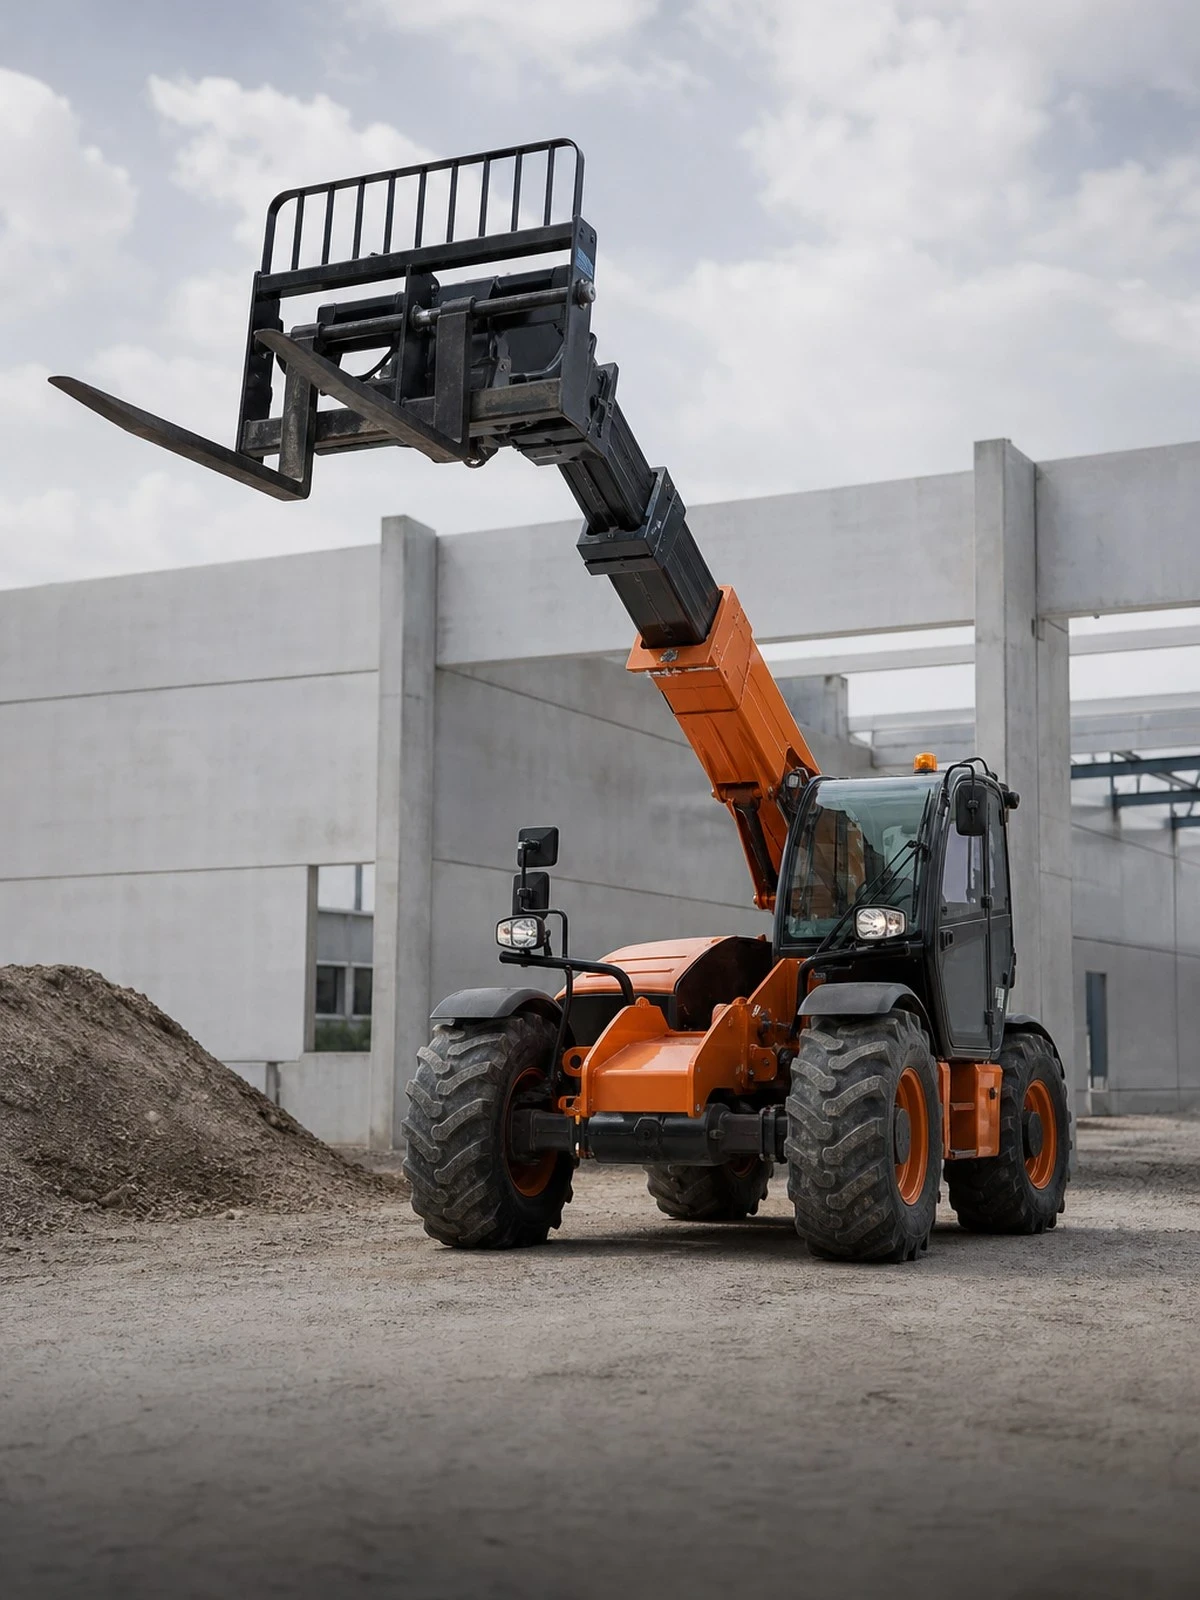
A telehandler becomes a different machine as soon as you change the attachment: with forks it is internal transport, with a hook it is lifting work and with a work platform it is carrying people.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The insurance question with a telehandler is not about the machine but about the tool hanging from it. If you drive with forks, the risk profile is that of internal transport and the load falls under care, custody and control. If you fit a jib or a hook, you are lifting and you need a lifting liability section. If you put a work platform on it, you are lifting people and the strictest requirements of all three apply.
Insurers assess those three applications separately. A policy applied for on the basis of fork use does not automatically cover lifting on the hook, and a machine that is not approved for lifting people certainly does not cover the work platform. If the actual use departs from what was declared, that affects the duty of disclosure in Article 7:928 of the Dutch Civil Code and the payout under Article 7:930 of the Dutch Civil Code.
In reality this means that taking stock of a telehandler takes longer than with a forklift truck or a aerial work platform. State on the application which attachments you own, which you hire and how often each regime occurs. That is also your protection: if it is declared, the argument after a loss is not about whether the use was permitted, but only about how the damage arose.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Forks, a rubble bucket, a jib, a hook, a concrete skip and a work platform are six different machines on one chassis. Every attachment has its own load chart and its own cover regime. Declare them separately with their value, including the hired ones. If lifting is done with an attachment that has not been declared, the question is not how carefully you worked but whether the use was insured at all.
A work platform on a telehandler is permitted where the machine and the platform are approved as a combination and the machine is equipped for it. If that approval is missing and someone falls, there is no cover and you are also left empty-handed under Article 7:658 of the Dutch Civil Code. Improvising with a pallet, a bucket or a borrowed basket is the most common breach on the building site.
As soon as the load hangs free, it can swing and affect stability. Insurers then expect a load moment limiter that works and an operator who knows what the reach does with the load. The damaged load falls under care, custody and control and is only covered with a lifting liability section, just as with a mobile crane. Without that section you pay for the load yourself.
Bypassing or ignoring the load moment limiter counts as wilful recklessness under Article 7:952 of the Dutch Civil Code. Wearing parts such as tyres, chains and hydraulic hoses are covered nowhere. Damage to the load on the forks is care, custody and control. And driving with the boom extended under load, outside what the load chart allows, is an operating error that leads to a reduced settlement where the machine overturns.
Lifting people with a telehandler is allowed only with an approved work platform and subject to conditions. Outside those limits the cover falls away.
Tracks, tyres, blades, teeth and cutting edges are wear parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
Only with a work platform approved together with the machine and with a telehandler that is equipped for it. If that combination is missing, it is not permitted and there is no cover if someone falls. Report the use of a work platform on the application. It is one of the few things an insurer wants to know in advance and will certainly check afterwards.
Not as standard. Both on the forks and on the hook the load is in your care, and property in your care, custody and control is excluded. For lifting work a lifting liability section is needed, for carrying third parties' goods a care, custody and control extension. Choose the sum insured on the basis of the most valuable load you move regularly.
Yes, with their value. They are not automatically insured and together often represent a considerable part of the total. The attachment also determines which regime of use applies. If you hire an attachment for a single job, report that in advance; hired plant falls under your policy only if it is expressly insured.
On a closed building site there is no public road and Article 2 of the Dutch Motor Insurance Liability Act (WAM) does not apply. As soon as you leave the building site or cross a public road, it does. Because telehandlers regularly travel between locations, cover attached to a registration number is almost always needed. Your liability on the work site itself is unaffected by that.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.