

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
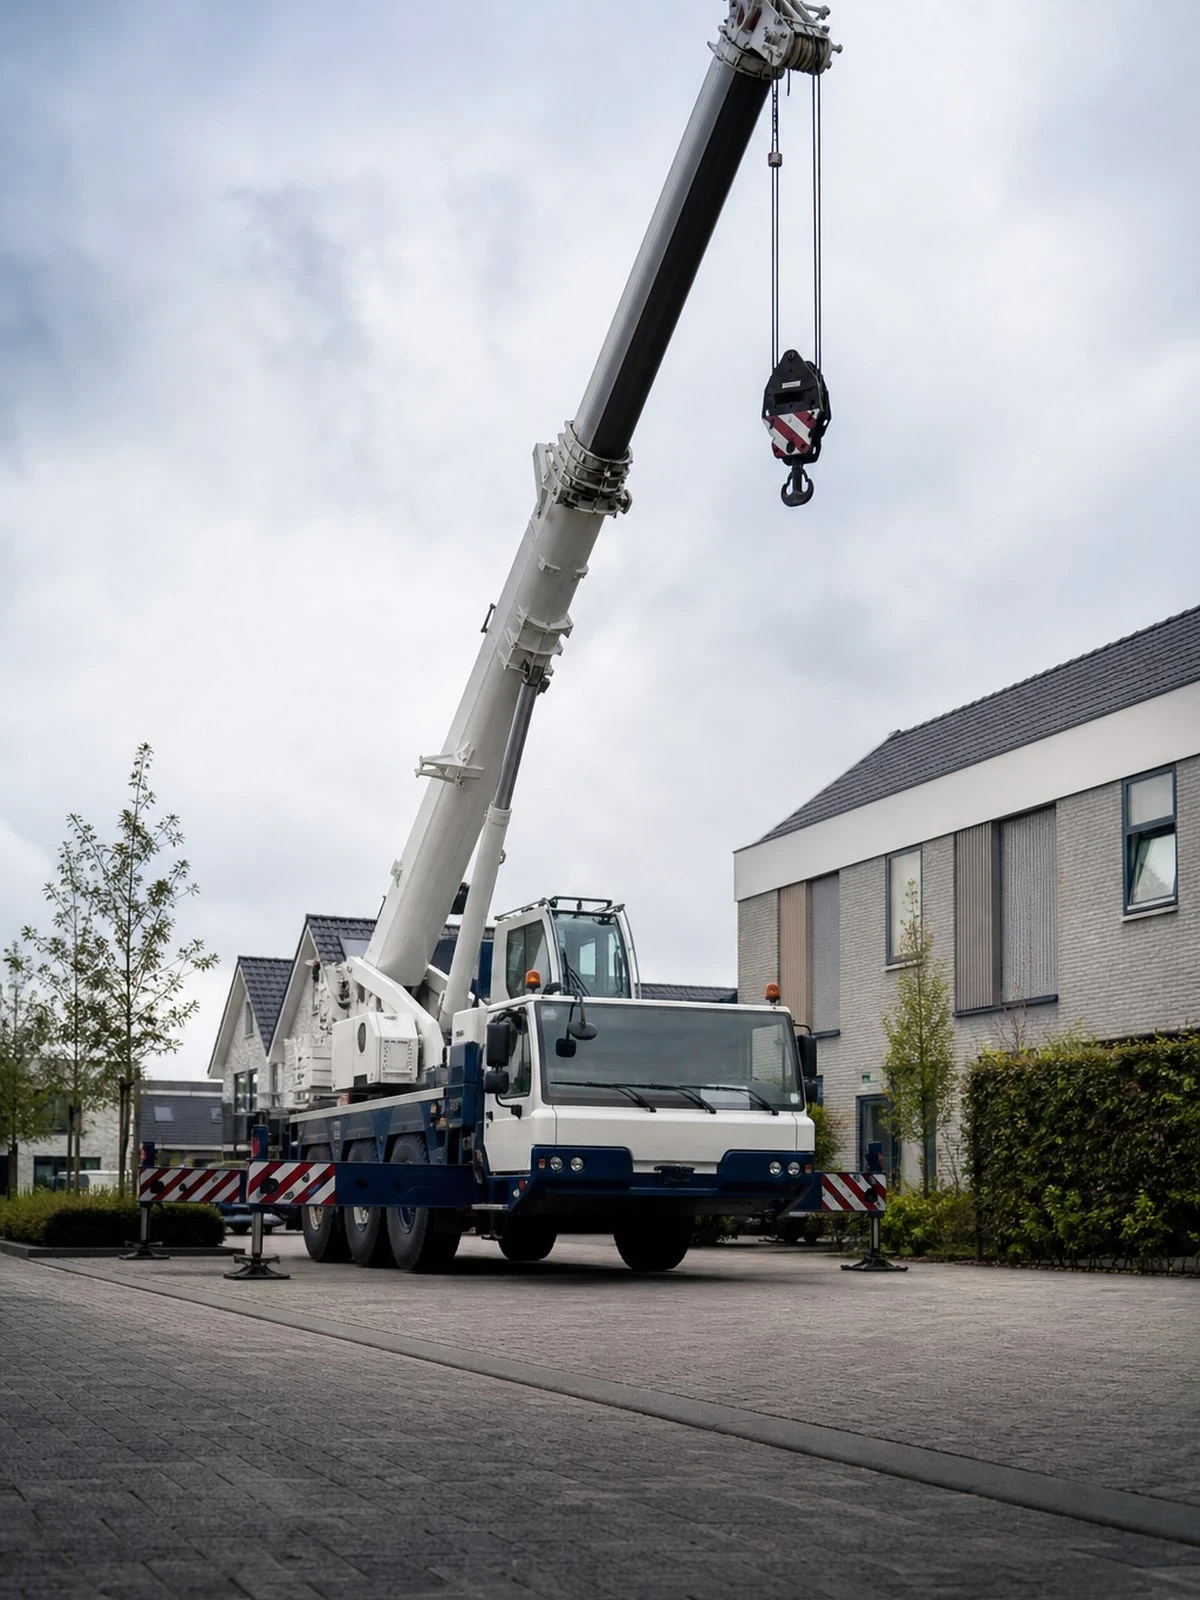
A mobile crane earns its money standing still on outriggers, and it is precisely that set-up that determines what damage you can cause and who bears it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A mobile crane lives in two legal worlds in a single day. On the way to the job it is a motor vehicle and the compulsory insurance under Article 2 of the Dutch Motor Insurance Liability Act (WAM)applies. As soon as the outriggers are out and the boom goes up, the machine is doing work for which liability cover for plant and machinery is needed. Insurers do not always draw that boundary in the same place, and that is exactly where a loss falls between two policies.
The second point is the set-up position. The outrigger pressure of a mobile crane is a point load on a small area. Beneath that pad there may be a sewer, a basement deck, the rim of a manhole or a newly laid cable duct. If it gives way, it is not your machine that is at issue but someone else's site, and then Article 6:162 of the Dutch Civil Code comes into play with the question of whether you should have checked the bearing capacity.
What surprises most crane owners: the load on the hook is never an own-damage claim. Own-damage cover insures the crane, not what hangs from it. A dormer that swings against a facade or an installation that ends up on the floor is property that was in your care and that is excluded as standard. So we first arrange how your plant and machinery insurance is built up on that point.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The whole crane plus the load comes down on four outrigger feet. If there is a basement deck, a manhole, a drainage pipe or newly laid paving underneath, it subsides and the damage is to your client's site. Insurers ask about the use of outrigger pads or track mats and about whether you requested the bearing capacity. Record that with a photograph of the set-up before you start.
Own-damage cover pays for damage to the crane itself. A load that tips, hits a facade or comes loose is damage to a third party's property that was in your care during the work. That is the classic care, custody and control exclusion and without a separate extension it is the most expensive uninsured part of your job. Set the level of that extension to match the heaviest and most valuable load you lift in a normal week.
On the way to the location the compulsory motor cover under Article 2 of the Dutch Motor Insurance Liability Act (WAM)applies. During the lifting, the working risk cover applies. If the crane drives into a viaduct or canopy with the boom raised, the question is which regime governs that moment. If you work above or beside the public road, record which traffic measures were taken; without barriers a claim quickly moves towards contributory fault.
If you lift outside the load chart or with condemned slings, it is no longer a matter of unfortunate coincidence. Keep for each job the lift plan, the outrigger pressure calculation and the inspection certificates for slings, shackles and hooks. Steel ropes, tyres and brake linings are wearing parts and are paid for nowhere; deferred maintenance on the boom or hydraulics is an independent ground for exclusion.
This is what people ask us most.
No. Own-damage cover protects the crane, not what hangs from it. A load that falls or swings into something is damage to someone else's property that was in your care, and that falls under the care, custody and control exclusion. Only a separate care, custody and control extension covers it. If the same movement also hits a facade or a parked car, that does fall under the ordinary liability cover.
That is damage to your client's site and therefore liability, not own-damage. The insurer looks at whether you asked about the bearing capacity of the set-up position and whether you used outrigger pads or track mats. If you could have known there was a cellar or manhole underneath and ignored it, the argument about due care under Article 6:162 of the Dutch Civil Code becomes difficult.
The lorry itself falls under the compulsory motor insurance. Lifting with the mounted crane is work, and working risk or plant and machinery cover is needed for that. Many commercial vehicle policies do not include it. So we always check whether the superstructure is insured and whether the crane appears on the policy with a value of its own.
Their absence does not automatically make the loss uninsured, but you lose your defence. The first question after an incident is what preparation there was. Without a plan, a calculation and valid inspection certificates for the lifting gear it is clear that you cannot show you acted with due care, and the injured party can recover from you considerably more easily.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.