

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
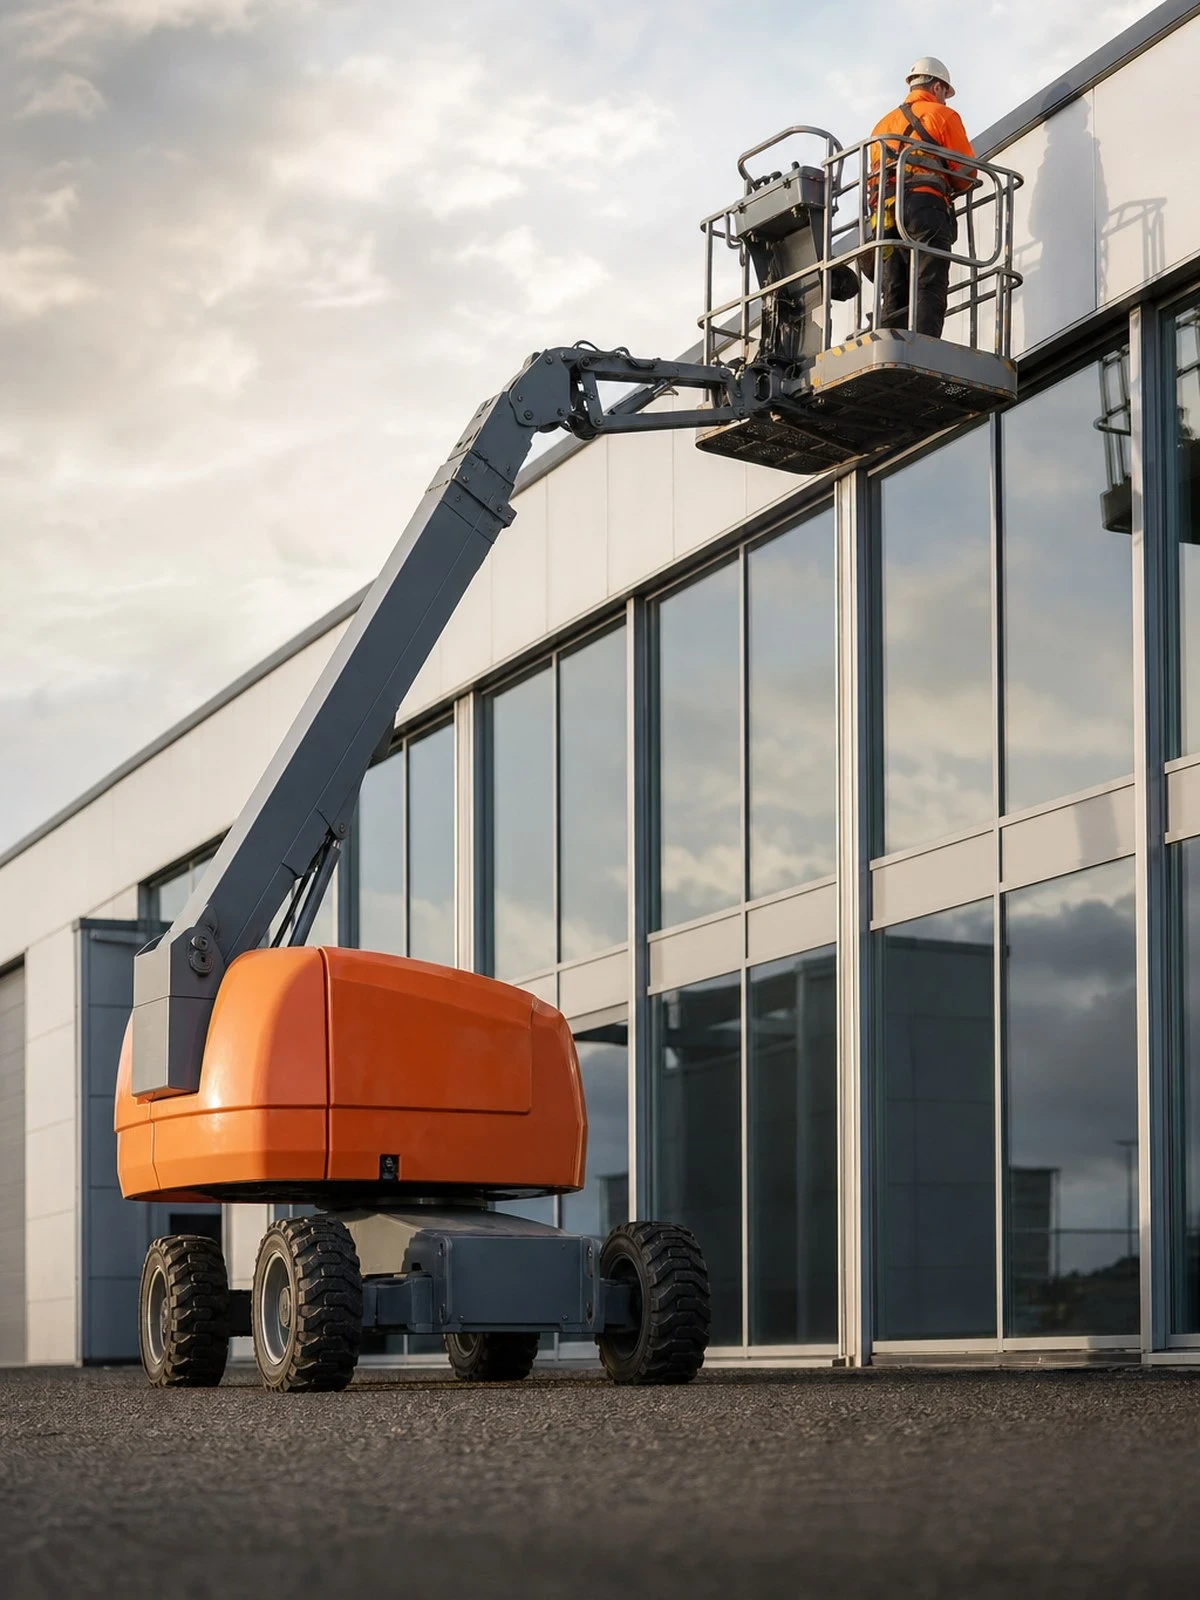
On an aerial work platform there is a person in the basket. That changes the character of the risk: it is not the damage to the machine but the injury that determines how large an incident becomes.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
An aerial work platform is the only machine in this group built to lift people. That shifts the centre of gravity of the insurance. Own-damage to the machine is manageable; injury to the person in the basket or to someone underneath is not. If it is your own employee who is hurt, it falls under employer's liability and Article 7:658 of the Dutch Civil Code places the burden of proof on you.
Two scenarios cause the majority of serious losses: the machine overturns, or something falls out of the basket. Overturning almost always arises from the ground, from failing to extend the outriggers fully, or from continuing to work in too much wind. Falling objects are liability, not own-damage: a tool that lands on a parked car or a passer-by affects your liability section and not the machinery cover.
The aerial work platform is also the machine most often hired in or out. If you work with hired plant, have it established who carries the own-damage risk and whether the hire contract places it with you. If you hire in with an operator, liability shifts again. For machines used to lift loads rather than people, see insuring a telehandler.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
In an articulated boom platform a harness with a short lanyard is prescribed, because the basket can catapult in a collision. If the harness is missing or attached in the wrong place and someone falls, you are left empty-handed under Article 7:658 of the Dutch Civil Code: you have to show that you gave instruction and exercised supervision. Record the work instructions and the issue of personal protective equipment.
Most overturning incidents arise because an outrigger is standing on a manhole cover, a soft verge or an unsupported basement deck. Wind speed is the second cause: every machine has a maximum wind speed and continuing to work above it is a deliberate choice that comes back during claims handling. Record for each job the set-up position, the outrigger pads used and the weather conditions at the start.
A tool, cladding panel or bucket of sealant that falls out of the basket causes damage below. That is not own-damage but liability, and where a passer-by is injured the figure rises quickly. If you work above public areas, that calls for barriers, securing of tools and, where necessary, a ground marshal. Set the sum insured to match what is beneath you, not the value of the machine.
Using an aerial work platform to lift loads is improper use and therefore excluded. Letting people step out onto a roof or facade scaffold falls outside the cover with many insurers, unless that is expressly permitted. Working with an expired inspection certificate or a bypassed safety device affects the acceptance conditions. Wearing parts such as tyres and hydraulic hoses fall outside own-damage cover everywhere.
Damage and injury caused by tools falling out of the basket is liability, not own-damage. Make sure the sum insured is set to match.
Tracks, tyres, blades, teeth and cutting edges are wear parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
No. Injury to your own employee runs through employer's liability on the business policy, not through the machinery cover. Article 7:658 of the Dutch Civil Code requires you to show that you provided safe equipment, instruction and supervision. Where a hired-in worker or a self-employed professional (zzp'er) works under your direction, that duty of care usually applies in full.
Not without more. An aerial work platform is certified for people, not as lifting equipment. If you use the basket or the boom to lift material, that is improper use and the insurer can refuse cover. If you want to lift both people and loads, a machine with the right approval and a suitable lifting section is the route to take.
That depends on the hire contract. Hire companies often place the own-damage risk with the hirer, with an excess per event. Your own policy covers hired plant only if that is expressly insured. Check that before the first hire. Afterwards the hire condition turns out to be binding and the cover absent.
Important enough to record. Every machine has a maximum permissible wind speed in the manual. If the platform overturns while work continued above that limit, the insurer treats it as a deliberate choice and can reduce the settlement under Article 7:952 of the Dutch Civil Code. Record the conditions at the start of the work.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.