

Business contents
- At replacement value as new
- Fire, water and burglary
- Tenant's improvements separately
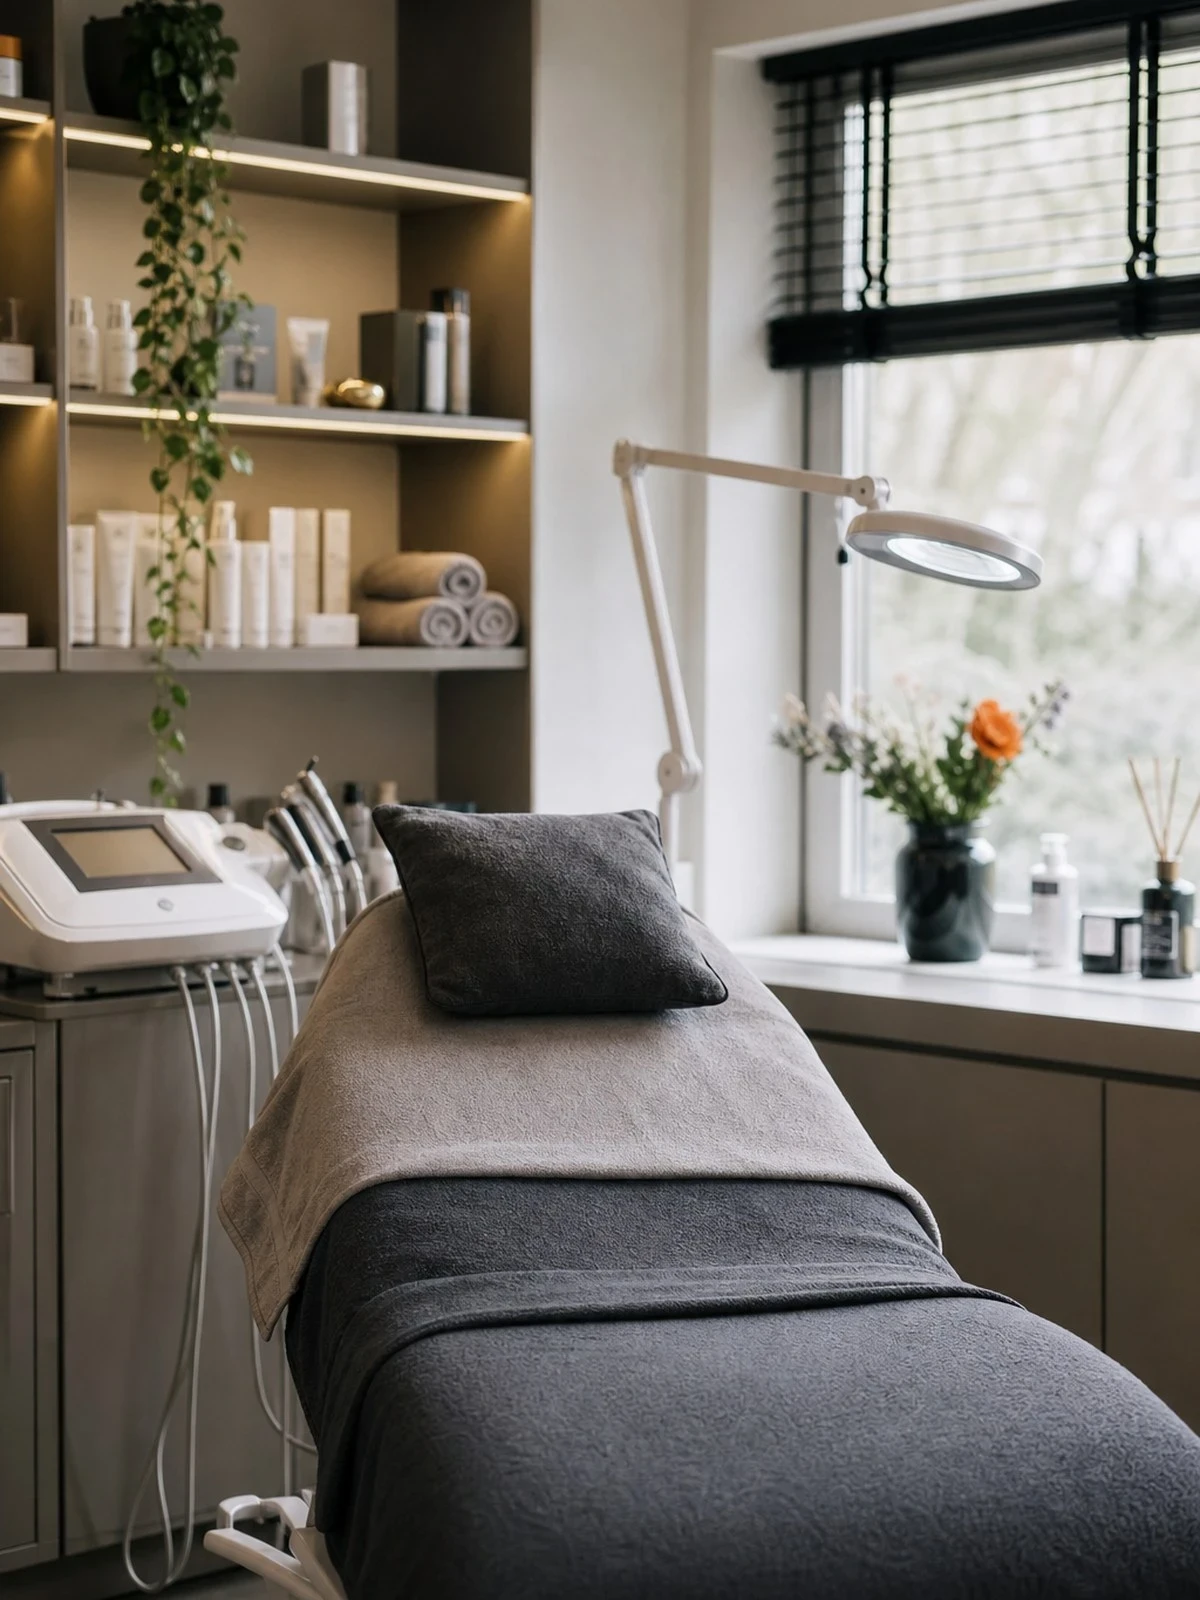
In a beauty salon most of the value sits in a handful of treatment devices that the insurer wants to see listed individually.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
In a salon, business contents are the treatment chair or couch, the cubicle fit-out, the basins, the mirror wall and above all the equipment: laser, IPL, radiofrequency, microdermabrasion, a steamer or a pedicure chair. Goods are the products you sell or use up. Those two items appear separately on the policy, because they are paid on a different basis: business contents usually at replacement value as new, the product stock at cost price.
What makes a salon unusual within this insurance is the ratio between value and floor area. A few square metres of cubicle can hold more equipment than a whole office floor. Insurers assess such a risk not on a round figure but on a list: make, type, serial number and year of manufacture for each device, often with a maintenance or inspection certificate. Without that declaration you end up arguing about the duty of disclosure in Article 7:928 of the Dutch Civil Code.
Never more than the actual loss is paid. That is the indemnity rule under Article 7:960 of the Dutch Civil Code. Standard exclusions are wear and tear and inherent defect of the equipment, customers' belongings, money in the till, and spoilage of products without a separate extension. If you work from rented premises, declare the tenant's improvements separately.
We compare your business contents insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business contents insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Machinery, equipment, furniture and fixed fittings.
Trading stock, raw materials and finished products.
What is excluded as standard.
What is covered
| Situation | Business contents | Goods |
|---|---|---|
| Fire and smoke damage | Yes | Yes |
| Burglary with signs of forced entry | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Customers' property being worked on | No | No |
| Spoilage due to refrigeration failure | Sometimes | Sometimes |
| Wear and deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Insurers rarely accept a salon with laser, IPL or radiofrequency equipment on a global figure. They ask for a specification per device with make, type, serial number and purchase date, and regularly for a current maintenance or inspection contract. That declaration is not a formality. If a device is missing from the list, it is not insured, and an undeclared treatment method touches on the duty of disclosure in Article 7:928 of the Dutch Civil Code. Update the list after every purchase.
An IPL lamp that loses power after thousands of flashes, a worn handpiece or a burnt-out component is not damage within the meaning of the policy. What is covered is a sudden, unforeseen event; wear and tear, inherent defect and gradual deterioration remain excluded, however expensive the part. If you want to cover the equipment itself failing, you need separate machinery breakdown cover or a service contract from the supplier.
Peels, ampoules, serums and consumables are goods and are paid at cost price, not at the price you sell them for in the salon. For products that must be kept cool, spoilage after a power cut only counts if you have expressly agreed that extension. Opened packaging and products whose use-by date had already passed fall outside any payment, even after an otherwise insured event.
Outside the cover remain the jewellery, coats and bags customers leave in the cubicle, the money in the till, and damage to a customer's skin. The last of these is injury and belongs with your public and employers' liability insurance. The cubicle walls, basins and lighting you had installed yourself in rented premises are also not automatically included. You declare those as tenant's improvements.
This is what people ask us most.
Yes. Almost every insurer wants this equipment listed individually on the policy, with make, type and serial number, and makes maintenance or periodic inspection a condition. A device not on the specification is not insured against fire or theft. If a treatment method is added later, report it; otherwise it turns out afterwards that you failed to declare a risk.
No. Business contents insurance covers damage from events such as fire, water and burglary, not a device failing through inherent defect, wear and tear or an electronic fault. Machinery breakdown cover or a service contract from the supplier is the right route for that. If you cannot work without that device, also look at business interruption or additional costs insurance.
Not on this policy. A bag, coat or watch a customer takes off during treatment is not your own business contents. If something goes missing or is damaged, you end up at your liability insurance, and there an exclusion usually applies for items in your care, custody and control. If you do want to cover that, a separate third-party property section is needed.
No. Home contents insurance covers private belongings. The treatment chair, equipment and stock are business assets and fall outside it, even though they are in your own home. Also declare the business use to your home insurer. An undeclared salon at home is a well-known reason why a household claim is ultimately not paid.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.