

Business contents
- At replacement value as new
- Fire, water and burglary
- Tenant's improvements separately
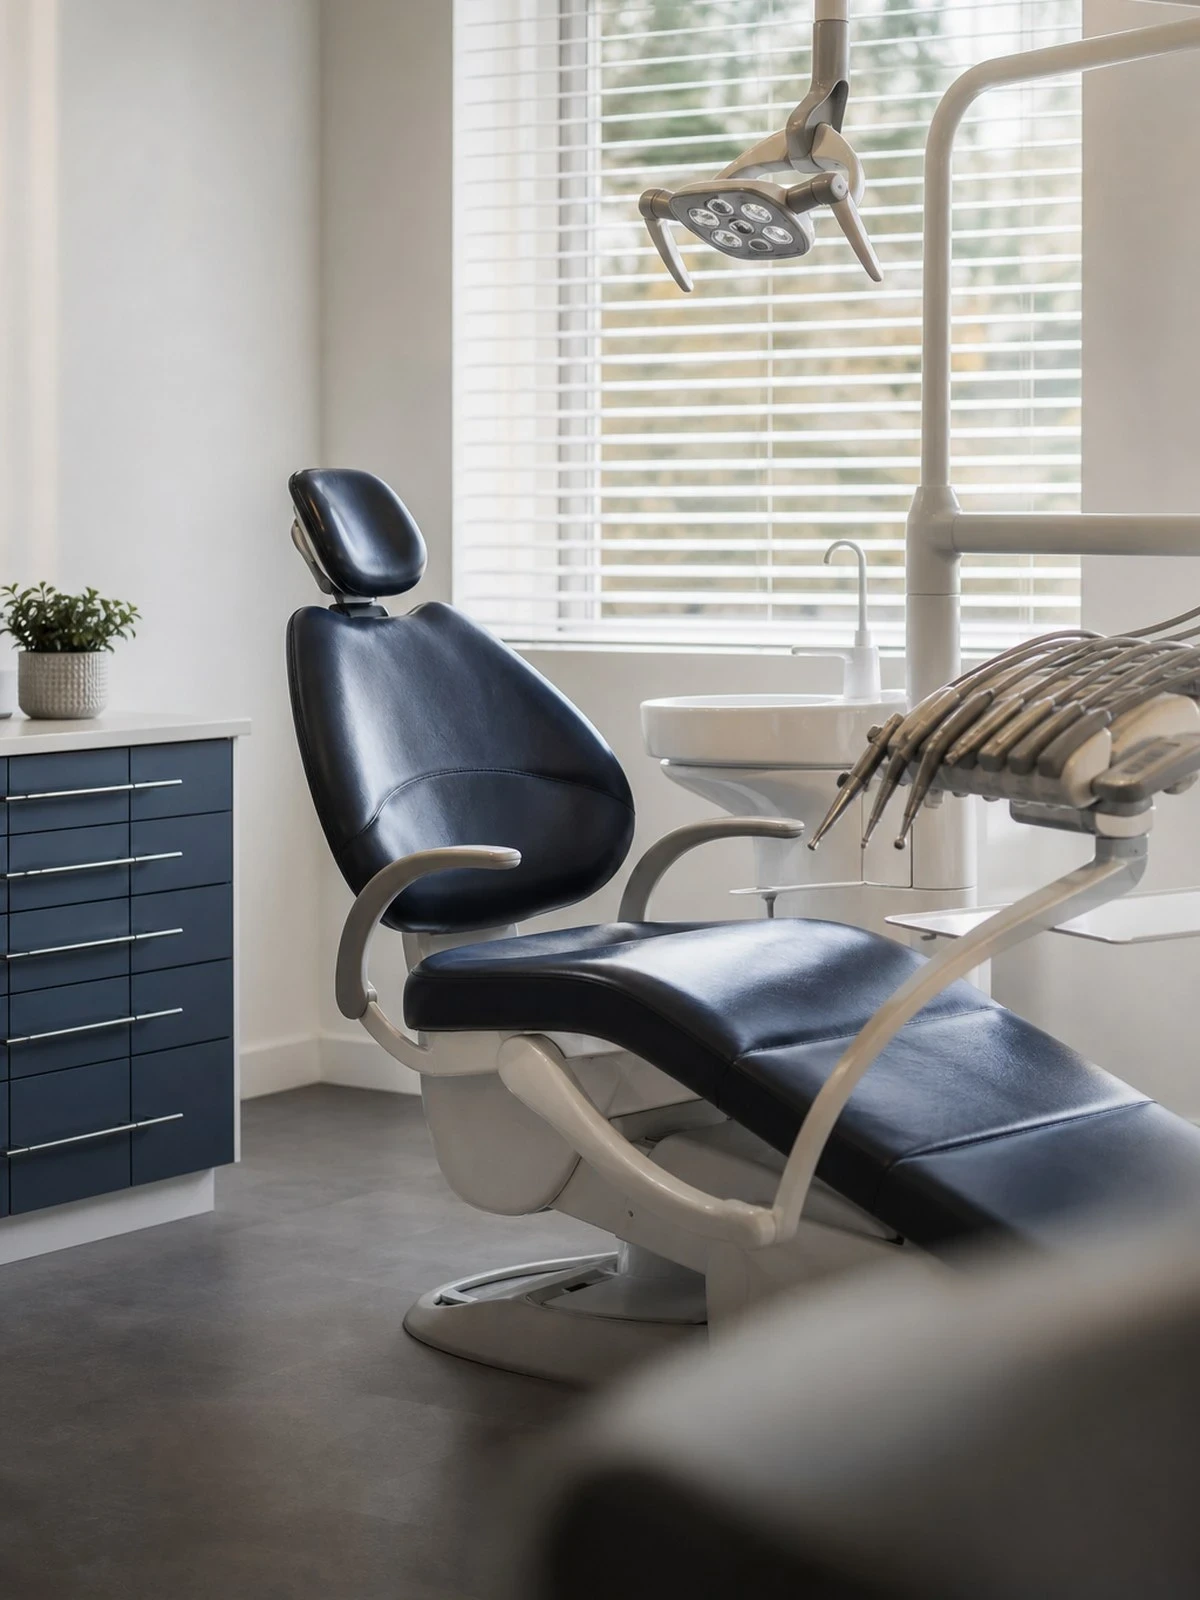
In a practice, the problem is not the purchase price but replaceability: equipment ordered to specification and calibrated is not back in place within a week.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The business contents of a practice consists of examination and treatment equipment, the treatment chair or examination couch, a steriliser, the fridge for medication, the IT hardware and the fit-out of the reception and waiting room. The goods are consumables and medication. The amount is often modest. The consequences of failure are not.
That is where a practice differs from a shop or office. Equipment is installed, connected and calibrated, and the delivery time for a replacement unit often runs into weeks or months. The policy pays for the property, not for the time during which you cannot treat patients. Also ask expressly whether recalibration and any required inspection after a loss are included in the payment; that is not a given.
Outside the cover remain: records, software and the cost of entering data again, medication that spoils after refrigeration failure without the spoilage section, patients' property in the waiting room, and wear and tear or inherent defect of equipment. If you work from home, declare that activity to your home insurer as well; that touches on Article 7:928 of the Dutch Civil Code.
We compare your business contents insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business contents insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Machinery, equipment, furniture and fixed fittings.
Trading stock, raw materials and finished products.
What is excluded as standard.
What is covered
| Situation | Business contents | Goods |
|---|---|---|
| Fire and smoke damage | Yes | Yes |
| Burglary with signs of forced entry | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Customers' property being worked on | No | No |
| Spoilage due to refrigeration failure | Sometimes | Sometimes |
| Wear and deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A made-to-order unit that has been set up and calibrated is not replaced from stock. Between the loss and restarting sit the quotation, delivery, installation and inspection. Match your business interruption insurance to that real timescale and not to a standard period. With the property cover, also ask whether the costs of reinstallation, recalibration and any mandatory inspection after a loss are included.
A practice keeps products that only remain usable within a narrow temperature band. Spoilage is not an automatic part of the cover but a separate section, with requirements: a temperature alarm, a minimum duration of failure and demonstrable temperature records. Also note the difference between a fault in your own fridge and a failure of the public supply. Not every policy covers both situations.
Business assets do not fall under private home contents insurance, even if the treatment room is the former study. Declare the practice activity to your home insurer, otherwise an undeclared business activity also affects your household cover. If you rent premises, the fit-out you had installed yourself is your tenant's improvements and belongs on the policy as its own amount.
Patient records, software and the hours spent entering data again are not property. There is data or cyber cover for that. Patients' property in the waiting room falls outside, as do wear and tear and inherent defect of equipment and spoiled medication without the section. Report claims within the period stated in the conditions and keep the faulty equipment until the loss adjuster has seen it (Article 7:941 of the Dutch Civil Code).
This is what people ask us most.
No. Business contents insurance pays for repair or replacement of the property itself. The turnover you lose while waiting for a replacement unit falls under business interruption. Choose an indemnity period there that matches the delivery time of your equipment, including installation and inspection. With specialist units that period is usually longer than owners assume in advance.
Only with the spoilage section. It sets requirements about temperature monitoring, alarms and the minimum duration of failure, and often distinguishes between a fault in your own fridge and an external power cut. Record the temperature demonstrably. Without logging it cannot be established afterwards how long and how far the temperature rose.
Not with home contents insurance alone. That covers private belongings. Your equipment, instruments and stock are business assets and fall outside. Take out commercial business contents insurance for them and declare the practice activity to your home insurer. An undeclared business activity is a well-known ground for refusing a claim for damage to the home itself.
Not by this insurance. Data is not property. The hardware is paid for, the reconstruction of records is not. There are cyber and data covers for that, which can also include the costs of recovery, forensic investigation and notifying those affected. Also make sure you have a back-up off the premises, because otherwise a fire hits the server and the back-up in one go.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.